
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
Xerocon 2018
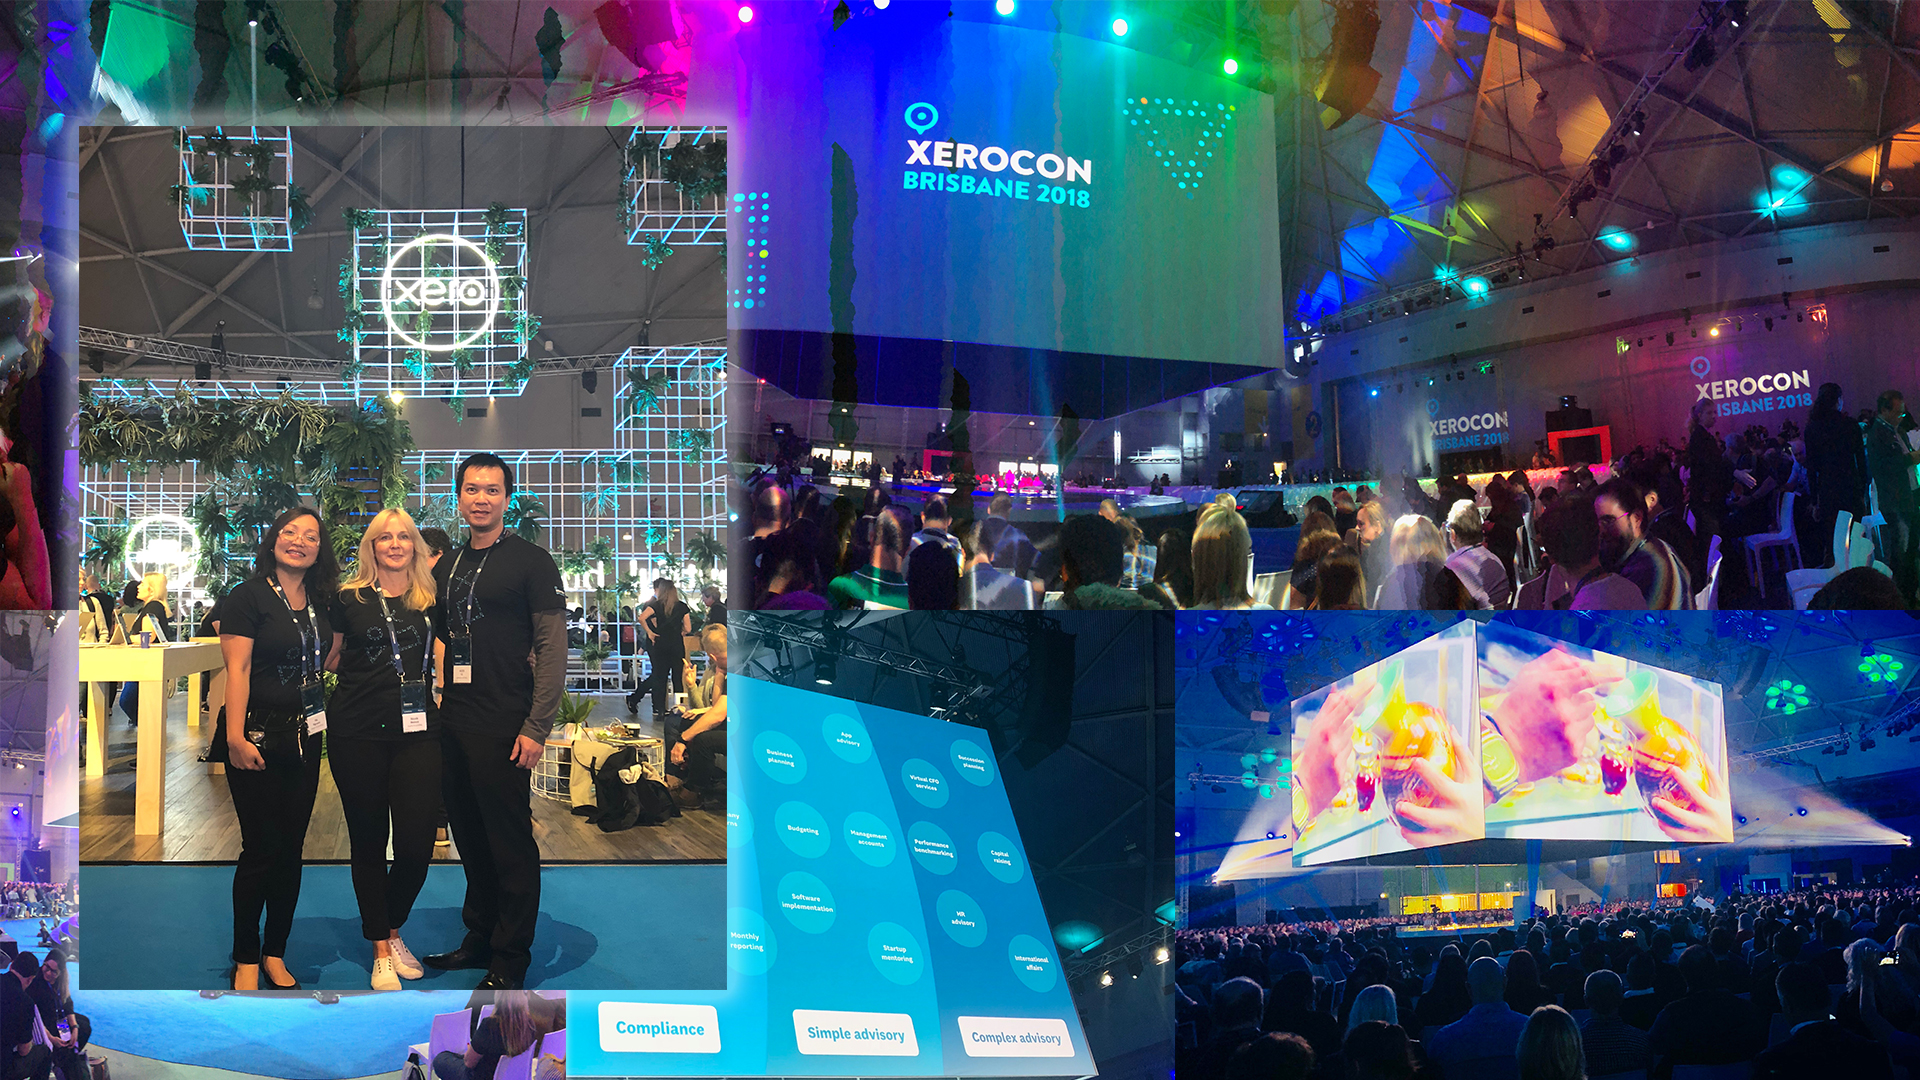
Each year XeroCon attracts a lot of forward thinking accountants and business advisors to attend, and this year was no exception. Held in Brisbane this 2-day event was hosted by the cloud accounting leaders and gathered some of the best speakers in the industry.
With AI and technology changing very fast XeroCon was an amazing opportunity for our team to gain an insight from keynote speakers as well as the chance to chat to the experts on the latest trends.
Whether you are new to cloud or someone who is thinking about the transitioning process to cloud accounting please give us a call. We are happy to discuss with you all the exciting benefits of using latest technology to support your business, saving your time and costs.
Client Alert – August 2018

Government launches new service to simplify business registrations
The government has officially launched a new stand-alone Business Registration Service, providing a simpler and clearer way to register a business. The service is available at www.business.gov.au.
The service can be used for things such as applying for an Australian Business Number (ABN) or goods and services tax (GST) registration. It is for people starting a new business as a sole trader, company, partnership, trust or superannuation fund. Existing businesses with an ABN can also use the service to apply for tax registrations such as GST.
The Business Registration Service has reduced the average time taken to obtain a business and associated licences to under 15 minutes.
Illegal early access to super: ATO warning about scammers
The ATO has issued a warning to be aware of scammers who promise to organise access to people’s retirement savings for a fee. Unscrupulous promoters encourage people to illegally access their super early to help with expenses such as the purchase of a car, paying off debts, sending money to overseas relatives and taking a holiday. The ATO has seen promoters, mostly in western Sydney, targeting people with small to medium super balances, those involved in local community groups, and those who may not have engaged with their super before being approached.
ATO gives small businesses the chance to seek independent review of ATO audit position
From 1 July 2018, the ATO is running a 12-month pilot to extend its independent review service to certain small business taxpayers. This means those taxpayers can have the ATO’s audit position on their tax affairs independently reviewed.
The independent review is conducted by an officer from the ATO’s Review and Dispute Resolution business line. This officer will not have been involved in the audit and will bring an independent “fresh set of eyes” to the case. The independent reviewer will consider the documents setting out the taxpayer’s position and the ATO audit position. They will schedule a case conference with the taxpayer and the ATO audit officer, generally within one month of receiving the taxpayer’s review request.
The ATO audit team will finalise the audit in accordance with the independent reviewer’s recommendations. The pilot is currently limited to small business disputes involving income tax audits in Victoria and South Australia.
Transacting with cryptocurrency: updated ATO info
The ATO says a capital gains tax (CGT) event occurs when a person disposes of their cryptocurrency (eg Bitcoin). A disposal can occur when someone:
- sells or gifts cryptocurrency;
- trades or exchanges cryptocurrency (including the disposal of one cryptocurrency for another cryptocurrency) – if the cryptocurrency received cannot be valued, the capital proceeds from the disposal are worked out by using the market value of the cryptocurrency disposed of at the time of the transaction;
- converts cryptocurrency to fiat currency like Australian dollars; or
- uses cryptocurrency to obtain goods or services.
If you need assistance with the tax treatment of cryptocurrency, or the ATO’s record-keeping requirements for taxpayers who are involved in acquiring or disposing of cryptocurrency, please contact our office.
Tax gap for individuals is $8.8 billion, says ATO
The ATO has estimated that the net “tax gap” for individuals not in business in 2014–2015 is approximately 6.4%, or $8.8 billion. The gap is an estimate of the difference between the tax the ATO collects and the amount that would have been collected if every one of these taxpayers was fully compliant with the law.
In other words, the ATO estimates that individuals not in business paid over 93% of the total theoretical tax payable in 2014–2015.
ATO warns about scammers at tax time
The ATO has warned taxpayers to be on “high alert” for tax-related scams. ATO Assistant Commissioner Kath Anderson said the most common scam is still the “fake tax debt” phone scam, but the ATO is also seeing an increase in “fake refund” or “refund for a fee” scams, and email and SMS scams enticing people to click a hyperlink, download a file or open an attachment.
Scammers frequently claim to be from the ATO and taxpayers should be wary of any phone call, text message, email or letter about a tax refund or debt, especially if they were not expecting it.
Income tax residency rules for individuals: Board of Taxation recommends reform measures
The Board of Taxation has publicly released its initial report on its review of Australia’s income tax residency rules for individuals. The Revenue Minister said the Board found that the current individual tax residency rules require modernisation and simplification. The Board also identified opportunities for tax arbitrage, for example where individuals become “residents of nowhere” when they leave Australia and do not become tax residents of another jurisdiction.
The report considered whether the current rules (largely unchanged since 1930) are sufficiently robust to meet the requirements of the modern workforce, address the policy criteria of simplicity, efficiency, equity and integrity, and take into account a significant number of cases heard since 2009 relating to individual residency. The Revenue Minister has asked the Board to consult further on some key recommendations.
Retirement income covenant needs more flexibility: KPMG
KPMG has released a submission in response to the Treasury position paper on the proposed retirement income covenant announced as part of the 2018–2019 Budget. The proposed covenant will require trustees of superannuation funds (including self managed superannuation funds) to formulate a retirement income strategy for fund members. This requirement is aimed at supporting the government’s development of a comprehensive income products for retirement (CIPR) framework.
Illegal phoenix activity costs billions; new Phoenix Hotline
The ATO has released a new report on the economic impacts of potential illegal phoenix activity. It estimates that the annual direct impact of illegal phoenix activity on businesses, employees and the government was between $2.85 billion and $5.13 billion for the 2015–2016 financial year.
The government has also established a new Phoenix Hotline to combat phoenixing activity and to protect compliant Australian workers and businesses. Employees, creditors, competing businesses and the general public can confidentially provide information about possible phoenix behaviour via the hotline on 1800 807 875 or the ATO website. Disclosures will be protected.
Super funds deliver healthy returns for 2017–2018
The median “growth” superannuation fund delivered a healthy investment return of 9.2% for 2017–2018, with the top spot going to Hostplus with a return of 12.5%, according to superannuation ratings firm Chant West. Growth super funds are those with a 61–80% allocation to growth assets.
Every fund in the growth category had positive returns, with even the lowest performer delivering a 6.5% return. Growth funds have delivered nine consecutive years of positive returns, averaging about 9% a year, said Chant West senior investment manager Mano Mohankumar.
GST exemption for offshore sellers of hotel bookings to be removed: draft legislation released
The Treasurer has released draft legislation to ensure offshore sellers of hotel accommodation in Australia calculate their GST turnover in the same way as local sellers from 1 July 2019.
Under the proposed changes, offshore suppliers of rights to use commercial accommodation (eg hotels) in the indirect tax zone (broadly, Australia) will be required to include these supplies in working out their GST turnover. If the supplier’s GST turnover equals or exceeds the registration turnover threshold, GST must be remitted for supplies that are taxable supplies.
Client Alert – July 2018
Business lending practices in spotlight at Royal Commission
Bank lending practices for small and medium enterprises (SMEs) were in the spotlight when the Financial Services Royal Commission (FSRC) held its third round of public hearings in late May. These hearings focused on the conduct of financial services entities providing credit to SMEs.
SMEs are an important sector of the economy – over two million SMEs account for more than 65% of private sector employment. The Royal Commission considered issues with SME lending practices by reference to case studies involving ANZ, Bank of Queensland, CBA, Westpac and Suncorp.
The next round of the Royal Commission’s public hearings focuses on issues affecting people in remote and regional communities, including farming finance, natural disaster insurance, and interactions between Aboriginal and Torres Strait Islander people and financial services entities.
Personal tax cuts now law
The legislation to enact the Government’s seven-year personal income tax reform plan, as announced in the 2018 Federal Budget, passed Parliament on 21 June 2018.
Under the plan, a new non-refundable Low and Middle-Income Tax Offset (LMITO) will be available from 2018–2019 to 2021–2022, providing tax relief of up to $530 to low-income individuals for each of those years. The new offset will be in addition to the existing low-income tax offset (LITO). The top threshold of the 32.5% tax bracket will increase from $87,000 to $90,000 from 1 July 2018.
In 2022–2023, the top threshold of the 19% bracket will increase from $37,000 to $41,000 and the LITO will also increase.
The top threshold of the 32.5% bracket will then increase from $90,000 to $120,000 from 1 July 2022.
The legislation passed without amendments, although some had been raised in the Senate that would have prevented increasing the top threshold of the 32.5% bracket from $120,000 to $200,000 from 1 July 2024, removing the 37% tax bracket completely. This third step of the seven-year plan will now go ahead under the new tax law. And finally, taxpayers will pay the top marginal tax rate of 45% for taxable income exceeding $200,000.
GST property settlement online forms available
From 1 July 2018, purchasers of newly constructed residential properties or new subdivisions must pay the related GST directly to the ATO as part of the settlement.
The ATO says property transactions of new residential premises or potential residential land that involve GST to be paid directly to the ATO on or before settlement will require purchasers or their representatives to use the following online forms:
- Form one, GST property settlement withholding notification, is used to advise the ATO that a contract has been entered into for new residential premises or potential residential land that requires a withholding amount. This form can be submitted any time after a contract has been entered into and prior to the settlement date.
- Form two, GST property settlement date confirmation, is used to confirm the settlement date and can be submitted at the time of settlement and when the payment has been made to the ATO.
Depending on which state or territory the property is acquired in, the purchaser’s representative can include a conveyancer or a solicitor.
Major ATO focus on work-related clothing and laundry this tax time
This tax time, the ATO will be closely examining claims for work-related clothing and laundry expenses. Clothing claims are up nearly 20% over the last five years and the ATO believes many taxpayers are making mistakes or deliberately over-claiming. Around a quarter of all clothing and laundry claims in recent years were exactly $150 – the amount claimable without a specific requirement to keep detailed records about the work-related clothing expenses.
TIP: The ATO has issued a stern reminder that the $150 threshold is not a “safe amount” that everyone can claim. We can help make sure your tax return claims are done right – contact us to find out more.
Advisory Board to help clamp down on the black economy
The Government is establishing a new Advisory Board to support its reform agenda to disrupt the black economy.
The term “black economy” refers to people and businesses who operate outside the tax and regulatory systems, or who are known to the authorities but do not correctly report their tax obligations.
The Advisory Board will include members of the private and public sector who will provide strategic advice and contribute to a report every five years about new threats emerging in the black economy.
The Government’s related actions to date have included a $10,000 limit on cash transactions, a comprehensive strategy to combat illicit tobacco, reforms to the ABN system, restricting government procurement to businesses that have acceptable tax records, and $315 million in additional funding to the ATO to increase its enforcement activity against black economy behaviour.
Superannuation system: Productivity Commission draft report
The Productivity Commission has released a draft report that recommends a range of changes to improve Australia’s superannuation system.
With default funds being tied to the employer and not the employee, many people end up with another super account every time they change jobs. Currently, a third of accounts (about 10 million) are unintended multiples, meaning that Australians pay excess fees and insurance premiums totalling $2.6 billion every year. According to the Commission, fixing these problems would lift retirement balances for members across the board – for example, a new workforce entrant today could earn around $407,000 more by the time they retire in 2064.
Tip: The end of the financial year is a good time to take a closer look at your super arrangements. Do you need to roll together accounts or change funds? Could you make salary sacrifices to reduce your tax payments and boost your retirement balance? Let us know if you’re considering these super questions.
SMSF compliance: don’t slip up
With the self-managed superannuation fund (SMSF) annual return lodgment deadline upon us, minds should have already turned to meeting compliance requirements. The 2016–2017 financial year includes a few twists and turns which trustees should factor in to avoid late lodgment.
The major super changes from 1 July 2017 mean that SMSFs members with a pension balance of more than $1.6 million may need to consider reducing any excess, resetting CGT cost bases and getting actuarial certificates. This is in addition to the usual issues such as calculating taxable income and what expenses are deductible for the SMSF.
With all of these changes to be considered, the ATO has allowed an extension to lodge returns by 2 July.
Recordkeeping reminders
Good SMSF compliance hinges substantially on good recordkeeping. Some SMSFs have resolutions and minutes for every investment transaction while others don’t go into much detail at all. But what level of detail is really necessary? The answer lies in the fund’s trust deed, investment strategy and what is required by the tax and superannuation legislation.
For example, a fund with a single balanced option is unlikely to have to meet each time a contribution is made to decide where the money should go. In contrast, if the fund’s investment strategy is couched in broad terms and a member wishes to select specific investments as permitted by the fund’s trust deed, then documents indicating whether the selection is consistent with the overall investment strategy of the fund are likely to be worthwhile.
The superannuation law requires that some records must be retained for various periods. For example, the fund’s accounting records, annual returns and other statements must be kept for at least five years. Minutes of meetings for purposes such as reviewing the fund’s investment strategy, changes of trustees, member reports and storage of collectables and personal use assets need to be kept for at least
10 years. The fund’s trust deed and other essential documents should be retained if the trustees consider the fund may be subject to challenge.
Keeping records for an SMSF serves many purposes to provide a “corporate memory” for the fund, which may be required for compliance purposes as well as to protect trustees from any unfounded challenges.
Client Alert – June 2018
Tax planning
With the end of the 2018 income tax year rapidly approaching, this issue draws attention to year-end tax planning strategies and compliance matters that you need to consider to ensure good tax health. It focuses on the most important issues for small to medium businesses and individuals to consider.
Tip: This is general information, but we’ll take your particular circumstances into account to help you achieve good tax health. Contact us to find out more.
Deferring derivation of income
If your business recognises income on an accruals basis (when an invoice is raised) and your cash flow allows, you may consider delaying raising some invoices until after 30 June, meaning the assessable income will be derived after the 2018 income tax year.
For business income derived on a cash basis (interest, royalties, rent and dividends), you may consider deferring the receipt of certain payments until after 30 June 2018. For example, setting term deposits to mature after 30 June 2018 rather than before.
Bringing forward tax-deductible expenses
To qualify for deductions in the 2018 income tax year, you may be able to bring forward upcoming expenses so that you incur them before 30 June 2018. Small businesses and individual non-business taxpayers may prepay some expenses (such as insurances and professional subscriptions) up to 12 months ahead. This should only be done subject to available cash flow and where the prepayment makes commercial sense.
Businesses
Lower company tax rates and imputation
Company tax rates are falling in Australia. Companies carrying on a business with turnover of less than $25 million will pay a rate of 27.5% in 2018 – the rate of 30% only applies if turnover is $25 million or more, or the company is not carrying on a business.
By 2027, the tax rate will reach a low of 25% for companies carrying on a business with turnover up to $50 million.
Tip: The dividend franking rate for 2018 may be different from a company’s tax rate, depending on whether turnover in 2017 was more than the current year’s turnover benchmark ($25 million for 2018).
Deductions for small business entities
Small business entities (companies, trusts, partnerships or sole traders with total turnover of less than $10 million) will qualify for a raft of tax concessions in the 2018 income tax year:
- the $20,000 instant asset write-off – an immediate deduction when buying and installing depreciating assets that cost less than $20,000.
- the simplified depreciation rules – accelerated depreciation rates of 15% or 30% for depreciable assets that cost $20,000 or more;
- the small business restructure rollover;
- an immediate deduction for start-up costs;
- an immediate deduction for certain prepaid expenses;
- the simplified trading stock rules – removing the need to do an end-of-year stocktake if stock value has changed by less than $5,000;
- the simplified PAYG rules – the ATO will calculate PAYG instalments;
- cash basis accounting for GST – the ATO will calculate the GST instalment payable and annual apportionment for input tax credits for acquisitions that are partly creditable;
- the FBT car parking exemption (from 1 April 2017); and
- the ability for employees to salary-sacrifice two identical portable electronic devices (from 1 April 2016).
These concessions are very powerful for small businesses and can lead to substantial tax savings.
Small business CGT concessions
If you’re selling a business that has an aggregated turnover of less than $2 million (a “CGT small business entity”) or the value of its net CGT assets is $6 million or less (it satisfies the $6 million “net asset value” test), you may be able to access the small business CGT concessions.
These concessions include:
- a 15-year exemption – no CGT is payable;
- a 50% active asset reduction – a 50% CGT discount in addition to the 50% general discount;
- the retirement exemption – up to $500,000 lifetime tax-free limit; and
- the active asset rollover – minimum two years’ deferral.
Individuals
No more Budget repair levy
The Budget repair levy (2% of the part of your taxable income over $180,000) no longer applies in 2018. This means that the top marginal rate for 2018 (including the 2% Medicare levy) is 47%, as opposed to 49% in 2017. The FBT rate is also 47% for the 2018 FBT year.
Deduct work-related expenses
People overclaiming deductions for work-related expenses like vehicles, travel, internet and mobile phones and self-education are on the ATO’s hitlist this year. There are three main rules when it comes to work-related claims:
- You can only claim a deduction for money you have actually spent (and that your employer hasn’t reimbursed).
- The expense must be directly related to earning your work income.
- You must have a record to prove the expense.
Deductions are not allowed for private expenses (e.g. travel from home to work that’s not required to transport bulky equipment) or reimbursed expenses (e.g. for the cost of meals, accommodation and travel). And although you don’t need to include records like receipts with your tax return, the ATO can deny your claim – and penalties may apply – if you can’t produce the evidence when asked.
Tip: The ATO now uses real-time data to compare deductions across similar occupations and income brackets, so it can quickly identify higher-than-expected or unusual claims.
Superannuation contributions and changes
There have been a number of fundamental changes to the superannuation landscape for the 2018 income tax year, including changes to the caps for concessional contributions (now $25,000 for all taxpayers) and non-concessional contributions ($100,000, or $300,000 under the three-year bring forward rule) and the introduction of the general transfer balance cap and total super balance threshold (each currently $1.6 million).
Also, from 2018, both employees and self-employed individuals can claim a tax deduction annually (maximum $25,000) for personal superannuation contributions, provided the superannuation fund has physically received the contribution by 30 June 2018 and the individual provides their superannuation fund with a “notice of intention to claim” document.
Property owners
There have been recent changes to:
- the tax treatment associated with residential rental properties (e.g. travel deduction and depreciation changes);
- CGT and GST withholding tax obligations for purchasers of property;
- superannuation measures impacting home ownership (e.g. the first home super saver scheme and the superannuation downsizer incentive); and
- stamp duty and land tax, which varies from state to state.
The government has also proposed to abolish the main residence CGT exemption for taxpayers who are no longer Australian tax residents at the time they sign a contract to sell their home, regardless of how long the home has actually been used as a main residence.
Tax compliance and developments
Single Touch Payroll
From 1 July 2018, employers with 20 or more employees will have to run their payroll and pay their employees through accounting and payroll software that is Single Touch Payroll (STP) ready. This is a major reporting change, as employers will report payments such as salaries and wages and allowances, PAYG withholding and super information to the ATO directly from their payroll solution at the same time employees are paid.
GST on low value imported goods
From 1 July 2018, overseas vendors with GST turnover of AUD$75,000 or more in Australian sales will have to account for GST on sales of imported goods costing AUD$1,000 or less to consumers in Australia.
Payments to contractors in building and construction
Businesses in the building and construction industry must report to the ATO about their total annual payments to contractors by 28 August 2018. The government has proposed to extend this reporting regime to cleaners and couriers (from 1 July 2018) and to security providers, road transport and computer design services (from 1 July 2019).
Federal Budget – May 2018
PERSONAL TAXATION
Personal tax rates: staged seven-year reform plan starting from 2018–2019
In the 2018–2019 Budget, the Government announced staged tax relief for low and middle-income earners. The Government is proposing a major seven-year, three-step plan to reform personal income tax.
Step 1 will see a new, non-refundable low and middle-income tax offset from 2018–2019 to 2021–2022, designed to provide tax relief of up to $530 for each of those years. The offset will be delivered on assessment after an individual submits their tax return and will be in addition to the existing low income tax offset (LITO).
The low and middle-income tax offset will provide a benefit of up to $200 for taxpayers with taxable income of $37,000 or less. Between $37,000 and $48,000 of taxable income, the value of the offset will increase at a rate of three cents per dollar to the maximum benefit of $530. Taxpayers with taxable incomes from $48,000 to $90,000 will be eligible for the maximum benefit of $530. From $90,001 to $125,333 of taxable income, the offset will phase out at a rate of 1.5 cents per dollar.
Step 2 will increase the top threshold of the 32.5% tax bracket from $87,000 to $90,000 from 1 July 2018. In 2022–2023, the top threshold of the 19% bracket will increase from $37,000 to $41,000 and the LITO will increase from $445 to $645. The increased LITO will be withdrawn at a rate of 6.5 cents per dollar between incomes of $37,000 and $41,000, and at a rate of 1.5 cents per dollar between incomes of $41,000 and $66,667. The top threshold of the 32.5% bracket will increase from $90,000 to $120,000 from 1 July 2022.
Step 3: from 1 July 2024, the top threshold of the 32.5% bracket will increase from $120,000 to $200,000, removing the 37% tax bracket completely. Taxpayers will pay the top marginal tax rate of 45% from taxable incomes exceeding $200,000 and the 32.5% tax bracket will apply to taxable incomes of $41,001 to $200,000.
The Government says this means that around 94% of all taxpayers are projected to face a marginal tax rate of 32.5% or less in 2024–2025.
Medicare levy, 2017–2018 tax rates unchanged
The Government had proposed to increase the Medicare levy from 2% to 2.5% from 1 July 2019, but has decided not to proceed with this. Presumably the Bills to do this, which are currently before Parliament, will be removed. In an address on 26 April 2018 to the Australian Business Economists in Sydney, the Treasurer said that, due to the improving economy and fiscal position, the Government is “now in a position to give our guarantee to Australians living with a disability and their families and carers that all planned expenditure on the National Disability Insurance Scheme (NDIS) will be able to be met in this year’s Budget and beyond without any longer having to increase the Medicare levy”.
At the same time, it has been reported that Shadow Treasurer Chris Bowen has announced that Labor will not proceed with its proposal to increase the Medicare levy by 0.5% (to 2.5%) on those earning above $87,000.
The tax rates and thresholds for the 2017–2018 year remain unchanged.
BUSINESS TAXATION
$20,000 instant asset write-off for SBEs extended by 12 months
The Government will extend the current instant asset write-off ($20,000 threshold) for small business entities (SBEs) by 12 months to 30 June 2019. This applies to businesses with aggregated annual turnover less than $10 million.
The threshold amount was due to return to $1,000 on 1 July 2018. As a result of this announcement, SBEs will be able to immediately deduct purchases of eligible depreciating assets costing less than $20,000 that are acquired between 1 July 2017 and 30 June 2019 and first used or installed ready for use by 30 June 2019 for a taxable purpose. Only a few assets are not eligible for the instant asset write-off or other simplified depreciation rules (e.g. horticultural plants and in-house software).
Assets valued at $20,000 or more (which cannot be immediately deducted) can continue to be placed into the general small business pool (the pool) and depreciated at 15% in the first income year and 30% each income year thereafter. The pool can also be immediately deducted if the balance is less than $20,000 over this period (including existing pools).
The current “lock out” laws for the simplified depreciation rules (which prevent small businesses from re-entering the simplified depreciation regime for five years if they opt out) will continue to be suspended until 30 June 2019.
The instant asset write-off threshold and the threshold for immediate deductibility of the balance of the pool will revert to $1,000 on 1 July 2019.
While the extension of the write-off will be welcomed, SBEs of course need to have the cash-flow to enable them to spend the $20,000 in the first place.
Anti-avoidance rules: family trust circular distributions
The Government will extend specific anti-avoidance rules that apply to other closely held trusts that engage in circular trust distributions to family trusts.
Currently, where family trusts act as beneficiaries of each other in a round-robin arrangement, a distribution can ultimately be returned to the original trustee in a way that avoids any tax being paid on that amount. The measure will allow ATO to pursue family trusts that engage in these arrangements and impose tax on such distributions at a rate equal to the top personal rate plus the Medicare levy.
This measure applies from 1 July 2019.
Deductions disallowed for holding vacant land
The Government will disallow deductions for expenses associated with holding vacant land. Where the land is not genuinely held for the purpose of earning assessable income, expenses such as interest costs will be denied. It is hoped this measure will reduce the tax incentives for land banking which limit the use of land for housing or other development.
The measure will apply to both land held for residential and commercial purposes. However, the “carrying on a business” test would generally exclude land held for a commercial development. It will not apply to expenses associated with holding land that are incurred after:
- a property has been constructed on the land, it has received approval to be occupied and available for rent; or
- the land is being used by the owner to carry on a business, including a business of primary production.
Disallowed deductions will not be able to be carried forward for use in later income years. Expenses for which deductions will be denied could be included in the cost base if it would ordinarily be a cost base element (i.e. borrowing costs and council rates) for CGT purposes. However, if the denied deductions are for expenses would not ordinarily be a cost base element, they cannot be included in the cost base.
This measure applies from 1 July 2019.
Partnerships: enhancing integrity of concessions
Partners that alienate their income by creating, assigning or otherwise dealing in rights to the future income of a partnership will no longer be able to access the small business capital gains tax (CGT) concessions in relation to these rights.
The Government said this measure will prevent taxpayers, including large partnerships, inappropriately accessing the CGT small business concessions in relation to their assignment to an entity of a right to the future income of a partnership, without giving that entity any role in the partnership.
There are no changes to the small business CGT concessions themselves. The concessions will continue to be available to eligible small businesses with an aggregated annual turnover of less than $2 million or net assets less than $6 million.
These measures will apply from 7:30PM (AEST) on 8 May 2018.
TAX COMPLIANCE AND INTEGRITY
No tax deduction for non-compliant PAYG and contractor payments
Measures will be enacted to ensure that taxpayers will not be able to claim deductions for payments to their employees such as wages where they have not withheld any amount of PAYG from these payments, despite the PAYG withholding requirements applying.
Similarly, the Government intends to remove deductions for payments made by businesses to contractors where the contractor does not provide an ABN and the business does not withhold any amount of PAYG (again despite the withholding requirements applying).
These measures were recommended by the Black Economy Taskforce.
The revenue expectations linked with this expenditure is quite modest – “a small unquantifiable gain to revenue over the forward estimates period”.
The measures will commence on 1 July 2019.
Cash payments limit: payments made
to businesses
The Government will introduce a limit of $10,000 for cash payments made to businesses for goods and services.
This measure will require transactions over a threshold to be made through an electronic payment system or by cheque. Logically it would seem that this threshold amount should be $10,000, but this is not spelt out in the Budget papers or the media release.
The rules will not apply to transactions with:
- financial institutions; or
- consumer-to-consumer non-business transactions.
This measure was recommended by the Black Economy Taskforce. It is designed to support other measures designed to counter the black economy. There is no revenue impact associated with it.
The limit will apply from 1 July 2019. The Government will consult further as part of the implementation process.
Reportable payments system extended: security providers, road freight transport and computer design
The Government will extend the taxable payments reporting system (TPRS) to the following industries:
- security providers and investigation services;
- road freight transport; and
- computer system design and related services.
This will extend the TPRS requirements already applying to the building and construction industry. The TPRS requirements will also be extended, from 1 July 2018, to the cleaning and courier industries under measures contained in the Treasury Laws Amendment (Black Economy Taskforce Measures No 1) Bill 2018.
The reporting requirements will apply from 1 July 2019, with the first annual report required in August 2020.
SUPERANNUATION
SMSF member limit to increase from four to six
The Budget confirmed that the maximum number of allowable members in new and existing self managed superannuation funds (SMSFs) and small APRA funds will be expanded from four to six members from 1 July 2019. This measure was originally flagged on 27 April 2018 by the Minister for Revenue and Financial Services, Kelly O’Dwyer.
The proposed increase to the maximum number of SMSF members seeks to provide greater flexibility for large families to jointly manage retirement savings. Given the growth in the sector to date, Ms O’Dwyer said the measure will ensure SMSFs remain compelling retirement savings vehicle. The Government is expected to ask the ATO to work with industry on the design and implementation of this measure. It is not expected to have a revenue impact.
Extra SMSF members to provide flexibility
Currently, s 17A(1)(a) of the Superannuation Industry (Supervision) Act 1993 (SIS Act) requires an SMSF to have fewer than five members. In addition, each member must be a trustee of the fund (or a director of the corporate trustee). This seeks to ensure that all members are fully involved and equally responsible for fund decisions and investments.
The Government’s proposal to allow up to six SMSF members may assist those with larger families to implement intergenerational solutions for managing long-term, capital intensive investments, such as commercial property and business real property. For example, allowing an extra two members provides an opportunity to improve a fund’s cash flow by using the contributions of the younger members to make pension payments to the members in retirement phase, without needing to sell a long-term investment.
As each member must be a trustee of the fund, a decision to add extra members should not be taken lightly as it can add complexity to the fund’s management and investment strategy. A change to the membership of an SMSF will alter the trustee arrangements which can impact who controls the fund in the event of a dispute. This is especially relevant in the event of the death of a member, as the surviving trustees have considerable discretion as to the payment of the deceased’s super benefits (subject to any binding death benefit nomination).
Labor’s dividend imputation policy
Allowing up to six SMSF members may assist some SMSFs to implement strategies to guard against Labor’s proposal to end cash refunds of excess franking credits from 1 July 2019. SMSFs in tax-exempt pension phase are expected to feel the brunt of Labor’s proposal, although an exemption was subsequently announced for SMSFs with at least one Government pensioner or allowance recipient before 28 March 2018.
To avoid wasting non-refundable franking credits, Labor’s proposal would create an incentive for SMSFs in pension phase to add additional accumulation phase members (e.g. adult children) who could effectively make some use of the excess franking credits within the fund. That is, the excess franking credits would be used to absorb some of the 15% contributions tax in relation to the accumulation members. For example, the proposal to increase the maximum number of SMSF members from four to six would enable a typical two-member fund in pension phase to admit up to four adult children as members. If those adult children are making concessional contributions up to the maximum of $25,000 per year, the fund could use the excess franking credits to offset up to $15,000 (four x $25,000 x 15%) in contributions tax each year for the adult children.
This strategy would essentially replicate, to the extent possible, the position of large APRA funds under Labor’s policy. APRA funds typically have more contributing members and diverse income sources (beyond franked dividends) that can usually fully absorb the franking credits.
As already noted, a decision to add additional members to an SMSF may add complexity to the management and control of the fund. This would require professional advice for the specific circumstances of the fund and its members.
Superannuation work test exemption for contributions by recent retirees
The Government will introduce an exemption from the work test for voluntary superannuation contributions by individuals aged 65–74 with superannuation balances below $300,000 in the first year that they do not meet the work test requirements.
Currently, the work test in reg 7.04 of the Superannuation Industry (Supervision) Regulations 1994 (SIS Regulations) restricts the ability to make voluntary superannuation contributions for those aged 65–74 to individuals who self-report as working a minimum of 40 hours in any 30-day period in the financial year. The measure will give recent retirees additional flexibilities to get their financial affairs in order in transition to retirement. It will apply from 1 July 2019.
SMSF audit cycle of three years for funds with good compliance history
The annual audit requirement for SMSFs will be extend to a three-yearly cycle for funds with a history of good record-keeping and compliance.
The measure will apply to SMSF trustees that have a history of three consecutive years of clear audit reports and that have lodged the fund’s annual returns in a timely manner.
This measure will start on 1 July 2019. The Government said it will undertake consultation to ensure a smooth implementation.
Super fees to be capped at 3% for small accounts, exit fees banned
Passive fees charged by superannuation funds will be capped at 3% for small accounts with balances below $6,000, while exit fees will be banned for all superannuation accounts from 1 July 2019. These measures form part of the Government’s Protecting Your Super Package.
The Minister for Revenue and Financial Services, Kelly O’Dwyer, said there were around 9.5 million super account with a balance less than $6,000 in 2015–2016. To avoid these small accounts from being eroded, the Government will cap the administration and investment fees at 3% annually, Ms O’Dwyer said.
The Government will also ban exit fees on all superannuation accounts. Exit fees of around $37 million were charged to members in 2015–2016 to simply close an account with a super fund. The proposed ban on exit fees will also benefit members looking to rollover their super accounts to a different fund, or who hold multiple accounts and see exit fees as a barrier to consolidating accounts.
With nearly two million low and inactive accounts belonging to women, the Minister said these measures will help to protect the hard-earned super savings of women from undue erosion. These changes will take effect from 1 July 2019.
Superannuation insurance opt-in rule for younger and low-balance members
The Government will change the insurance arrangements for certain cohorts of superannuation members from 1 July 2019. Under the proposed changes, insurance within superannuation will move from a default framework to be offered on an opt-in basis for:
- members with low balances of less than $6,000;
- members under the age of 25 years; and
- members with inactive accounts that have not received a contribution in 13 months.
These changes seek to protect the retirement savings of young people and those with low balances by ensuring their superannuation is not unnecessarily eroded by premiums on insurance policies they do not need or are not aware of. The Minister for Revenue and Financial Services, Kelly O’Dwyer, said around 5 million individuals will have the opportunity to save an estimated $3 billion in insurance premiums by choosing to opt-in to this cover, rather than paying for it by default.
The changes also seek to reduce the incidence of duplicated cover so that individuals are not paying for multiple insurance policies, which they may not be able to claim on in any event. Importantly, these changes will not prevent anyone who wants insurance from being able to obtain it. That is, low balance, young, and inactive members will still be able to opt in to insurance cover within super.
In addition, the Government said it will consult publicly on ways in which the current policy settings could be improved to better balance the priorities of retirement savings and insurance cover within super.
The changes will take effect on 1 July 2019. Affected superannuants will have a period of 14 months to decide whether they will opt-in to their existing cover or allow it to switch off.
Client Alert – May 2018
ATO closely examines work-related car expenses
The ATO is concerned about taxpayers making mistakes or deliberately lodging false claims for work-related car expenses, and has announced it will be closely examining claims for these expenses in 2018 tax returns. Last year, around 3.75 million people made a work-related car expense claim, totalling about $8.8 billion.
The best way for to avoid mistakes is to make sure you follow “the three golden rules”, only making a car claim if:
- you paid for the expense yourself and you weren’t reimbursed;
- it’s directly related to earning your income – in other words, your employer required you to make the trips as part of your job; and
- you have a record to support your claim.
TIP: We can help you avoid mistakes and understand what you’re entitled to claim this tax time. Contact us about your tax return today.
Data matching finds taxpayers with unnamed Swiss bank accounts
More than 100 Australians have been identified as “high risk” and will be subject to ATO investigation because they have links to Swiss banking relationship managers who are alleged to have actively promoted and facilitated tax evasion schemes.
The ATO constantly receives intelligence from a range of local and international sources which it cross-matches against existing intelligence holdings through its “smarter data” technology.
Australians who may have undeclared offshore income are encouraged to contact the ATO with that information – if penalties or interest apply, the amounts will generally be reduced (by up to 80%) if you make this kind of voluntary disclosure.
TIP: It’s important for Australia tax residents to declare all of their worldwide income to the ATO. Australia has many international tax agreements that work to avoid double taxation for people who are resident in Australia but make income from offshore sources.
CGT main residence exemption to disappear for non-residents
A person’s Australian tax residency status may be about to assume a whole new meaning. Currently, both residents and non-residents qualify for a full or partial exemption from capital gains tax (CGT) when they sell a property that is their home (main residence). But if a Bill that is currently before Parliament is passed, that will change, and any individual who is a non-resident for tax purposes at the time they sign a contract to sell their home – for example, if they have moved overseas before signing the sale contract – will no longer qualify for the full or partial main residence exemption, regardless of how long the home was actually their main residence when they were an Australian tax resident.
TIP: If you’re considering selling your home and moving or travelling overseas, talk to us to find out how this could affect your Australian tax residency and CGT costs.
Residential rental property travel expense deduction changes
Recent changes to Australian tax law mean that individuals, self managed superannuation funds (SMSFs) and “private” trusts and partnerships can longer claim tax deductions for non-business travel costs related to their residential rental properties. Such costs also cannot form part of the cost base or reduced cost base of a CGT asset.
The ATO has issued guidance to make it clear that tax deductions are only permitted for taxpayers who incur this kind of travel expense as a necessary part of
carrying on a business such as property investing, or providing retirement living, aged care, student accommodation or property management services.
TIP: The ATO will consider a range of factors, such as number of properties leased, time and expertise needed for their maintenance, and taxpayer record-keeping, when deciding if someone carries on a business that requires travel expenditure related to their residential properties.
Government to increase civil penalties for white-collar crime
In response to recent Senate Economics References Committee and Australian Securities and Investments Commission (ASIC) Enforcement Review Taskforce reports, the Federal Government has agreed to increase the civil penalties for corporate and financial misconduct (white-collar crime), for both individuals and bodies corporate. ASIC infringement notices will also be expanded to cover a broader range of financial services and managed investments infringements.
The new maximum civil penalties will be set at:
- for individuals, the greater of 5,000 penalty units (currently $1.05 million) or three times the value of the benefits obtained or losses avoided; and
- for corporations, the greater of 50,000 penalty units (currently $10.5 million) or three times the value of the benefits obtained or losses avoided, or 10% of annual turnover in the 12 months before the misconduct, up to a total of one million penalty units ($210 million).
Businesses, get ready: GST on
low value goods
From 1 July 2018, GST will be imposed on the supply low value goods from outside of Australia to Australian consumers. Businesses need to be ready for this change.
TIP: Businesses must register for Australian GST once their annual turnover reaches $75,000, but registering is optional for businesses with lower turnover. The low value goods changes will apply from 1 July 2018 for all businesses registered for GST, whether their registration was required or they chose to register.
Under the low value goods regime, businesses that sell goods valued at A$1,000 or less to an Australian consumer (who is not registered for GST) will be liable to pay GST on those sales. GST will also apply where the business delivers or facilitates delivery of the goods into Australia.
TIP: If your business will be affected, now is the time to make sure your systems are ready to collect GST on low value sales, that your online terms and conditions are up to date, and that your website meets Australian consumer law requirements for displaying prices.
Business-to-business (B2B) sales, where a business sells low value goods to a recipient business that is registered for GST, are excluded from the regime.
Tip: The New Zealand Government has also recently proposed to levy GST on goods valued under the country’s current threshold of NZ$400.
Financial Complaints Authority takes shape
Minister for Revenue and Financial Services Kelly O’Dwyer has announced the authorisation of the new financial dispute resolution scheme, the Australian Financial Complaints Authority (AFCA), which will start accepting complaints from 1 November 2018. AFCA is intended to be a “one-stop shop”, having the expertise to deal with all financial disputes, including superannuation and small business lending disputes, with higher monetary limits and compensation caps.
All Australian financial services (AFS) licensees, Australian credit licensees, superannuation trustees and other financial firms legally required to join AFCA will need to do so by 21 September 2018.
Banking Royal Commission wraps up evidence on financial advice
The Banking Royal Commission has wrapped up its two weeks of hearings focused on financial advice.
The hearings have included gruelling evidence of misconduct in financial services entities’ provision of financial advice, occurring in the context of fees being charged for no service, platform fees, inappropriate advice, improper conduct and the disciplinary regime.
The Royal Commission has adjourned until 21 May 2018, when it will begin its third round of hearings with a focus on small and medium enterprises (SMEs). The Commission’s final report is due by 1 February 2019.
ATO assessments issued for excess super pension balances
The ATO has started issuing excess transfer balance (ETB) tax assessments to self managed super fund (SMSF) members, or their agents, who had previously received an ETB determination and rectified the excess. These ETB tax assessments are sent to SMSF members (or their professionals), and not to the fund. It’s then up to the member to decide how to cover the ETB liability for exceeding their $1.6 million pension transfer balance cap.
The ATO warns that SMSF members may receive an ETB assessment even if they didn’t receive an ETB determination. If they rectified the excess before they were assessed for a determination, they are still liable for the ETB tax. However, SMSF members who were covered by the transitional rules for excesses not exceeding $100,000 and rectified in full by 31 December 2017, will not receive an ETB tax assessment.
ABN Lookup – Business Names/Trading Names
From November 2018, trading names will be removed from the ABN Lookup.
The ABN Lookup contains a list of all Australian Business Numbers (ABNs) and any associated business names.
A ‘trading name’ refers to an unregistered name that businesses could use before the introduction of the National Business Names Register.
A trading name is not a registered business name.
If you want to trade under a specific name, you’ll need to register it as a business name with the Australian Securities and Investments Commission (ASIC).
You don’t need to register a business name if you trade under your own name (‘John Smith’), but you’ll need to have a business name if it’s anything else (‘John Smith Plumbing’).
To continue using a trading name after November 2018, businesses have to register them.
Should you require a business name to be registered or would like any further information or assistance please contact Nicole Bedoya on 9509 7033 or email nb@guests.com.au
Client Alert – April 2018
ATO embarking on e-Audits
The ATO has recently published information about the “e-Audit” technology it uses as part of its tax compliance activities. These audits involve the ATO performing computer tests on a taxpayer’s own electronic records to verify that the data is accurate and complete and that the taxpayer has complied with relevant tax laws.
If a taxpayer is selected by the ATO for an audit or review, the ATO will take a copy of the relevant records (eg data held in the taxpayer’s accounting or payroll systems) in order to perform the tests. Although the ATO has broad powers to access taxpayers’ records, the ATO takes a cooperative approach and will work with the taxpayer and their advisers.
The ATO may also use an assessment tool to rate a taxpayer’s system risks in relation to correct reporting of tax and super obligations. This can have benefits for the taxpayer because the ATO will provide them with a final report that highlights any particular compliance risks for their business and includes recommendations for addressing these issues.
Court finds pay-as-you-go amounts “withheld” from salary payments
The Federal Court has ruled that pay-as-you-go (PAYG) amounts were “withheld” from a taxpayer’s salary payments so that she was entitled to a tax credit, despite the amounts never being remitted or notified to the ATO by her employers.
This case illustrates the importance of records and documentation in tax matters. The Court examined evidence such as the taxpayer’s offer of employment, payslips, bank statements and payment summaries, which suggested that the salary payments she received were “net pay” amounts (and not “gross”).
The Court noted that where an employer has not remitted PAYG withholding amounts to the ATO, this will raise questions about whether amounts were really withheld. However, adequate documentation can – as in this case – be used to prove that PAYG has in fact been withheld by an employer, even if the employer has subsequently failed to remit this to the ATO.
“Transition to retirement” pensions to become simpler
In welcome news for superannuation members, the government has announced plans to simplify the payment of transition to retirement income streams (TRISs) so that they will always be permitted to automatically revert to a dependant upon the death of the original pensioner. This is designed to address a trap in the current legislation that is causing some administrative difficulties for funds when a TRIS recipient passes away.
TIP: With greater certainty about the payment of TRISs on death, now is a good time for superannuation members to review their estate plans.
ATO releases latest small business benchmarks
The ATO has released its latest small business benchmarks, providing over 100 different industries with average cost of sales and average total expenses.
These benchmarks can not only assist businesses with tax compliance (eg by prompting them to double-check their records if their expenses are outside the benchmark range for their industry), but also provide useful information to help businesses judge their performance against others in the industry.
TIP: You can access the benchmarks online or by using the ATO app. Contact our office if you wish to discuss how your business compares against industry benchmarks.
Capital gains tax withholding: updated information for trustees
The foreign resident capital gains tax (CGT) withholding regime requires purchasers of Australian property to withhold an amount from the purchase price (for remission to the ATO) if the vendor is a foreign resident. This regime is designed to assist the ATO in collecting CGT payable by foreign residents.
If the vendor is an Australian resident, they must provide an ATO-issued clearance certificate to the purchaser on or before the day of settlement to ensure no withholding occurs. The ATO has released some guidance for trusts and superannuation funds about specific information they must provide when applying to the ATO for a clearance certificate. Contact our office for further assistance.
Goods and services tax on low-value imported goods
From 1 July 2018, goods and services tax (GST) will apply to some offshore supplies of goods valued at $1,000 or less that are purchased by consumers and brought into Australia. The new rules are designed to create a more “level playing field” for local retailers.
The ATO has released a ruling covering GST registration issues for suppliers and other technical aspects of the new legislation. Notably, the existing rules about GST on imports valued above $1,000 are unchanged.
Superannuation rates and thresholds for 2018–2019
We summarise some of the key superannuation rates and thresholds for the upcoming financial year:
Contributions
| Concessional contributions cap | $25,000 |
| Non-concessional contributions cap | $100,000* |
| CGT cap amount | $1,480,000 |
| Super guarantee percentage | 9.5% |
| Maximum contribution base (per quarter) | $54,030 |
* 300,000 for a “bring forward” arrangement
Government co-contributions
| Lower income threshold | $37,697 |
| Higher income threshold | $52,697 |
Superannuation payments
| Lump sum low rate cap | $205,000 |
| Untaxed plan cap | $1,480,000 |
| ETP cap amount | $205,000 |
| Genuine redundancy and early retirement payments – tax-free amounts: | |
| · base amount | $10,399 |
| · service amount | $5,200 |
Pension cap
| General transfer balance cap | $1,600,000 |
| Defined benefit income cap | $100,000 |
| “Total superannuation balance” threshold | $1,600,000 |
Super guarantee: ATO compliance approach to non-payment
The ATO has released a fact sheet explaining its compliance approach to employers who fail to meet their superannuation guarantee (SG) obligations.
Broadly, employers are required to make SG contributions of 9.5% of an employee’s ordinary time earnings (provided they have paid the employee at least $450 in a calendar month). Payments are due quarterly. Employers are also liable to make contributions for certain contractors.
The ATO confirms that its compliance approach towards a particular employer will depend on that employer’s compliance history and other circumstances. The ATO will take firm action against any employer who repeatedly fails to pay the correct amount of SG or who does not cooperate with the ATO (eg by failing to provide information or attempting to mislead or obstruct the ATO).
Single Touch Payroll reporting: ATO urges employers to get ready
The ATO is urging employers with 20 or more employees to start preparing now for the Single Touch Payroll (STP) reporting regime, which will be mandatory from 1 July 2018.
This reporting change for employers means they will report payments such as salaries, wages, allowances, PAYG withholding and superannuation contributions information to the ATO directly from their payroll solution at the same time they pay their employees. STP reporting starts on 1 July 2018 for employers with 20 or more employees, and is slated to apply from 1 July 2019 for those with 19 or fewer employees.
TIP: Businesses should do a headcount of employees as at 1 April 2018 to check if they have 20 or more. There are rules about which employees to include in the headcount. Contact our office for assistance.
Client Alert – March 2018
Bill to implement housing affordability CGT changes
As part of the 2017–2018 Budget, the Federal Government announced a range of reforms intended to reduce pressure on housing affordability. Legislation has now been introduced into Parliament that proposes to:
- remove the entitlement to the capital gains tax (CGT) main residence exemption for foreign residents; and
- modify the foreign resident CGT regime to clarify that, for the purpose of determining whether an entity’s underlying value is principally derived from taxable Australian real property (TARP), the principal asset test is applied on an “associate inclusive” basis.
The Bill also proposes to amend the tax law to provide an additional discount on CGT for affordable housing. The discount of up to 10% will apply if a CGT event happens to an ownership interest in residential property used to provide affordable housing.
TIP: The main residence exemption means that CGT doesn’t apply for a capital gain or loss that an individual makes from selling their main residence. A CGT discount applies if the dwelling was their main residence for only part of the time they owned it, or they partly used it to produce assessable income.
Changes to small business CGT concessions
Treasury has released draft legislation to make sure that taxpayers will only be able to access the small business CGT concessions for assets that are used (or held ready for use) in the course of a small business or are an interest in a small business.
The draft also proposes additional conditions to be satisfied from 1 July 2017 when applying the small business CGT concession for capital gains related to a share in a company or an interest in a trust.
TIP: A range of tax concessions are available for small businesses. Talk to us to find out how your business could benefit.
Bill to change residential property GST arrangements
A Bill has been introduced into Parliament that, when passed, will require purchasers of new residential premises and new subdivisions of potential residential land to pay the goods and services tax (GST) on the purchase directly to the ATO as part of the settlement process from 1 July 2018.
TIP: Under the current law, the supplier of the property (e.g. the developer) is responsible for paying the GST to the ATO when lodging a business activity statement (BAS). This can happen up to three months after settlement.
The new measure was announced in the 2017–2018 Federal Budget. It is intended to speed up the GST payment process, and to deal with the problem of some developers dissolving their business and setting up a new entity to avoid paying GST (a form of “phoenix” tax avoidance).
Moving to combat the black economy
The Black Economy Taskforce was established in 2017 “to develop an innovative, forward-looking whole-of-government policy response to combat the black economy in Australia, recognising that these issues cannot be tackled by traditional tax enforcement
measures alone”. In May 2017 the taskforce made a its initial recommendations, which it based on foreign jurisdiction experiences, consultation with stakeholders and anecdotal evidence it had received.
TIP: The black economy includes people who don’t correctly report and meet their tax obligations and people who operate entirely outside the tax and regulatory system.
The Government accepted a number of the taskforce’s recommendations, and has now introduced a Bill into Parliament, proposing to combat the black economy by:
- prohibiting the production, distribution and possession of sales suppression tools, which are typically used to remove or alter transaction information recorded by point-of-sale (POS) systems;
- prohibiting the use of electronic sales suppression tools to incorrectly keep tax records; and
- requiring entities that have an ABN and that provide courier or cleaning services to report to the ATO (from 1 July 2018) information about transactions that involve engaging other entities to undertake those services for them.
Corporate tax avoidance: latest
ATO targets
The ATO has provided an update on its latest focus areas and the compliance projects it is undertaking to reduce corporate tax avoidance. These include:
- investigating possible manipulation of the thin capitalisation rules, including 27 taxpayers’ asset revaluations totalling $78 billion;
- looking into arrangements that move intellectual property assets and rights offshore to multinational entities’ related parties;
- focusing on the treatment of oil and gas industry labour costs associated with high-value asset construction;
- examining the arm’s length conditions operating in pharmaceutical industry arrangements;
- identifying tax professionals and advisers who are promoting unacceptable tax planning; and
- looking at the tax affairs of various major
e-commerce players.
Social security means testing of lifetime retirement income streams
The Department of Social Services (DSS) has released its proposed means testing rules for pooled lifetime retirement income streams.
The pension standards were amended from 1 July 2017 to allow for more tax-exempt lifetime superannuation income stream products that enable pooling risk to manage longevity risk. Lifetime pensions and annuities that meet these new standards qualify for tax concessions tax treatment.
The DSS proposes to consider the following amounts when assessing such pooled lifetime income streams as part of social security means testing:
- income test: 70% of all income paid from the income stream product; and
- assets test: 70% of the purchase price of the product until the person reaches the age of their life expectancy at the time they made the purchase, and 35% from then on.
TIP: Under the new rules, deferred super income stream products would receive the same asset test assessment as products where payments begin immediately.
ATO now issuing excess transfer balance determinations
The ATO has advised that is now sending out excess transfer balance (ETB) determinations to individuals who have exceeded their superannuation transfer balance cap and not taken steps to remove the excess amount.
TIP: The transfer balance cap, currently set at $1.6 million, is a limit on the total amount of super that can be transferred into retirement phase. You can make multiple transfers as long as the total amount transferred remains below the cap.
Self-managed superannuation fund (SMSF) members that had exceeded their transfer balance cap by $100,000 or less on 1 July 2017 had until 31 December 2017 to remove the excess capital from retirement phase. If they didn’t do so, they will now have to remove the excess capital and ETB earnings, and also pay ETB tax.
Windfarm grant was an assessable recoupment
The Full Federal Court has dismissed a taxpayer’s appeal and held that a Commonwealth grant of almost $2.5 million for the establishment of a windfarm was an assessable recoupment (Denmark Community Windfarm Ltd v FCT [2018] FCAFC 11).
In May 2011, the taxpayer was given a renewable energy grant for 50% of the project costs it incurred in constructing two wind turbines. The grant was paid in instalments on the completion of identified project milestones.
The ATO made a private ruling that the grant would be assessable income. The taxpayer argued against the ruling, but the Full Federal Court dismissed the taxpayer’s appeal.
Explanatory Notes
FBT return action checklist
Single Touch Payroll
Client Alert – February 2018
ATO guidelines: profit allocation within professional firms
The ATO has become aware that its guidelines on Everett assignments and the allocation of profits within professional firms are being misinterpreted for some higher-risk arrangements, including the use of related-party financing and self-managed superannuation funds (SMSFs).
The guidelines have been suspended from 14 December 2017 to allow the ATO to consult with stakeholders on replacement guidelines.
Anyone considering new arrangements beginning after the cut-off date should contact the ATO to discuss the arrangement risk profile and the possibility of a private ruling.
Arrangements beginning before the cut-off date that comply with the guidelines and do not exhibit high risk factors shouldn’t require action, but arrangements with high risk factors may be subject to ATO review.
TIP: The ATO encourages anyone who is uncertain about how the law applies to their existing circumstances “to engage with us as soon as possible”.
Housing affordability measures
now law
Legislation has been passed to implement the 2017–2018 Federal Budget housing affordability measures. The following will start on 1 July 2018:
- the First Home Super Saver (FHSS) Scheme, which allows individuals to use specific amounts from their super to buy or construct a first home; and
- the option for individuals aged 65+ to make “downsizing” contributions of up to $300,000 to their super from selling a home they have owned for at least 10 years.
TIP: An exemption from meeting the FHSS Scheme “first home” requirement will be available for people suffering financial hardship. “Financial hardship” criteria are likely to include circumstances where someone has limited savings, is currently renting and had a past interest in a home that was in a cheaper real estate market or when the person was in a relationship that has since broken down.
Fringe benefits tax: employees’ private use of vehicles
The ATO has issued guidance for employers on determining an employee’s private use of a vehicle.
Draft Practical Compliance Guideline PCG 2017/D14 should provide more certainty and transparency about the circumstances where the ATO won’t apply compliance resources to investigating whether private vehicle use meets the car-related FBT exemptions.
Eligible employers who rely on this guideline won’t need to keep records to prove that an employee’s private use of a vehicle is minor, infrequent and irregular.
TIP: The guideline includes specific eligibility conditions for employers and their employees’ vehicle use. Talk to us about whether the new guidance applies to your FBT circumstances.
Tax consequences of trust vesting
The ATO has issued a long-awaited ruling on trust vesting, including changing a trust’s vesting date and the CGT and income tax consequences of vesting.
TIP: A trust’s “vesting date” is the day when the beneficiaries’ interests in the trust property become fixed. The trust deed will specify the vesting date and the consequences of that date being reached. Vesting does not, of itself, ordinarily cause the trust to come to an end or cause a new trust to arise. In particular, the underlying trust relationship continues after vesting while the trustee still holds property for the takers.
The key points in the draft ruling are that:
- before vesting, it may be possible to extend the vesting date (by applying to a court or by the trustee exercising a power to nominate a new vesting date);
- it is too late to change the vesting date once it has passed (and the ATO says it is unlikely that a court would agree to do so); and
- continuing to administer a trust in a way that is inconsistent with the vesting terms can have significant CGT and income tax consequences.
Disclosing business tax debt information to credit agencies
The Federal Government has released draft legislation and a draft legislative instrument that, when passed, will authorise the ATO to disclose a business’s tax debt to registered credit reporting bureaus where the business has not effectively engaged with the ATO to manage the debt.
The draft legislation intends to place tax debts on a similar footing as other debts, to encourage timely payment or engagement with the ATO for businesses that want to avoid having their debt information affect their creditworthiness. Disclosure to credit reporting bureaus will only be permitted if the ATO has given the taxpayer at least 21 days’ notice beforehand.
Taxing employee share scheme dividend equivalent payments
The ATO has made a new determination that dividend equivalent payments made under an employee share scheme (ESS) are assessable to an employee as income when they receive the payment for or in connection with services they provide as an employee.
A “dividend equivalent payment” is a cash payment to an employee participant and beneficiary an ESS funded from dividends on which the trustee has been assessed in previous income years because no beneficiary of the trust was entitled to the income at the time.
A trustee that makes a dividend equivalent payment under an ESS must withhold an amount from the payment, even though the trustee is not the employee’s employer.
TIP: The ATO offers a safe harbour from such payments being treated as income under specific circumstances. Get in touch with us to talk about whether your situation makes you eligible.
The new determination applies to dividend equivalent payments paid under the terms and conditions attached to ESS interests granted on or after 1 January 2018.
Superannuation integrity changes
The Government has released a consultation paper and exposure draft legislation to give effect to the following superannuation taxation integrity measures it announced in the 2017–2018 Federal Budget:
- the non-arm’s length income (NALI) rules in s 295-550 of the Income Tax Assessment Act 1997 for related-party superannuation fund transactions will be expanded from 1 July 2018 to also include expenses not incurred that would normally be expected to apply in a commercial arm’s length transaction (e.g. reduced interest expenses, brokerage, accountancy fees or legal costs); and
- a member’s share of the outstanding balance of a limited recourse borrowing arrangement (LRBA) will be included in the member’s “total superannuation balance” for new LRBAs entered into on or after 1 July 2018.
The measures are designed to ensure that related-party transactions with super funds and LRBAs can’t be used to circumvent the reduced contribution caps that apply from 1 July 2017. The changes should generally not affect LRBAs entered into with unrelated third parties for commercial rates of interest (and other expenses).
Guidance for SMSFs on transfer balance reporting
The ATO has released further guidance on when SMSFs need to report events affecting their members’ transfer balance accounts (by making a transfer balance account report, or TBAR) for the purposes of the $1.6 million pension cap.
From 1 July 2018, SMSFs that have any members with a total superannuation balance of $1 million or more must report events impacting that member’s transfer balance account within 28 days after the end of the quarter in which the event occurs.
SMSFs where all members have total super balances of less than $1 million can choose to report events which impact their members’ transfer balances at the same time that the fund lodges its annual return.
The guidance also covers reporting requirements for retirement phase income streams and commutations (including commutation authorities).
Single Touch Payroll – What you need to know
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News
Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























