
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
Single Touch Payroll – 1 April 2018 Action
Single touch payroll will be a compulsory reporting requirement for employers.
It means employers will report payments such as salaries and wages, pay as you go withholding (PAYGW) and super information from their payroll solutions at the same time they pay their employees, directly to the Australian Taxation Office (ATO).
For employers with 20 or more employees, Single Touch Payroll reporting starts from 1 July 2018.
While the system starts 1 July 2018, the obligation is triggered on 1 April 2018.
The 20 or more Headcount is done on April Fools Day!
The following employees need to be included within the Headcount:
- Full-time employees
- Part-time employees
- Casual employees who are on your payroll on 1 April 2018 and worked any time during March
- Employees based overseas
- Any employee absent or on leave (paid or unpaid)
- Seasonal employees engaged regularly.
When performing the headcount, the following are not included:
- Any employees who ceased work before 1 April
- Casual employees who did not work in March
- Independent contractors
- Staff provided by a third-part labour hire organisation
- Company directors
- Office holders
- Religious practitioners
AcctWeb
Property investors on notice after ATO spots false claims
As usual some ridiculous claims ruin it for genuine investors.
(One case reported by the ATO, one man owned a property on Victoria's Mornington Peninsula and claimed $760,000 in deductions for a property used by either himself or family and friends for 87 per cent of the year.)
Clients with holiday homes will be subject to further ATO surveillance this tax time, after the ATO found a large number of “mistakes, errors and false claims” made by owners who use their property for personal holidays.
ATO assistant commissioner Kath Anderson has called on tax agents to double-check claims made by their property investor clients after finding a large number of incorrect deduction claims being made.
“As Australians enjoy the Easter break, they should be aware that the ATO is focusing on taxpayers who claim deductions for holiday homes that are not actually available for rent or only available to friends and family,” said Ms Anderson.
“While private use by family and friends of a holiday home is entirely legitimate, it does reduce your ability to earn income from the property. This in turn impacts the deductions you can claim.
“You can only claim deductions for your holiday home if your property is genuinely available for rent. You cannot claim for times when you were using it for your own personal holidays or letting friends and family stay rent-free,” she added.
“Holiday home owners also need to remember that if their property is rented to friends and family at mates rates, they can only claim deductions for expenses up to the amount of the income received.”
The ATO’s increased focus came after it found similar claims being made last year, including red flags when clients attempt to make claims for property that has not been genuinely rented out.
Ms Anderson said records were key to substantiating claims, including records of income received from the rental property, evidence of the property being rented out, and records of people who have stayed at the holiday home.
“We see things like unreasonable conditions placed on prospective renters, rental rates set above market rates, or failing to advertise a holiday home in a way that targets people who would be interested in it,” Ms Anderson said.
“Incorrect rental property claims will not go unnoticed. Whether it is a genuine mistake or a deliberate attempt to over-claim, new technology, data matching and other systems allow the ATO to identify unusual claims.
“Where something raises a red flag, it will be investigated. Property owners whose claims are disproportionate to the income received can expect scrutiny from the ATO.”
By: Jotham Lian
29 MARCH 2018
www.accountantsdaily.com.au
Client Alert – March 2018
Bill to implement housing affordability CGT changes
As part of the 2017–2018 Budget, the Federal Government announced a range of reforms intended to reduce pressure on housing affordability. Legislation has now been introduced into Parliament that proposes to:
- remove the entitlement to the capital gains tax (CGT) main residence exemption for foreign residents; and
- modify the foreign resident CGT regime to clarify that, for the purpose of determining whether an entity’s underlying value is principally derived from taxable Australian real property (TARP), the principal asset test is applied on an “associate inclusive” basis.
The Bill also proposes to amend the tax law to provide an additional discount on CGT for affordable housing. The discount of up to 10% will apply if a CGT event happens to an ownership interest in residential property used to provide affordable housing.
TIP: The main residence exemption means that CGT doesn’t apply for a capital gain or loss that an individual makes from selling their main residence. A CGT discount applies if the dwelling was their main residence for only part of the time they owned it, or they partly used it to produce assessable income.
Changes to small business CGT concessions
Treasury has released draft legislation to make sure that taxpayers will only be able to access the small business CGT concessions for assets that are used (or held ready for use) in the course of a small business or are an interest in a small business.
The draft also proposes additional conditions to be satisfied from 1 July 2017 when applying the small business CGT concession for capital gains related to a share in a company or an interest in a trust.
TIP: A range of tax concessions are available for small businesses. Talk to us to find out how your business could benefit.
Bill to change residential property GST arrangements
A Bill has been introduced into Parliament that, when passed, will require purchasers of new residential premises and new subdivisions of potential residential land to pay the goods and services tax (GST) on the purchase directly to the ATO as part of the settlement process from 1 July 2018.
TIP: Under the current law, the supplier of the property (e.g. the developer) is responsible for paying the GST to the ATO when lodging a business activity statement (BAS). This can happen up to three months after settlement.
The new measure was announced in the 2017–2018 Federal Budget. It is intended to speed up the GST payment process, and to deal with the problem of some developers dissolving their business and setting up a new entity to avoid paying GST (a form of “phoenix” tax avoidance).
Moving to combat the black economy
The Black Economy Taskforce was established in 2017 “to develop an innovative, forward-looking whole-of-government policy response to combat the black economy in Australia, recognising that these issues cannot be tackled by traditional tax enforcement
measures alone”. In May 2017 the taskforce made a its initial recommendations, which it based on foreign jurisdiction experiences, consultation with stakeholders and anecdotal evidence it had received.
TIP: The black economy includes people who don’t correctly report and meet their tax obligations and people who operate entirely outside the tax and regulatory system.
The Government accepted a number of the taskforce’s recommendations, and has now introduced a Bill into Parliament, proposing to combat the black economy by:
- prohibiting the production, distribution and possession of sales suppression tools, which are typically used to remove or alter transaction information recorded by point-of-sale (POS) systems;
- prohibiting the use of electronic sales suppression tools to incorrectly keep tax records; and
- requiring entities that have an ABN and that provide courier or cleaning services to report to the ATO (from 1 July 2018) information about transactions that involve engaging other entities to undertake those services for them.
Corporate tax avoidance: latest
ATO targets
The ATO has provided an update on its latest focus areas and the compliance projects it is undertaking to reduce corporate tax avoidance. These include:
- investigating possible manipulation of the thin capitalisation rules, including 27 taxpayers’ asset revaluations totalling $78 billion;
- looking into arrangements that move intellectual property assets and rights offshore to multinational entities’ related parties;
- focusing on the treatment of oil and gas industry labour costs associated with high-value asset construction;
- examining the arm’s length conditions operating in pharmaceutical industry arrangements;
- identifying tax professionals and advisers who are promoting unacceptable tax planning; and
- looking at the tax affairs of various major
e-commerce players.
Social security means testing of lifetime retirement income streams
The Department of Social Services (DSS) has released its proposed means testing rules for pooled lifetime retirement income streams.
The pension standards were amended from 1 July 2017 to allow for more tax-exempt lifetime superannuation income stream products that enable pooling risk to manage longevity risk. Lifetime pensions and annuities that meet these new standards qualify for tax concessions tax treatment.
The DSS proposes to consider the following amounts when assessing such pooled lifetime income streams as part of social security means testing:
- income test: 70% of all income paid from the income stream product; and
- assets test: 70% of the purchase price of the product until the person reaches the age of their life expectancy at the time they made the purchase, and 35% from then on.
TIP: Under the new rules, deferred super income stream products would receive the same asset test assessment as products where payments begin immediately.
ATO now issuing excess transfer balance determinations
The ATO has advised that is now sending out excess transfer balance (ETB) determinations to individuals who have exceeded their superannuation transfer balance cap and not taken steps to remove the excess amount.
TIP: The transfer balance cap, currently set at $1.6 million, is a limit on the total amount of super that can be transferred into retirement phase. You can make multiple transfers as long as the total amount transferred remains below the cap.
Self-managed superannuation fund (SMSF) members that had exceeded their transfer balance cap by $100,000 or less on 1 July 2017 had until 31 December 2017 to remove the excess capital from retirement phase. If they didn’t do so, they will now have to remove the excess capital and ETB earnings, and also pay ETB tax.
Windfarm grant was an assessable recoupment
The Full Federal Court has dismissed a taxpayer’s appeal and held that a Commonwealth grant of almost $2.5 million for the establishment of a windfarm was an assessable recoupment (Denmark Community Windfarm Ltd v FCT [2018] FCAFC 11).
In May 2011, the taxpayer was given a renewable energy grant for 50% of the project costs it incurred in constructing two wind turbines. The grant was paid in instalments on the completion of identified project milestones.
The ATO made a private ruling that the grant would be assessable income. The taxpayer argued against the ruling, but the Full Federal Court dismissed the taxpayer’s appeal.
Explanatory Notes
FBT return action checklist
Single Touch Payroll
Client Alert – February 2018
 ATO guidelines: profit allocation within professional firms
The ATO has become aware that its guidelines on Everett assignments and the allocation of profits within professional firms are being misinterpreted for some higher-risk arrangements, including the use of related-party financing and self-managed superannuation funds (SMSFs).
The guidelines have been suspended from 14 December 2017 to allow the ATO to consult with stakeholders on replacement guidelines.
Anyone considering new arrangements beginning after the cut-off date should contact the ATO to discuss the arrangement risk profile and the possibility of a private ruling.
Arrangements beginning before the cut-off date that comply with the guidelines and do not exhibit high risk factors shouldn’t require action, but arrangements with high risk factors may be subject to ATO review.
TIP: The ATO encourages anyone who is uncertain about how the law applies to their existing circumstances “to engage with us as soon as possible”.
Housing affordability measures
now law
Legislation has been passed to implement the 2017–2018 Federal Budget housing affordability measures. The following will start on 1 July 2018:
- the First Home Super Saver (FHSS) Scheme, which allows individuals to use specific amounts from their super to buy or construct a first home; and
- the option for individuals aged 65+ to make “downsizing” contributions of up to $300,000 to their super from selling a home they have owned for at least 10 years.
TIP: An exemption from meeting the FHSS Scheme “first home” requirement will be available for people suffering financial hardship. “Financial hardship” criteria are likely to include circumstances where someone has limited savings, is currently renting and had a past interest in a home that was in a cheaper real estate market or when the person was in a relationship that has since broken down.
Fringe benefits tax: employees’ private use of vehicles
The ATO has issued guidance for employers on determining an employee’s private use of a vehicle.
Draft Practical Compliance Guideline PCG 2017/D14 should provide more certainty and transparency about the circumstances where the ATO won’t apply compliance resources to investigating whether private vehicle use meets the car-related FBT exemptions.
Eligible employers who rely on this guideline won’t need to keep records to prove that an employee’s private use of a vehicle is minor, infrequent and irregular.
TIP: The guideline includes specific eligibility conditions for employers and their employees’ vehicle use. Talk to us about whether the new guidance applies to your FBT circumstances.
Tax consequences of trust vesting
The ATO has issued a long-awaited ruling on trust vesting, including changing a trust’s vesting date and the CGT and income tax consequences of vesting.
TIP: A trust’s “vesting date” is the day when the beneficiaries’ interests in the trust property become fixed. The trust deed will specify the vesting date and the consequences of that date being reached. Vesting does not, of itself, ordinarily cause the trust to come to an end or cause a new trust to arise. In particular, the underlying trust relationship continues after vesting while the trustee still holds property for the takers.
The key points in the draft ruling are that:
- before vesting, it may be possible to extend the vesting date (by applying to a court or by the trustee exercising a power to nominate a new vesting date);
- it is too late to change the vesting date once it has passed (and the ATO says it is unlikely that a court would agree to do so); and
- continuing to administer a trust in a way that is inconsistent with the vesting terms can have significant CGT and income tax consequences.
Disclosing business tax debt information to credit agencies
The Federal Government has released draft legislation and a draft legislative instrument that, when passed, will authorise the ATO to disclose a business’s tax debt to registered credit reporting bureaus where the business has not effectively engaged with the ATO to manage the debt.
The draft legislation intends to place tax debts on a similar footing as other debts, to encourage timely payment or engagement with the ATO for businesses that want to avoid having their debt information affect their creditworthiness. Disclosure to credit reporting bureaus will only be permitted if the ATO has given the taxpayer at least 21 days’ notice beforehand.
Taxing employee share scheme dividend equivalent payments
The ATO has made a new determination that dividend equivalent payments made under an employee share scheme (ESS) are assessable to an employee as income when they receive the payment for or in connection with services they provide as an employee.
A “dividend equivalent payment” is a cash payment to an employee participant and beneficiary an ESS funded from dividends on which the trustee has been assessed in previous income years because no beneficiary of the trust was entitled to the income at the time.
A trustee that makes a dividend equivalent payment under an ESS must withhold an amount from the payment, even though the trustee is not the employee’s employer.
TIP: The ATO offers a safe harbour from such payments being treated as income under specific circumstances. Get in touch with us to talk about whether your situation makes you eligible.
The new determination applies to dividend equivalent payments paid under the terms and conditions attached to ESS interests granted on or after 1 January 2018.
Superannuation integrity changes
The Government has released a consultation paper and exposure draft legislation to give effect to the following superannuation taxation integrity measures it announced in the 2017–2018 Federal Budget:
- the non-arm’s length income (NALI) rules in s 295-550 of the Income Tax Assessment Act 1997 for related-party superannuation fund transactions will be expanded from 1 July 2018 to also include expenses not incurred that would normally be expected to apply in a commercial arm’s length transaction (e.g. reduced interest expenses, brokerage, accountancy fees or legal costs); and
- a member’s share of the outstanding balance of a limited recourse borrowing arrangement (LRBA) will be included in the member’s “total superannuation balance” for new LRBAs entered into on or after 1 July 2018.
The measures are designed to ensure that related-party transactions with super funds and LRBAs can’t be used to circumvent the reduced contribution caps that apply from 1 July 2017. The changes should generally not affect LRBAs entered into with unrelated third parties for commercial rates of interest (and other expenses).
Guidance for SMSFs on transfer balance reporting
The ATO has released further guidance on when SMSFs need to report events affecting their members’ transfer balance accounts (by making a transfer balance account report, or TBAR) for the purposes of the $1.6 million pension cap.
From 1 July 2018, SMSFs that have any members with a total superannuation balance of $1 million or more must report events impacting that member’s transfer balance account within 28 days after the end of the quarter in which the event occurs.
SMSFs where all members have total super balances of less than $1 million can choose to report events which impact their members’ transfer balances at the same time that the fund lodges its annual return.
The guidance also covers reporting requirements for retirement phase income streams and commutations (including commutation authorities).
Single Touch Payroll – What you need to know
Client Alert – December 2017
Consultation paper: combating phoenix activities
The Federal Government has released a consultation paper proposing company and tax law reforms to combat phoenix activities.
Phoenix activities involve stripping assets from a company that’s in debt and transferring them to another company to avoid paying the first company’s liabilities – that is, the new company “rises from the ashes” of the old one.
The government is considering a range of ways to combat this type of activity, including setting up a hotline for phoenix reporting, adding phoenixing to the offences specifically prohibited under the Corporations Act 2001, making directors personally liable for companies’ unpaid GST, and limiting the ability for sole directors to resign unless there is a replacement director or the company is wound up.
New passive income test for lower corporate tax rate
The Federal Government has recently introduced a Bill into Parliament to ensure that companies with more than 80% passive income will not qualify for the reduced company tax rate.
Under the Bill’s changes to the Income Tax Rates Act 1986, calculations of a business’s “passive income” would include:
- distributions by corporate tax entities (other than non-portfolio dividends);
- franking credits attached to such distributions;
- non-share dividends;
- interest;
- royalties;
- rent;
- gain on qualifying securities;
- net capital gains; and
- amounts included in the assessable income of partners in a partnership or beneficiaries of a trust estate that are referable to another base rate entity passive income amount.
At the time of writing, the Bill is still before the Parliament. When passed, it will apply from the 2017–2018 income year.
The lower company tax rate of 27.5% is available in 2017–2018 for small businesses and corporate base rate entities with turnover of less than $25 million.
ATO guidance: what is “carrying on a business”?
The ATO has issued a draft taxation ruling to explain the factors it will consider when deciding whether a company (incorporated under the Corporations Act 2001) is “carrying on a business”. This is one of the tests companies and small businesses must pass to be eligible for the lower corporate tax rate.
It’s not possible to definitively state whether a company carries on a business, but the draft ruling says that ATO will consider a range of indicating factors. Specifically, a company is likely to be carrying on a business if it:
- is established and maintained to make a profit for its shareholders; and
- invests its assets in gainful activities that have both a purpose and prospect of profit.
Tip: Wondering whether you can access the reduced corporate tax rate? Talk to us today to find out more about how the passive income and carrying on a business tests apply to your situation.
Total superannuation balances and pension transfer balance account reports
The concept of a person’s “total superannuation balance” is now being used to determine whether you are eligible for various super concessions, including the $1.6 million balance limit for non-concessional contributions, Federal Government co-contributions, the spouse contributions tax offset, carrying forward unused concessional contributions and self-managed superannuation fund (SMSF) segregation.
The ATO has recently agreed to modify the reporting obligation for total superannuation balances, recognising that some funds are not in a position to correctly report their correct accumulation phase value for 30 June 2017.
The ATO has also set out when superannuation providers and life insurance companies must lodge transfer balance account reports. The ATO will use the reports to determine if individuals have exceeded their pension transfer balance cap.
An administrative concession will be provided for self-managed superannuation funds (SMSFs), allowing later reporting to help the funds transition to event-based transfer balance cap reporting.
TIP: Super shouldn’t be a “set and forget” arrangement. It’s important to revisit your strategy and consider it carefully, especially in light of the wide range of super changes announced in this year’s Federal Budget.
Fringe benefits tax: should an Uber be treated as a taxi?
Earlier in 2017, the Federal Court ruled that UberX drivers must be registered for GST, because they supply “taxi travel”. There has been much discussion of this finding since, and the ATO is now examining whether Uber trips should be eligible for the “taxi travel” FBT exemption.
The FBT exemption, introduced in 1995, currently only applies to travel in a vehicle that is state or territory licensed to operate as a taxi. However, with the Federal Court’s decision on GST for Uber, and some recent state and territory moves towards licensing changes, the ATO has decided to review its interpretation of the definition of “taxi” in the FBT law.
TIP: Any benefit arising from taxi travel by an employee is exempt from FBT if the travel is a single trip that begins or ends at the employee’s workplace.
In a discussion paper open for comment until late October, the ATO has asked questions such as, “Should the FBT definition of ‘taxi’ be interpreted to include not just vehicles licensed to provide taxi services … [but also] ride-sourcing vehicles and other vehicles for hire?”
TIP: Any benefit arising from an employee’s taxi travel is also exempt from FBT if the travel is a result of the employee’s sickness or injury and the journey is between the employee’s workplace, residence and/or another place appropriate because of the sickness or injury.
Tax treatment of long-term construction contracts
In new Draft Taxation Ruling TR 2017/D8, the ATO explains the methods that taxpayers can use to return income derived and recognise expenses incurred in long-term construction projects. A construction project is considered long-term if it straddles two or more income years.
Two methods of accounting are available: the basic approach (essentially the accruals method) and the estimated profits approach.
Once a particular method is chosen, the ATO expects the taxpayer to apply it consistently for the entire contract. The same method should also be applied to all of the taxpayer’s similar contracts.
The draft ruling also deals with several accounting methods that the ATO does not consider acceptable for long-term construction contracts, including the completed contracts method (bringing profits and losses to account when the contract is completed).
Foreign equity distributions to corporate entities
Two recent taxation determinations from the ATO deal with how the foreign equity distribution rules in the Income Tax Assessment Act 1997 apply where the distribution recipient is a corporate partner in a partnership or a corporate beneficiary of a trust.
Under the rules, a foreign equity distribution is treated as non-assessable, non-exempt income if the recipient is an Australian corporate tax entity that holds a participation interest of at least 10% in the foreign company making the distribution.
The ATO’s view is that a partnership or trust can hold a direct control interest in a foreign company for the purposes of the rules, so that an Australian corporate tax entity can have an indirect participation interest in the foreign company via the partnership or trust.
Client Alert – November 2017
Compensation for ATO systems outages
After the ATO’s unplanned systems outages, it provided lodgment deferrals, and remitted interest and penalties where the outages affected practitioners and their clients’ lodgments.
The ATO has also advised that it assesses claims for compensation in two ways:
- compensation for legal liability (eg negligence); and
- compensation under the Compensation for Detriment caused by Defective Administration (CDDA) scheme, which allows the ATO to consider claims and pay compensation for disadvantage or loss because of defective administration.
The ATO considers claims in accordance with guidelines issued by the Department of Finance.
TIP: If your tax affairs were affected by the ATO systems outages, contact us to find out if you’re eligible to seek compensation.
Small business restructure rollover: changes
The ATO is proposing to modify how the small business restructure rollover (SBRR) operates.
The SBRR means that small businesses can restructure from one legal entity to another – for example, from a company to a trust – and transfer the business’s assets to the new structure without immediately causing a capital gains tax liability.
The ATO’s latest proposed changes address the fact that the transferred business assets in this type of restructure could still give rise to a dividend for the transferee.
TIP: Are you thinking about changing how your small business operates? Talk to us for more information about the options and tax implications.
Tax cut closed off for passive investment companies
The Government has released exposure draft legislation to deny access to the lower corporate tax rate of 27.5% (down from 30%) for companies with predominantly passive income. Under the changes, companies will qualify for the lower tax rate only if:
- their passive income is less than 80% of their assessable income for the year;
- they “carry on a business” in that year; and
- they come below the aggregated turnover threshold for the year ($25 million for 2017–2018).
Identification numbers for directors: an Icarus moment for phoenix activities?
The Government has announced a package of reforms to combat phoenix activities, including the introduction of a Director Identification Number (DIN).
Phoenixing involves deliberately transferring assets from a failed or insolvent company to a new company, with the intention to avoid paying the original company’s creditors, tax and employee entitlements (that is, the new company illegally “rises from the ashes” of the indebted company).
The DIN would identify each director with a unique number, allowing regulators to map the relationships directors have with entities and other people.
Tax measures for affordable housing
The Government has released draft tax legislation to implement elements of its housing affordability plan. The proposed measures include an increased capital gains tax discount for people who hold affordable rental housing investments for at least three years.
Under the draft legislation, managed investment trusts would be allowed to hold affordable housing investments with the main aim of deriving long-term rental income, but purchasing residential property that is not affordable housing would no longer be permitted for these trusts.
TIP: If this legislation is passed, there will be a transitional period for managed investment trusts that already hold non-affordable housing residential property to change their investments to comply with the changes.
Legislation for First Home Super Saver scheme and downsizer super contributions
A Bill has been introduced into Parliament to establish the First Home Super Saver (FHSS) scheme and allow people aged 65 or over to make “downsizer contributions” to their super.
The FHSS scheme will allow people to make voluntary contributions into super, take advantage of the associated tax concessions, and later withdraw the contributions and associated earnings to buy their first home.
The downsizer contribution changes will allow older Australians who sell their main residence from 1 July 2018 to make non-deductible contributions of up to $300,000 to their superannuation from the sale proceeds.
No GST on digital currency: Bill
The GST Act (A New Tax System (Goods and Services Tax) Act 1999) is being amended to ensure that digital currency, such as Bitcoin, is disregarded for GST purposes unless the supply is made in exchange for a payment of money or digital currency.
To achieve this, a definition of “digital currency” will be inserted into the GST Act. Under the new definition, a digital currency has broadly the same features as state fiat currencies (legal tender). In particular, the value of a digital currency must derive from the market’s assessment of its value. A digital currency’s value cannot be based on the value of anything else, so it must not have, for example, a value pegged to Australian or United States dollars.
The currency units must be useable as consideration for any type of supply, and must be generally available to the public.
Units will not be considered digital currency if they give the holder benefits (such as memberships or vouchers), other than entitlements incidental to holding the unit or using it as consideration.
TIP: When the new definition passes into law, no GST will apply for supplies of digital currency made on or after 1 July 2017.
New financial and superannuation complaints authority
Legislation has now been introduced to establish a new external dispute resolution framework and an enhanced internal dispute resolution framework for the Australian financial system.
Consumers will have easy access to a single external dispute resolution scheme, the Australian Financial Complaints Authority (AFCA). Certain firms that provide financial and credit services will need to be members of AFCA, including Australian financial services licensees, unlicensed product issuers, unlicensed secondary sellers, Australian credit licensees and credit representatives, regulated superannuation funds (other than SMSFs), approved deposit funds, retirement savings account providers, annuity providers, and life policy funds and insurers.
Before AFCA will consider a dispute, it will refer the complaint back to the financial firm so it can attempt to resolve the dispute within a defined timeframe. AFCA will also have an independent assessor to investigate any complaints about how disputes are handled.
Superannuation guarantee
Crackdown on employer non-compliance
The Government has announced a package of reforms to give the ATO near-real-time visibility over employers’ superannuation guarantee (SG) compliance. The package includes measures to:
- require super funds to report contributions at least monthly to the ATO;
- roll out Single Touch Payroll (STP); and
- give the ATO the ability to seek court-ordered penalties in severe cases of non-payment.
Salary sacrifice integrity
Legislation has also been introduced to prevent employers from using an employee’s salary sacrifice contributions to reduce the employer’s own minimum SG contributions. This change would apply to working out employers’ SG shortfalls for quarters beginning on or after 1 July 2018
The Goldilocks effect – Economic and market update 4Q 17
The year 2017 was defined by a near-perfect goldilocks backdrop of steady global growth, modest inflation, and still-accommodative monetary policy, the combination of which helped fuel a broad-based rally in asset prices.
Global equities took a step higher, with non-US equities outperforming their US counterparts for the first time in five years, bolstered by a weak dollar and widespread improvement in growth across countries. Even previous weak links of the developed world such as Europe and Japan posted above-trend growth numbers, as rising sentiment, a modest upturn in CAPEX, and the ease of the post-GFC deleveraging cycle gave fresh momentum to domestic demand. In emerging markets, fundamentals have also improved more broadly, against the backdrop of solid Chinese economic data, higher commodity prices, and narrowing current account deficits. On the other hand, Australia appeared to be de-synchronised with the global recovery for most of the year, though the economy did appear to pick up speed as the year progressed, in part due to the effect of coming off a low base from the corresponding quarter in the previous year. For the whole year, the local share market was able to lock in a solid return of 11.9%—its best annual performance since 2013.
All that said, the current backdrop of strong market returns and unusually low financial volatility do raise some concern, as it underscores widespread complacency among investors, despite potential risks being well-known. In particular, valuations in various risk asset classes appear stretched, and the start of monetary policy normalisation in many parts of the world could potentially lead to unexpected consequences. Overall, the odds of a bumpy adjustment in financial markets appear much higher than before, with downside risks, in our view, being more elevated in the equity market than in the bond market.
Of most major economies, the US seems most susceptible to a market correction, with our fair-value CAPE suggesting that US stock valuations are approaching overvalued territory—even after adjusting for lower inflation and interest rates. Meanwhile, the lack of strong inflationary pressures despite robust growth and tight labor markets was undoubtedly a key defining element of the US economy in 2017. Yet that did not stop the Federal Open Market Committee from voting to increase the Federal Funds Rate target range by 25bps to 1.25-1.5% in December. The risk in 2018 is that the tight labour market will grow tighter, driving the unemployment rate well below 4%. Expectations of additional rate hikes would inevitably follow, ending an era of extraordinary monetary support in the US and possibly leading markets to price in more aggressive normalisation plans elsewhere. None of this is status quo.
Global fixed income investments continued to deliver muted returns against a backdrop of low interest rates and low yields across regions, including Australia. Reflecting subdued wage growth and mild inflationary pressure, the Reserve Bank of Australia (RBA) held the cash rate unchanged at 1.5% in December, marking the 16th straight month it has been on hold. Annual returns for cash assets are expected to be muted as official policy rates remain near historic lows.
Europe—risks diminish
Near term Euroscepticism risks appear to have diminished, with rising popular support for the EU in most European countries, though Italian elections in March 2018 could result in a victory to the Eurosceptic populist party, the Five Star Movement. Risks around Brexit are also seen to be more balanced, after the EU and UK made sufficient progress in the financial settlement bill in December, which allowed Brexit negotiations to move into their second phase of discussing future relationships.
China—surprises to the upside
Growth surprised to the upside in 2017, with the full-year GDP growth number coming in at 6.9%, comfortably above the government’s annual 6.5% target. Nonetheless, ongoing policy and regulatory tightening should begin weighing on activity more heavily in 1H18, especially as the government becomes increasingly focus on the “quality” rather than “quantity” of growth this year. In 2018, we expect to see headline GDP slow to around 6.5%.
Japan—rising with the tide
The economy is marching along, with real GDP expanding for seven consecutive quarters, the longest streak for Japan in 16 years. While the expansion so far has come primarily from an acceleration in the export cycle and a mildly expansionary fiscal policy, we expect the recovery to become more broad-based in 2018, as rising confidence, a gradual increase in real wages, and solid profitability leave room for domestic demand to pick-up in 2018. The Bank of Japan is likely to adopt a gradual and flexible approach in 2018, staying vigilant against potentials risks to both the inflation outlook and financial stability.
Australia—rates dilemma
Locally we saw a mixed performance throughout 2017, though the latest national accounts showed an acceleration in year-on-year GDP growth to a slightly above-trend of 2.8% in Q3 2017. Nonetheless, Australia may struggle to sustain this level of growth next year, as the effect of coming off a low base fades and as high leverage and fading dwelling investments put a limit on how fast domestic demand can accelerate. The RBA faces a major dilemma over the next few years, on whether to hike “in the name of financial stability”, or cut “in the name of inflation and wages”. Against this backdrop, the RBA will probably “drag their feet” and wait until late 2018 at the earliest to raise the cash rate.
Qian Wang, Senior Economist
02 February 2018
www.vanguardinvestments.com.au
Tax assessments confirmed for undisclosed business income
The increasing cost of underreporting and failing to lodge.
The Administrative Appeals Tribunal has ruled that the Australian Taxation Office (ATO) was correct to issue tax assessments of $3.7 million and penalties of $3.3 million to a business taxpayer that had underreported its income and failed to lodge several year returns.
The taxpayer argued that it owned and rented out several Sydney properties, but did not engage in other business activities or receive the significant amounts of income that the ATO had assessed to it.
Evidence before the Tribunal showed the taxpayer made a range of expensive capital purchases, including fitness equipment, more than 30 motor vehicles, firearms and a “bomb dog”. Its bank statements included references to “consultation fees”, “gun licenses” and a “security industry register”. A loan application suggested income 20 times what the taxpayer admitted to earning and had apparently made significant loans to related parties with no returns.
The commentary suggested that ATO was better prepared with evidence than the taxpayer.
It is hardly surprising that the Tribunal upheld the assessments and penalties issued and allowed the ATO to impose an extra 20% penalty for two of the taxpayer’s income years.
We report this case mainly to remind taxpayers about that burden of proof is theirs and disputation success can depend on case preparation and credibility.
AcctWeb
Super returns on the up despite clients’ hesitation
While many accountants have reported their clients’ confidence in super is down, it appears there’s some good news on the returns front to kick off 2018.
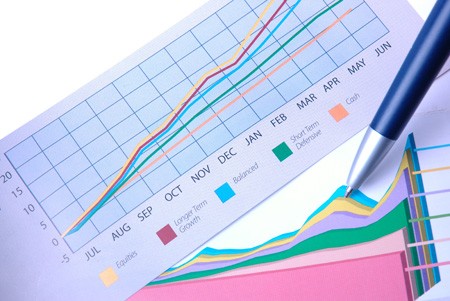
Australian superannuation funds are estimated to have returned 10.5 per cent in 2017, nearly twice as much as the 10-year average, according to SuperRatings research released this week.
The research house said a “late rally” in Australian equities helped bolster returns despite poor performance from global shares.
“Investors will certainly be starting out 2018 on the front foot, despite some of the challenges we have seen throughout the past 12 months,” said SuperRatings chief executive Kirby Rappell.
Mr Rappell said 2017 had been a “frustrating” year for investors, but a falling Australian dollar and support from US market momentum had both helped returns hit the estimated 10.5 per cent – almost double the 5.6 per cent average seen over the last decade.
This figure would also mark the sixth consecutive year of positive returns, the statement added.
As a result of the 2016 federal budget, 2017 saw one of the biggest periods of reform for superannuation since the Costello era. The introduction of a transfer balance cap and the finalisation of event-based reporting were particularly contentious and complex items.
Professionals like Cooper Partners director, Jemma Sanderson, previously told Accountants Daily their clients have been “spooked” by the persistent tinkering with superannuation.
“They've gone through a lot of big changes recently so now they just need to calm down, say no further changes for some time, and let everything settle, let the dust settle, and let the confidence in the system really rebuild itself,” Ms Sanderson said.
“It doesn’t help the confidence in the industry and because superannuation is compulsory for most Australians, it’s an area where a lot of people have an interest from that perspective.
“Every adult Australian tends to have superannuation so we need to maintain the integrity of that system so that it also doesn’t become overly complicated for the general population because a lot of people can't afford to pay for that advice.”
By: Katarina Taurian
03 JANUARY 2018
accountantsdaily.com.au
Australia. All you need to know to be the expert.
An up-to-date snapshot of Australia's vital statistics.
Please click on the following link to see all this interesting information. The areas covered are:
- Overview
- Markets
- GDP
- Labour
- Prices
- Money
- Trade
- Government
- Business
- Consumer
- Housing
- Taxes
- Climate
Access all this data here.
tradingeconomics.com
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News
Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























