
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
Superannuation Guarantee Rates Reminder
The current superannuation guarantee rates for employees has increased to 10% rate from pay periods ending after 1st July 2021. This has changed from the 9.5% superannuation guarantee rate used since 2014.
Employers are encouraged to review their payroll software to ensure that their systems are up to date and are calculating the correct rates. The incorrect rates will lead to unintended underpayments of superannuation, which may attract penalties.
We also recommend that employers review your employee’s contracts to ensure that you are calculating the superannuation correctly on the employees renumeration package. The first quarterly superannuation guarantee subject to the new rate will be September 2021, due by the 28th October 2021.
As a reminder, the following superannuation guarantee (SG) rates are to be implemented in due course:
|
Period |
SG Rate |
|
1 July 2021 to 30 June 2022 |
10.00% |
|
1 July 2022 to 30 June 2023 |
10.50% |
|
1 July 2023 to 30 June 2024 |
11.00% |
|
1 July 2024 to 30 June 2025 |
11.50% |
|
1 July 2025 to 30 June 2026 |
12.00% |
AcctWeb
‘Mammoth consequences’: ATO’s NALI ruling draws ire from accountants
The recent ruling on non-arm’s length income (NALI) in super funds by the ATO will have far-reaching consequences for the superannuation sector, according to industry experts.
First issued as a draft in September 2019, the finalised Law Companion Ruling 2021/2 issued on Wednesday, which clarifies the ATO's interpretation of amendments to NALI rules relating to non-arm’s length expenditure (NALE).
The Institute of Public Accountants, The Tax Institute and Chartered Accountants Australia and New Zealand have now joined together to call for the ruling to be narrowed to the law’s original intent.
“At the same time as the whole super sector has been helping Australians navigate their retirement like never before, they’ve been waiting with bated breath for the finalisation of this ruling which seems to demand perfection,” said the joint bodies.
“The ruling forces all super funds to carefully consider if all losses, outgoings and expenditures have occurred on arm’s length terms.
“It is concerning that if finance teams, accountants or advisers get any transaction wrong in any super fund including APRA regulated funds, that fund could pay the highest marginal tax rate at 45 per cent on all its income including realised capital gains.
“There are mammoth consequences for minor errors which means that solutions need to be worked through very carefully, requiring considerable time and expertise. Because of this potential outcome all super funds need more certainty about how they go about their business.”
The joint bodies note that the LCR 2021/2 ruling applies to a much broader range of circumstances and has much greater impact than what the super industry had understood the original government announcement was targeted at.
“The ruling which has opted to show the broad application of these non-arm’s length rules even to relatively benign situations and the ATO has clearly indicated that it intends to apply a broad interpretation to these rules.
“The ATO has provided multiple opportunities for professional bodies and the industry to comment on these rulings throughout its development and we look forward to continuing this collaboration with the ATO to investigate how this ruling will apply in practice.
“We will also work with the government to request that these rules be narrowed so that benign or minor expenses cannot create such a disproportionate outcome to a super funds’ tax affairs and in turn severely deplete retirement of Australians.”
Increased risks and litigation impacts
With the confirmation of the ruling, DBA Lawyers director Daniel Butler said the ATO has taken a pro-revenue construction of legislation that results in numerous far-reaching and severe consequences.
“The construction that a ‘general expense’ taints all of a fund’s entire income, both ordinary income and statutory income, is the preferred construction posited by the ATO,” Mr Butler said. The ATO does not acknowledge the preferred construction put forward by numerous professional bodies.
“This was not expected by many in the SMSF industry and has caused great concern in the SMSF sector that the ATO may seek to assess many mum and dad SMSFs doing typical dealings.
“Numerous professional bodies submitted that a general expense such as a lower accounting fee has little, if any, nexus to income derived; any connection at best could be described as tenuous and remote.
“The good news is that the ATO will not dedicate its compliance resources if there are reasonable attempts to benchmark an arm’s length service fee being charged.”
Mr Butler said it would remain to be seen how the courts would react to the ruling if such matters proceed to litigation.
“What view would a court cast on say a $100 discount resulting in a 45 per cent tax on an average mum and dad SMSF of $1.3 million with a diversified investment portfolio on the basis that the ATO argue that a $100 discount on an accounting fee has a sufficient connection to every share, managed fund, deposit, interest in real property (direct and indirect) and the fund’s other investments, etc,” Mr Butler explained.
“One would hope that a judge would see the absurd and severe consequences that can result from this construction and construe the NALE provisions in a balanced manner. The rules of statutory construction where tax is being levied must be clear and should be construed accordingly where absurd and unintended consequences arise. That is not to say the ATO are not without an argument, but is it the preferred construction that would hold sway in a court of law?
“Importantly, the ATO is not a law maker and the ruling is light on in relation to providing appropriate reason or authority to support the ATO’s views.
“Despite the ruling not being the law, given taxpayers wear the onus of proof, the ATO view generally prevails as not many taxpayers are prepared to ventilate technical points of law with the ATO that has vast resources at its disposal.”
There is also the risk that some ATO officers may seek to apply NALI inappropriately and give rise to substantial costs to defend unfounded NALI claims, according to Mr Butler.
“There is no formal early engagement and voluntary disclosure for NALI as there is for contraventions of the Superannuation Industry (Supervision) Act 1993 (Cth),” Mr Butler continued.
“Such a system is needed as SMSFs are often afraid to approach the ATO given its recent stance on NALI matters. The ATO should encourage funds to come forward and due to reduced penalties and more flexible approach for engaging with the ATO.”
Conflicting and complex applications
While the ATO has sought to clarify certain points such as whether a person is acting as in an SMSF trustee/director capacity or in their own individual capacity, the ruling has come as a disappointment to many in the superannuation industry.
Heffron managing director Meg Heffron said whilst the ATO has consulted widely, “it has ended up in a place that won’t please a lot of us on every front.”
Ms Heffron noted that the ruling explicitly distinguishes between this type of “once-off NALE” and a similar problem where the expense relates to the purchase of an asset.
“Unfortunately, there is a permanent problem for NALE under these circumstances. The ruling even provides an explicit example where an LRBA is entered into on non-arm’s length terms. Even refinancing and moving to arm’s length terms doesn’t help – all income and capital gains, now and forever, will be NALI,” Ms Heffron said.
“That’s rough. It means there is actually no solution for LRBAs that aren’t set up on a solid market basis.”
Ms Heffron noted that whilst the ATO had softened its original stance on the application of NALI to professionals such as accountants doing work for their own SMSFs using company equipment, there were still plenty of questions to answer in regard to this subject.
“The importance of relying on a licence or insurance – it would seem that (for example) it’s fine for a qualified accountant to do their SMSF’s bookwork on their work computer and using their expertise gained via their work. But if they also lodged their tax return under their firm’s corporate tax agency, that is likely to create a problem,” Ms Heffron said.
“A similar issue would appear to arise for financial advisers. An example provided in the ruling (Example 7, Levi) makes it clear that it’s fine for Levi to place investments for his SMSF (even using his work computer). But we’re unclear as to how far that stretches. If Levi’s SMSF is invested via the same platform as all Levi’s other clients, can he manage it under the same dealer code?
“And finally, the ruling does acknowledge the commercial reality of things like staff discounts. It provides examples about situations where (say) accounting fees for work on SMSFs of the staff who work at the firm can be discounted without automatically creating NALE.
“A key feature of the examples provided, however, is that the trustee/member is not in a position to influence the discount. How far does this go? Could we be in the bizarre situation where I can offer all Heffron staff a discount on their SMSF work but can’t receive one myself because I can influence the decision? It’s not clear.”
Tony Zhang
29 July 2021
smsfadviser.com
ATO Small Business Newsroom – July / August
The ATO provides information on a large number of business related topics, issues, rules and regulations. We hope this article will help quickly you keep up to date.
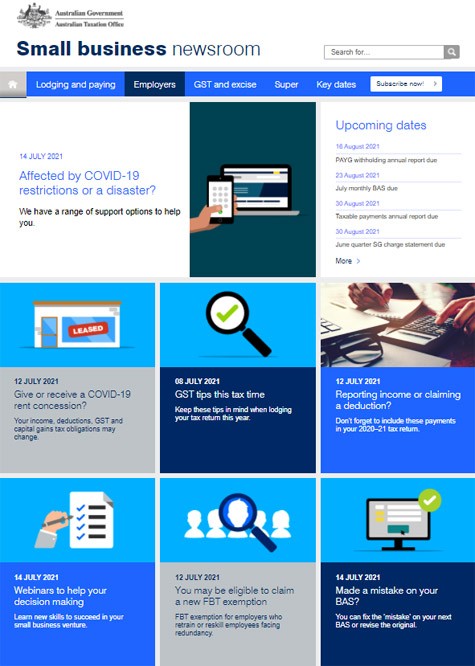
Visiting the ATO's website can be daunting but here is a page that links to information important to small businesses everywhere.
For example:
- Upcoming dates
- Afected by COVID-19
- GST tips
- Reporting income or claiming a deduction
- Made a mistake on your BAS?
- More ….
Click here or the image to access this resource.
ATO
Hardship priority processing of tax returns
If your business is experiencing financial difficulties due to the latest lockdowns, the Australian Taxation Office (ATO) may be able to help by processing your tax return faster and expediting the release of any refund to you.
Priority processing of a business tax return doesn’t guarantee a refund. If your business has outstanding tax or other debts with Australian government agencies, the credit from a return may be used to pay down those debts first.
You can apply for ATO priority processing through your tax professional after the lodgement of the tax return in question. Once the initial request for priority processing is received, you’ll be notified and contacted if more information is required. Processing will take more time for businesses that have lodged several years’ worth of income tax return amendments at the same time, and for those that have unresolved tax debts.
Before lodging any priority processing request, check the progress of your return by contacting your tax professional. If the return is in the final stages of processing, you may not need to lodge a priority processing request – the return will be finalised before the ATO has an opportunity to consider the request.
AcctWeb
‘Nowhere to hide’: New gig economy reporting regime set to debut
Share economy participants will no longer be able to evade their tax obligations as the government looks to legislate a new compulsory reporting regime.
The new reporting regime will see share economy platforms — such as Uber, Airbnb and Deliveroo — required to report information of all transactions to the ATO, in the same way the taxable payments reporting system (TPRS) is being currently applied across a number of industries.
Transactions relating to a ride-sourcing or a short-term accommodation service will be first in line for the reporting regime, with share economy platforms required to report these transactions from 1 July 2022.
All other share economy transactions will fall under the new reporting regime from 1 July 2023.
The ATO will specify the frequency of the reporting but has indicated that it will begin requiring reports on a biannual basis.
Draft legislation released by the Treasury on Tuesday notes that all electronic platforms that allow entities to make supplies available to an end-user consumer through the platform will be covered by the new regime.
It includes platforms such as a website, internet portal, app, gateway, store or marketplace.
The requirement will generally not apply if the transaction only relates to a supply of goods where ownership of the goods permanently changed, where title to real property is transferred, or the supply is a financial supply.
The measure, first raised in the 2019–20 Mid-Year Economic and Fiscal Outlook, comes after the Black Economy Taskforce found that without a reporting regime in place, it would be difficult for the ATO to gain information on compliance of sharing economy participants unless targeted audits were used.
It also argued that a reporting regime would send a clear signal to sharing economy participants that in most cases payments would be taxable.
The Institute of Public Accountants’ Tony Greco, who sits on the taskforce, believes the new reporting regime will send a strong message to gig economy participants.
“There’s nowhere to hide anymore,” said Mr Greco. “If you are a participant and whether it was intentional or unintentional that you didn’t report that income, those days are over.
“It is a significant and growing part of the economy and the risk to revenue just becomes too big to ignore.
“Participants will have nowhere to hide once the reporting regime takes hold which will lead to a level playing field with other sources of income such as wages.”
Jotham Lian
07 July 2021
accountantsdaily.com.au
COVID-19 disaster payments to be tax-free: Prime Minister Scott Morrison
Prime Minister Scott Morrison has declared that COVID-19 disaster payments will now be tax-free, a policy change that will have ramifications for accountants and their clients, say tax experts.
Mr Morrison told ABC Radio on Thursday morning that the federally funded income support scheme would now provide tax-free payments of $750 a week to workers who lose 20 or more hours of work a week, and $450 a week to those who lose between eight and 20 hours.
The PM then stressed his point on Seven Network’s Sunrise, stating, “I’ve made that very clear this morning, back through the system, they won’t be taxable. JobKeeper, by the way, was.”
Mr Morrison’s position comes despite the Treasury, the ATO and Services Australia all publicly noting that COVID-19 disaster payments are taxable income.
A Treasury official told Accountants Daily that a policy change had indeed been made and that the Treasury was in the process of updating its guidance as of Friday morning.
A legislative change is unlikely to be required, given the COVID-19 disaster payment is authorised under regulations issued by the Governor-General rather than through legislation.
The Institute of Public Accountants general manager of technical policy, Tony Greco, said granting the $750 a week payment with a tax-free status would mean workers will take home more than they did under the original JobKeeper program.
Disaster payment recipients can expect to be better off by $90 a week compared with the JobKeeper wage subsidy, based on an annualised $39,000 income of $750 each week.
“The main concern is that these payments have always been stated as assessable, so now there’s confusion,” said Mr Greco. “It is a significant shift in treatment from what people have been told and what we have come to expect.
“This is a seismic shift in the tax treatment for recipients and a windfall which will come at a huge cost to the taxpayer.”
Michael Croker, tax leader at Chartered Accountants Australia and New Zealand, said the policy change would come at a bigger cost to taxpayers and open up questions around the taxable status of payments made since 3 June — the day the COVID-19 disaster payment was announced.
“Tax policy wonks will be concerned about the so-called income and substitution effects,” said Mr Croker.
“Within the hard-hit NSW business community, the new policy will be factored into the question often put to accountants: ‘Is it better to stand down workers, lower business labour costs and send them to Services Australia for the COVID-19 disaster payment?’.
“For some low-paid workers, $750 tax-free a week could even be a temporary pay rise, an outcome at odds to the take-home pay of a comparable employee still on the business’s payroll.”
According to Mr Morrison, more than $490 million in COVID-19 disaster payments have been paid to over 955,000 workers in NSW and Victoria.
The payments, which were increased on Wednesday from $600 to $750 a week for workers who lost more than 20 hours, and raised from $450 from $375 for those who lost between eight and 20 hours, are expected to cost the federal government $750 million a week.
Jotham Lian
30 July 2021
accountantsdaily.com.au
Tax mix to rely more heavily on income tax as the Treasurer ducks austerity
The Australian economy is predicted to grow “slower than previously thought” over the next 40 years, as the nation grapples with a tax mix that relies heavily on income tax despite an ageing population.
The federal government on Monday released its 2021 Intergenerational Report (IGR), the fifth of its kind, which forecast slowed growth for the Australian economy over the next 40 years as Australia’s population ages, and puts pressure on federal deficit repayment.
Personal income tax receipts are expected to grow faster than GDP, increasing from 11.1 per cent of GDP in 2020–21 to 12.7 per cent of GSP in 2035–36.
This will account for 53.1 per cent of total taxation receipts, up from 49.6 per cent this financial year.
The report goes on to suggest that company tax receipts will likely remain volatile as indirect and consumption-based taxes form a smaller proportion of total tax receipts than they have in the past.
Committee for Economic Development of Australia (CEDA) chief executive Melinda Cilento said the government’s assumption that Australia’s tax mix will mostly rely on income tax isn’t a realistic one.
“Comprehensive tax reform must be put back on the table, with a renewed resolve to reshape the system to sustain a strong and dynamic economy and pay for the essential services so important to our communities,” Ms Cilento said.
Treasurer Josh Frydenberg said the report details the long-tail impacts the COVID-19 pandemic are likely to mount in the face of the Australian economy but warned against hiking taxes.
“Our population is growing slower and ageing faster than expected,” Mr Frydenberg said. “The Australian economy will continue to grow, but slower than previously thought. Growth will continue to be highly dependent on productivity gains.
“Growing the economy is Australia’s pathway to budget repair, not austerity or higher taxes. Only by growing the economy can we continue to guarantee the essential services Australians rely on.”
An ageing population
According to the IGR, the old-age dependency ratio in 2019–20 was 4.0 working-age people for every person aged over 65. The ratio is projected to fall further by 2060–61 to 2.7 working-age people for every person over 65.
The fall, according to the report, presents challenges for Australia’s long-term economic growth and fiscal outlook, as a working-age person’s taxes will be required to support a greater number of people aged over 65, with no revenue mechanisms yet in place to offset the nation’s ageing population unable to work.
It highlights that a larger, older population will require greater government spending in healthcare, the Age Pension and end-of-life support, and has implications for participation and productivity growth.
As the population continues to age and adds pressure to the budget, the report suggests government policy will need to adapt and foster economic growth to overcome these fiscal challenges, instead of generating feasible revenue streams to support them.
“While Australia’s debt is sustainable and low by international standards, the ageing of our population will put significant pressures on both revenue and expenditure,” it said.
The report goes on to highlight that future governments will need to manage spending pressures by “improving the efficiency of service delivery” and delivering services like health and aged care via targeted programs paid for by the lowest, most “efficient” taxes possible.
Mr Frydenberg said federal deficits are expected to decline from current GDP of 7.8 per cent to 0.7 of a percentage point in 2036–37, before widening to 2.3 per cent in 2060–61.
“It’s a trajectory similar to many of the previous IGRs reflecting the impact of an ageing population and existing policy settings,” Mr Frydenberg said. “However, the budget position is significantly better than projected in most past IGRs.
“The Howard government’s 2002 and 2007 IGRs forecast deficits at the end of the 40-year period of 7 per cent and 5 per cent, respectively, and the Rudd government's 2010 IGR forecast a deficit of 4 per cent in 2050.”
On economic growth, the Treasurer said governments will need to invest further in skills, infrastructure and digital transformation, along with a more efficient tax system, though he shied away from detailing what that might look like, in both his speech, and the report.
“With productivity responsible for over 80 per cent of Australia’s national income growth over the past 30 years, the task is obvious and the choice is clear,” Mr Frydenberg said.
“If we want to maintain our living standards, generate higher wages and create more jobs, Australia has no alternative other than to pursue economic reform, much of which is hard and contested.”
John Buckley
29 June 2021
accountantsdaily.com.au
Tax implications – more than one job
If you are working two or more jobs casually or have overlapping contract work, you need to be careful to avoid an unexpected end of financial year tax debt.
With insecure, contract and casual work becoming increasingly common, particularly in the current COVID-19 affected economy, it’s no surprise that many young and not-so-young Australians may have income from more than one job.
A tax debt may arise where a person with more than one job claims the tax-free threshold in relation to multiple employers, resulting in too little tax being withheld overall. To avoid that, you need to look carefully at how much you’ll be earning and adjust the pay as you go (PAYG) tax withheld accordingly.
Currently, the tax-free threshold is $18,200, which means that if you’re an Australian resident for tax purposes, the first $18,200 of your yearly income isn’t subject to tax. This works out to roughly $350 a week.
A simple solution for people who have more than one employer/payer at the same time is only claim the tax-free threshold from the employer who usually pays the highest salary or wage. The other employer/payer will then withhold tax from your payments at a higher rate (the “no tax-free threshold” rate).
If you have two or more incomes, for example from casual or contract jobs or because you get a pension and have part-time employment income, we can help you figure out your tax withholding arrangements and avoid a surprising bill at tax time.
AcctWeb
ATO extends Division 7A COVID-19 relief
The Tax Office has extended relief for taxpayers who are unable to meet the minimum yearly repayments on Division 7A loans due to COVID-19.
On Monday, the ATO confirmed it would offer an extension of the repayment period for those who are unable to make their minimum yearly repayments (MYRs) by the end of the lender’s 2020–21 income year due to the ongoing effects of COVID-19 under section 109RD.
A similar extension was provided last year for the 2019–20 MYR. Taxpayers who obtained the extension last year will be required to make up the shortfall of their 2019–20 MYR by 30 June 2021.
Borrowers seeking the relief this year will be required to complete a streamlined online application form where they will be asked to confirm the shortfall, that the COVID-19 situation has affected them and that they are unable to pay the MYR as a result.
The ATO can only make a decision in writing after the end of the lender’s 2020–21 income year, within 28 days on receipt of the lodgement form.
Once approved, borrowers will be informed that they will not be considered to have received an unfranked dividend if the shortfall is paid by 30 June 2022.
The streamlined application process only applies to applications for an extension of the 2019–20 and 2020–21 MYR of up to 12 months under section 109RD for COVID-19-affected borrowers, with the ATO noting that it is not intended to be available in the 2021–22 income year and beyond.
Borrowers can still apply to obtain a longer extension of time outside the streamlined process under section 109RD, or for relief on the grounds of undue hardship under section 109Q.
Further details and the approved ATO form can be accessed here.
Jotham Lian
22 June 2021
accountantsdaily.com.au
Super transfer balance cap increase from 1 July 2021
This year will be the first indexation increase of the $1.6 million pension limit.
If you’re nearing retirement and have a large amount in your transfer balance account, it may be wise to take advantage of this after 1 July 2021 due to the pension transfer cap increase from $1.6 million to $1.7 million.
At the time you first commence a retirement phase superannuation income stream, your “personal transfer balance cap” is set at the general transfer balance cap for that financial year.
When the general transfer balance cap is indexed to $1.7 million from 1 July 2021, there won’t be a single cap that applies to all individuals. Rather, every individual will have their own personal transfer balance cap of between $1.6 million and $1.7 million.
Each calculation will be dependent on member balance in each superannuation account and pension start date.
AcctWeb
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























