
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
ATO targets dodgy deductions for holiday homes
Thousands of dollars in claims “that would fail the pub test” contribute to $1.6bn tax shortfall, assistant commissioner says.
.
Expense claims running to thousands of dollars for occasionally rented holiday homes fail the pub test and will fall foul of the ATO’s crackdown on property deductions, says assistant commissioner Kath Anderson.
She said 2.2 million property owners filed rental expense claims of $42.6 billion in 2021, but full compliance by the sector would add $1.6 billion in revenue and she called on tax agents to help bring owners into line.
“Holiday homes might sound minor in the scheme of things,” Ms Anderson said at last week’s Accountants Daily Strategy Days in Melbourne and Sydney. “But if we applied the pub test, I don't think we would find many Australians would think it's OK for someone to claim thousands – in some cases hundreds of thousands – of dollars in deductions for their holiday home.
“Many of the returns that have errors in them have actually been prepared by agents. Quite often clients are not telling their agents or providing them with all of the information that they should.
“We need your help to educate clients about what is a valid rental deduction and what's not. We also need your help to get the message out there that claiming deductions and effectively taking money from the community to pay for your holiday home is not OK.”
Ms Anderson said rental property claims were high on the ATO’s hitlist for 2022-23 as it attempted to reduce the tax gap – the difference between what is collected and what full compliance would yield – down from $33 billion.
“The gap represents an unfair advantage that those not doing the right thing have over those who are doing the right thing. And in the context of a business, especially a small business, this unfair advantage can be significant.
“As you would expect, integrity and levelling that playing field will continue to be a high priority for us.”
The recent budget had delivered funding to extend the personal income tax compliance program for two years and, as well as rentals, omitted income and work expenses were also key targets.
She said work-related claims accounted for $3.7 billion of the tax gap and while many were “optimistic” characterisations of personal expenses some were more creative, “like the Maltese terrier guard dog or weekends away for stress relief”.
Increasing digitisation of ATO processes was a key feature of the compliance mission but would also make the work of tax agents easier.
“In 2022-23, you'll see us continuing to use data as much as we can. We’ll provide it in prefill will harness advances in digitalisation and data to provide more real time nudges and prompts for income and claims that seems to be a little bit outside of the norm,” she said.
“We've been delivering nudges and individual income tax returns for some time now, but we're also starting to use nudges in relation to GST reporting by delivering those upfront messages for clients that are due to get a refund, just helping them to check their claims before they finish lodging.
“Enabling them to self correct where they've made an error removes the need for follow-up contact from us, which nobody likes.”
As of October, GST lodgement nudge messaging had resulted in corrections of about $57 million and approximately 400,000 individual income tax returns had been fixed up in real time before being finalised.
With lodgement deferrals at a record high number of almost 2 million over the past year, another ATO initiative would make the process smoother.
“We know that the lodgement deferrals process can be an irritant for you,” she said. “We've not only listened, but we've actually taken active steps to address your concerns. A new lodgements deferrals function in online services for agents will be delivered in the first part of 2023.
“I'm sure you'll be happy to hear that a new lodgements deferrals function in Online Services for Agents will be delivered in the first part of 2023. Now this is a digitised version of that current clunky spreadsheet, which is more intuitive lodgement deferral experience and it will also deliver real-time visibility and quicker processing times.”
Philip King
06 December 2022
accountantsdaily.com.au
How crypto assets can trigger CGT tripwires
Lending digital currency can be viewed as disposal while losses from the recent downturn may offer little relief from previous capital gains.
.
In its October 2021 report, the Select Committee on Australia as a Technology and Financial Centre (Senate Report) canvassed the uncertainty and potential harsh tax outcomes presented by cryptocurrencies and other digital assets.
In particular, the Senate Report discussed how the existing tax framework did not contemplate such technology, and as a result, whenever a crypto asset interacts with a protocol where it is swapped, accessed, staked, wrapped, burned or exchanged, CGT event A1 may be triggered.[1]
Regardless of whether you are familiar with these precise terms, the point to note is that when it comes to digital assets, CGT liabilities may be inadvertently triggered in cases where there may have been no underlying disposal, including, for instance, from mere technological upgrades akin to a stock split.[2]
Once triggered, taxpayers cannot rely on CGT rollover relief to mitigate the consequences of this outcome as the strict and limited requirements for rollover do not extend to digital assets.
After outlining these potential tax issues by reference to various submissions, the Senate Report recommended that the CGT regime be amended so that digital asset transactions only create a CGT event when they genuinely result in a clearly definable capital gain or loss.[3]
An example of an inadvertent tax liability – “lending” or “staking” digital assets
By way of example, it may surprise some crypto users that an ATO officer had informally flagged that “lending” digital assets may trigger CGT event A1 (a disposal).[4] So while a “lender” may consider that they continue to hold the “lent” asset”, depending on the particular terms under which it occurs, the “lending” may actually result in a disposal within the meaning of CGT event A1.
Although the latest FTX scandal may have constituted fraud, it serves as a timely reminder of the need to carefully and thoroughly understand how each product/arrangement is governed and what risks exist, including counterparty risk. It is only by carefully analysing the terms of the arrangement and understanding your precise legal rights as the “lender” that the commercial risks and resulting taxation implications can be properly identified.
To this end, the specific terms adopted to conveniently describe an offering may not accurately reflect the actual commercial and legal realities.
To properly understand the tax ramifications of “lending” digital assets, including whether CGT event A1 is triggered, it may be necessary to consider whether the “lender” will continue to hold legal title and/or beneficial title. The analysis of whether ownership is retained can be further complicated in circumstances where the “lender” relinquishes control of the digital assets and subjects it to a self-executing “smart contract”.
Takeaway
It is important not to rely on labels but to properly review the terms of all arrangements and new product offerings to ensure you understand your rights. It is only after doing so that you can properly assess the risks as well as the taxation ramifications.
Digital assets, including bitcoin, are not regarded as currencies and that outcome is about to be enshrined in legislation. As a result, they will likely fall within the CGT regime and they will not be eligible for the Commissioner’s administrative indulgence not to treat them as CGT assets.[5]
Crystallising large capital losses during the latest downturn may be of limited use in mitigating the consequences of having triggered inadvertent capital gains at market highs in earlier income years.
The Board of Taxation is considering the tax treatment of digital assets and is due to report this month.
Jeremy Makowski is special counsel in tax at law firm Cornwalls.
Jeremy Makowski
23 December 2022
accountantsdaily.com.au
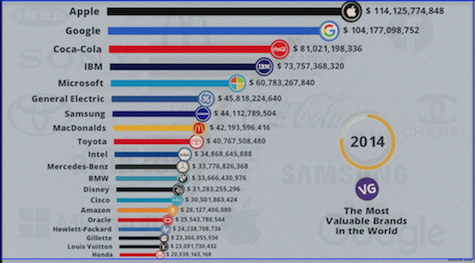
The Most Valuable Brands in the World 2000 – 2022
Check out who are the biggest brands in the world.
.
FBT – Christmas Parties and Taxi Fare/Rideshare
Some employers, who are commendably anxious to protect their employees and clients from the drink/driving laws, also pay for taxis/rideshare to and from the place of entertainment.
For FBT purposes there may be different consequences for payment of the taxi fare. For clients, the taxi fare is considered to be part of the entertainment expense and no deduction is allowable. For employees, if the fare is for travel from home to the place of entertainment (not being their place of employment) and return home again, the benefit is considered to be for the facilitation of entertainment and is not a separate benefit from the entertainment itself.
The result is that the employer would then have to rely on the total entertainment package being under $300 for the minor benefit rule to apply.
However, if the Christmas function is held on the employer’s premises, the taxi trip is FBT exempt if it is a single trip beginning or ending at the employer’s premises. For example, the exemption would apply if the employee went from the workplace to home, or any other place.
However, the exemption would not apply if the trip was broken and continued at some other time. For example, the employee gets a taxi from the workplace and goes out to a nightclub; that trip is deductible and exempt from FBT. If the employee later gets another cab to home, that leg of the trip would be deductible to the employer but FBT would be payable.
Note however, that if the employer is using the 50/50 split method of calculating FBT and deductions, the taxi travel would always be included in the cost of entertainment, and there would be no exempt journey for travel from the workplace to home.
Uber and other ride sharing services are now also included for FBT exemption as taxi services, after recent changes to the FBT Act, from 1st April 2019.
AcctWeb
Working from home during a COVID-19 lockdown: Can you claim a tax deduction for rent?
The ATO has long held firm on the principle that rent payments (being a form of occupancy costs) are generally outgoings “of a private or domestic nature” and therefore not deductible, even where part of the rented home is used as a home office. However, it has been accepted that in some circumstances, a rent deduction may be claimed if a part of the home is used exclusively for income-producing activities and there is no alternative place of business provided by the taxpayer’s employer.
But with Sydney and Melbourne being plunged into months-long lockdowns, can anyone working from home now claim a tax deduction for paying their rent? After all, office accommodation is explicitly prohibited by state public health orders, and workers have had no choice but to use their primary residence as an office. Some workers may have even moved from the inner city to a larger residence in the suburbs to expand their home office!
Read on for our breakdown of the relevant legislation and case authority that might open the door for claiming a deduction for rent during the COVID-19 pandemic.
When are home office expenses deductible?
Income tax deductions are governed by the Income Tax Assessment Act 1997 (Cth) (ITAA 1997). In particular, s 8-1 sets out the general principle that “any loss or outgoing” is deductible from your assessable income if it is “incurred in gaining or producing your assessable income”; or it is necessarily included in carrying on a “business for the purpose of gaining or producing your assessable income”. However, this is subject to certain exclusions. One of which is that you cannot deduct a loss or outgoing under this principle if “it is a loss or outgoing of a private or domestic nature”.
The principle that expenses of a “private or domestic nature” are not deductible is the reason that the ATO has generally distinguished between two broad categories of costs associated with running a home office. They are:
- (a) Occupancy expenses: Expenses relating to the ownership or use of a home (e.g. rent, mortgage interest, home insurance premiums) that are not affected by the taxpayer’s income-earning activities
- (b) Running expenses: Expenses relating to the use of facilities within the home (e.g. electricity, cleaning costs and furniture)
ATO views – Taxation Ruling TR 93/30
The current ATO position as set out in Taxation Ruling TR 93/30 is that running expenses for any home office can be deductible for the area of the home that is used as a “place of business”, for the portion of time that area is used as a place of business. However, occupancy expenses are only deductible for an area of a home that “has the character of a place of business” – otherwise, occupancy expenses are of a “private or domestic nature” and are not deductible.
Generally, the courts and tribunals have refused to consider a home office as having the “character of a place of business” where working from home is a “matter of convenience”, or choice, to the taxpayer. TR 93/30 sets three requirements which, if satisfied, will qualify a home office as having the character of a place of business allowing for the deduction of occupancy costs:
- It is a requirement inherent in the nature of the taxpayer’s activities that the taxpayer needs a place of business
- The taxpayer’s circumstances are such that there is no alternative place of business and it was necessary to work from home
- The room or home office is used exclusively or almost exclusively for income producing purposes (TR 93/30)
These principles have been applied in several tribunal cases. For example, the 1986 decision Case T48, 86 ATC 389 (Case T48). In Case T48, the taxpayer was employed by a major oil company as a territory manager. The company provided no office or equivalent for the taxpayer to perform his duties and it was expected that it was his responsibility to provide one. The taxpayer used one bedroom in his rented two-bedroom flat exclusively as an office, and claimed a deduction for a portion of his rent (calculated as the percentage of the total floor area that the office space comprised). The Board of Review allowed this claim on the basis that the home office had the “character of a place of business” sufficient to displace the presumption that rent was an expense of a private or domestic nature. In more recent times, a similar finding was made in McAteer v FC of T 2020 ATC ¶10-536; [2020] AATA 1795, regarding an on-call IT support worker who was not working from home merely for convenience. Does COVID-19 open the door to deductions for rent?
In normal times, most office workers cannot claim a deduction for their rent for using a home office, given an office is provided by their employer. However, during the COVID-19 pandemic lockdown, the office cannot be accessed – stay-at-home restrictions and capacity restrictions have forced many people to work from home for prolonged periods. Applying the second requirement in TR 93/30, many taxpayer’s circumstances are such that there is no alternative place of business and it is necessary to work from home.
The third requirement, that the room or home office is used exclusively (or almost exclusively) for income-producing purposes, may depend on the taxpayer’s particular circumstances and home set-up. However, for many workers currently stuck in lockdown, an exclusive (or almost exclusive) home office space is no longer a luxury but a necessity. This is especially so for workers who have frequent online meetings with clients and teammates that concern sensitive or confidential information, those that need a dedicated distraction-free space, not to mention those who have children at home.
While the ATO has published information on “Working from home during COVID-19” on its website and has made available a short-cut method for claiming running costs, very little has been published regarding claiming occupancy costs (such as rent). In the current COVID-19 pandemic environment, whether your circumstances permit you to claim a deduction for occupancy costs such as rent is certainly worth careful consideration.
This article is the opinion of the author and in no way constitutes legal advice. We recommend reaching out to our expert tax law team who will be able to advise you on your specific circumstances.
Andrew Henshaw, managing director and Fiona Bucknall, paralegal, Velocity Legal
Andrew Henshaw and Fiona Bucknall, Velocity Legal
17 September 2021
www.accountantsdaily.com.au
Recontributions of COVID-19 early released super
Under the COVID-19 early release measures, individuals could apply to have up to $10,000 of their super released during the 2019–2020 financial year and another $10,000 released between 1 July and 31 December 2020.
Between 20 April 2020 and 31 December 2020, the ATO received 4.78 million applications for early release, totalling $39.2 billion worth of super.
Not everyone who applied to have super released ended up needing to use it once the government ramped up its financial support programs. From 1 July 2021, people who received a COVID-19 super early release amount can recontribute to their super up to the amount they released, and those recontributions will not count towards their non-concessional contributions cap.
The recontribution amounts must be made between 1 July 2021 and 30 June 2030 and super funds must be notified about the recontribution either before or at the time of making the recontribution.
Shaun
W MARSHALL & ASSOCIATES
https://www.marshals.com.au/
ATO announces STP Phase 2 blanket deferral
Australian employers will now have two more months to transition to the second phase of Single Touch Payroll as the ATO announces a blanket deferral in light of the current business environment.
The ATO has revealed that employers that begin reporting additional payroll information required under STP Phase 2 by 1 March 2022 will be considered to have met its 1 January 2022 deadline.
“Whilst the start date for STP phase 2 remains 1 January 2022, the ATO is committed to supporting employers transition to STP Phase 2 reporting by being flexible, reasonable and pragmatic,” an ATO spokesperson told Accountants Daily.
“Where an employer’s payroll solution is ready and they can start reporting from 1 January 2022, the ATO will support and encourage them to do so.
“Employers whose payroll solution is ready for 1 January 2022 will be considered to be reporting on time provided they start Phase 2 reporting before 1 March 2022. They will not need to apply to the ATO for more time.”
STP Phase 2 reporting will see additional information, including a breakdown of gross amounts and income types, required to be reported to the ATO each payday, and subsequently shared with Services Australia in a bid to reduce employers’ reporting obligations to multiple government agencies.
With STP Phase 2 heavily reliant on software providers to update their payroll solutions, the ATO has also announced that further deferrals will be available to providers that need more time. Customers of these software providers will automatically be covered by that deferral.
Further to the deferrals, no penalties will be applied for honest mistakes made during the first year of reporting the expanded data.
The concessions come after key accounting and business groups told the Tax Office that preparing for the expanded reporting was not a priority for businesses and their advisers, particularly in NSW and Victoria where extended lockdowns drag on.
It is the second time the ATO has moved on its STP Phase 2 deadline, after previously bowing to pressure to defer its proposed 1 July 2021 start date to 1 January 2022.
Matthew Addison, executive director of the Institute of Certified Bookkeepers, said the ATO’s concessions would come as a relief for many practitioners and their clients.
“Workloads and deadlines are abnormal at this time and the statement by the ATO that they allow an implementation deferral until 1 March 2022 is welcome,” he said.
Likewise, the Institute of Public Accountants general manager of technical policy Tony Greco said the profession would welcome any concession after a torrid 18 months.
“In a perfect world we welcome reforms such as STP 2, it’s just that it competes with a backlog of other work that just gets pushed aside to respond to emergencies, such [as] helping clients access vital business support to keep businesses afloat,” said Mr Greco.
“Practitioners have not experienced business as usual conditions since March last year.
“The ATO has acknowledged the workload predicament facing practitioners. The profession will take any concessions gratefully. Any further concessions delaying other measures would be appreciated especially for practitioners facing fortnightly retesting required for clients who wish to continue to receive NSW JobSaver payments.”
Jotham Lian
24 September 2021
www.accountantsdaily.com.au
Reminder: super changes for the 2021 financial year
The government’s long-slated “flexibility in superannuation” legislation is finally law.
This means from 1 July 2021, individuals aged 65 and 66 can now access the bring-forward arrangement in relation to non-concessional super contributions. The excess contributions charge will be removed for anyone who exceeds their concessional contributions cap, and individuals who received a COVID-19 super early release amount can now recontribute it without hitting their non-concessional cap.
Previously, if you made super contributions above the annual non-concessional contributions cap, you could automatically access future year caps if you were under 65 at any time in the financial year.
The bring-forward arrangement allows you to make non-concessional contributions of up to three times the annual non-concessional contributions cap in that financial year. Note for the 2021 income year, the non-concessional contribution cap limit was $110,000.
In addition, individuals who previously exceeded their concessional contributions cap would have to pay the excess contributions charge (around 3%) as well as the additional tax due when excess contributions were re-included in their assessable income.
However, people who exceed their cap on or after 1 July 2021 will no longer pay the charge, but will still receive a determination and be taxed at their marginal tax rate on any excess concessional contributions amount, less a 15% tax offset to account for the contributions tax already paid by their super fund.
Shaun
W MARSHALL & ASSOCIATES
https://www.marshals.com.au/
Greenhouse gas emission by country since 1880
The total sum of CO2 emissions since 1880 (in tons). Food for thought, that's for sure

Treasury consults on increase to charities financial reporting threshold
The revenue thresholds defining small, medium and large charities are set to be raised, saving over 5,000 charities the need to produce reviewed or audited financial statements.
Treasury is now consulting on exposure draft legislation that the government hopes will reduce red tape, and increase transparency of, the charity sector.
Among the changes is an increase to the revenue thresholds for charities, with small charities to be defined as those with an annual revenue below $500,000, up from the current $250,000 threshold.
Medium-sized charities, currently defined as those with revenues between $250,000 and $1 million, will now see the threshold raised to $500,000 to less than $3 million.
Likewise, large charities will be defined as those with revenues of $3 million or more.
The higher annual revenue thresholds will have a direct impact on a charity’s annual reporting obligations, with approximately 2,500 small charities no longer being required to produce annual financial reports, saving each charity around $2,400 in accounting fees annually.
Over 2,700 medium-sized charities will also no longer be required to produce audited financial statements, saving them around $3,000 in accounting expenses annually.
The proposed thresholds, however, remain lower than those recommended by the ACNC’s 2018 review. It had called for the thresholds to be increased to less than $1 million for a small entity, from $1 million to less than $5 million for a medium entity, and $5 million or more for a large entity.
Other changes proposed in the exposure draft legislation include a requirement for all registered charities to disclose related party transactions, with small registered charities to make a simplified disclosure involving a brief description of related party transactions.
According to Treasury, the change will provide greater transparency and accountability, particularly around “transactions that pose a higher risk to charitable assets being used for private benefit”.
The regulations will provide an exemption to medium and large charities with only one remunerated key management person, from the requirement to disclose, as part of their related party transactions, aggregate remuneration paid to responsible persons and senior executives.
Jotham Lian
22 September 2021
www.accountantsdaily.com.au
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























