
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
The year of workplace law upheaval
Parliament, the FWO, unions, employees and employers alike grappled with the ever-complex Fair Work Act in 2023.
.
The Fair Work Ombudsman has had a very busy year. Its 2023 annual report detailed $509 million in unpaid wages recovered for 251,475 workers in FY 2022-23, the second-highest result after $532 million was clawed back only a year prior.
The workplace watchdog and chief enforcer of the Fair Work Act also said it entered into 15 enforceable undertakings, filed 81 lawsuits and issued 2,424 compliance notices.
FWO boss Anna Booth called for businesses, especially big corporates and universities, to do better, with names like Suncorp, David Jones, Politix, Crown, UTS, Starbucks, Best & Less and St Vincent’s all guilty of underpaying workers.
“All employers must place a higher priority on ensuring they are meeting all their workers’ lawful entitlements, including by improving their payroll and governance and investing in advice,” Ms Booth said.
However, Rebecca Thistleton, director of thinktank McKell Institute, said that for every one of the FWO’s successes, “we know there are far more instances that are never investigated and workers who are never properly compensated”.
The FWO only recovered about two-thirds of an estimated $850 million in yearly unpaid wages and businesses habitually exploited its limited resources, the McKell Institute said.
CEO Ed Cavanough said actual wage theft could be as high as $1.35 billion since data failed to capture the incorrect payment of penalty or award rates.
“This is an extraordinary amount of money being stolen and it’s unacceptable,” he said. “Being unaware is not an excuse. The onus is on employers to understand their obligations to their employees,” he said.
In December, National Tertiary Education Union president Alison Barnes called out universities’ governance models after the union’s analysis found “rampant” wage theft among virtually every major university across the country.
The NTEU believes that 97,000 staff are owed $159 million, a $50 million increase since its report in February.
“The fact that wage theft is so widespread in Australian universities is a damning indictment of the current governance model,” she said.
Ms Barnes said wage theft was driven by the sector’s widespread use of casual staff, with two-thirds of all university workers employed “insecurely” through casual or fixed-term arrangements.
“If universities are to finally become exemplary employers then we need to end the scourge of casualisation using state and federal powers,” she said.
The union also said it was involved in eight ongoing cases and echoed the McKell Institute’s suspicions that wage theft estimates understated the true extent of the problem.
Similarly, the Shop, Distributive and Allied Employees Association sued discount supermarket chain Aldi for $150 million in unpaid wages. “Over $100 million has been ripped out of the pockets of workers and their families by this multi-billion-dollar corporation,” said national secretary Gerard Dwyer.
The Aldi action came after its biggest competitors, Woolworths and Coles, were also accused of serial underpayments in Federal Court – the FWO sued the supermarket giants in June over setting up payment structures to avoid paying workers overtime.
To close “loopholes” in the system, the government introduced the Fair Work Legislation Amendment (Closing Loopholes No. 2) Bill 2023 in September to criminalise wage theft and reform casual employment, the gig economy and labour hire laws.
The bill was then split in two in a crossbench deal on the final day of Parliament to pass its less-contentious provisions on labour hire and union delegate rights.
While unions strongly supported the changes, the corporate sector was not so taken, with key business and employer groups coming out with scathing rebukes.
Council of Small Business Organisations Australia CEO Luke Achterstraat criticised the complexity of the behemoth 800-page omnibus. “The new definition of casuals is three pages long and comprises 15 different tests. You shouldn’t need a PhD in law to know how to hire a casual worker,” he said.
National employer association Ai Group CEO Innes Willox called the changes “unworkable”.
“Make no mistake, the bill will hurt industry, undermine productivity and result in fewer job opportunities as well as higher costs that will potentially be passed on to consumers,” he said.
With the bill’s remaining provisions on casual work still in Parliament, the ATO also released guidance on differentiating between employees and contractors in December.
TR 2023/4 confirmed the ATO would follow the High Court’s approach to determining whether a worker was an employee under the Taxation Administration Act.
It said it was a question of fact and should be determined by reference to an objective assessment of the relationship, legal rights and obligations between an employer and employee, a departure from the old “multi-factorial” analysis of parties’ conduct when determining worker classification.
However, instead of providing clarity, some commentators believed the ruling added a further wrinkle to the employment law landscape.
This is because it went in direct contrast to the approach contained in Closing Loopholes, which proposed to reinstate the old multi-factorial test.
According to employment lawyer Nicholas Parkinson, that would lead to an “incongruous position” where the Fair Work Act, FWO, courts and tribunals would use one definition of employment, and the ATO in ensuring compliance with tax obligations would use another.
A senate inquiry into the bill is due to report next month and the government will look to pass the remaining provisions on casual and gig economy worker protections in the coming months.
In the meantime, the FWO will almost certainly have its work cut out again in 2024 as businesses and authorities attempt to navigate a system in a constant state of flux.
Christine Chen
11 January 2024
accountantsdaily.com.au
ATO warns advisers against suspect R&D tax claims
Spending by associated entities or activities conducted overseas will be subject to increased scrutiny, the Tax Office says.
.
The ATO has released two taxpayer alerts warning about incorrect R&D tax offset claims involving spending by associated entities or activities conducted overseas for foreign-related entities.
Taxpayer Alerts TA 2023/4 and TA 2023/5 said taxpayers and advisers using either arrangement would be subject to increased scrutiny and possible penalties if the R&D tax incentives were being wrongly applied.
In a guidance update, the ATO said:
“We’re concerned these arrangements are being used to:
- claim the R&D tax offset in situations where it would not otherwise be available, either at all or in the income year claimed by the R&D entity.
- artificially increase the amount of the R&D tax offset claimed.”
Regarding TA 2023/4, “Research and development activities delivered by associated entities”, the ATO said: “We’ve identified arrangements where an entity incorrectly claims the R&D tax offset for expenditure incurred under an agreement with an associated entity who conducts those activities.”
Arrangements of concern included those where a “service provider”, which was usually an entity that conducted a group’s trading and research activities, operated as a contractor to provide R&D for the entity claiming the incentive. The service provider would not normally be entitled to claim the incentive and the body making the tax claim had little or no activity other than the specific R&D arrangements.
“In substance and effect, the refundable tax offset is the R&D entity’s only receipt and the only amount used to service the R&D entity’s payment obligations to the service provider,” the alert said.
Taxpayer Alert TA 2023/5, “Research and development activities conducted overseas for foreign related entities”, similarly outlines ATO concerns about arrangements where Australian entities claim the R&D tax offset for expenditure incurred on R&D activities conducted overseas.
“Arrangements of concern include where an R&D entity has purported that R&D activities were conducted for its own benefit, but those activities were instead conducted for a foreign entity that is ‘connected with’, or is an ‘affiliate’, of the R&D entity,” it said.
“We are concerned that R&D entities do not qualify for an R&D tax offset under Division 355 of the ITAA 1997 for expenditure incurred by them on R&D activities conducted overseas as the R&D activities were:
- not conducted for the R&D entity, or
- conducted to a significant extent for the foreign related entity, and that entity does not satisfy the statutory conditions for eligible R&D activities.”
The ATO said penalties could apply to participants in these types of arrangements although they might be “significantly reduced if the amendment request is treated as a voluntary disclosure”.
Philip King
18 December 2023
accountantsdaily.com.au
What is a Commercial Lease?
If you are an owner of commercial property, it is important to understand commercial leases well.

.
A commercial lease is a document that sets out the rights and obligations of an owner of commercial property (the landlord or lessor) and a third party that has agreed to occupy the property (the tenant or lessee). Depending on the circumstances, commercial leases come in different forms. In this article, we explore what a commercial lease is and the types of leases you may encounter, including:
- retail leases;
- commercial leases;
- licences; and
- subleases.
Retail Leases
Retail leases are used wholly or predominantly for retail shop business. Typically, this is the case whether or not the shop is within a shopping centre.
In Australia, the legislation which governs retail leases differs from state to state. For example, in New South Wales, the Retail Leases Act 1994 is the relevant legislation that governs retail leases. However, there are several exceptions to the application of the legislation, including:
- retail shops over 1000 square metres;
- shops operated within a cinema, bowling alley or skating rink;
- shops in an office tower that form part of a retail shopping centre; and
- leases for over 25 years (including any options to renew).
A distinguishing feature of a retail and commercial lease is that the retail legislation imposes obligations on the landlord and provides rights and protections to tenants who lease retail premises.
It is important to determine whether the relevant retail legislation in your state or territory applies to the premises early. This will impact:
- the requirements you must fulfil before entering the lease;
- the contents of the lease; or
- what will occurs after entering the lease.
Commercial Leases
A commercial lease is for a commercial space, such as a factory or office space. Concerning rent, you can prepare commercial leases on many bases. For example, you could calculate rent on:
- base rent with no outgoings (otherwise known as a gross lease);
- base rent plus outgoings;
- base rent plus a percentage of sales (referred to as turnover rent); or
- rent review as market review, a fixed percentage or based on CPI measure.
Ultimately, your commercial lease may be based on any of the above or a combination. Although, this will depend upon your commercial negotiations with the landlord. The bargaining positions of the landlord and tenant can determine the rental terms of the commercial lease, including:
- their size;
- demand for the premises; and
- strength of the market.
It is important to determine whether the relevant retail legislation in your state or territory applies to the premises early. This will impact:
- the requirements you must fulfil before entering the lease;
- the contents of the lease; or
- what will occurs after entering the lease.
Licences
A licence is, at law, a right of use. This differs from a lease that provides a legal (and usually registrable) right of registration. A licence of premises is usually best for short-term leasing periods. Given the short-term length of the licence agreement, it is less common for the licence to include provisions for the amount of rent to be adjusted, requiring the tenant to pay outgoings in addition to rent or for the tenant to undertake any repairs or maintenance.
However, given the short-term nature, licences also only sometimes include an option to renew the term. As such, it is more suitable for businesses that would like to operate only for a short period. However, suppose you consider operating the premises for a longer period of time. In that case, it may be in your interest to enter into a short term lease instead, with options to renew. For instance, consider a one-year lease.
Another distinguishing feature of a licence is that the occupants are not usually given ‘exclusive possession’. This will vary from licence to licence but often means that the licensor of the premises has greater rights to enter into the Premises at any time.
Subleases
A sub-lease is an agreement between the tenant and a third party (the sub-lessee) to assume the tenants obligations under the lease with the landlord. Further, it is documented as a new agreement between the tenant and third party where the third party becomes a sub-tenant under a sublease agreement. Moreover, this may or may not be on the same terms as the lease between the landlord and tenant. Typically, a lessor must consent to a sublease before it can be entered into.
Additionally, a tenant cannot enter a lease via a sublease unless the lease permits it and the landlord consents. Provisions under a lease that allow for sublease with the landlord’s consent are attractive to a tenant as they allow the tenant to have a level of flexibility to grant occupation rights to another party (for the whole or a portion of the property). Therefore, the tenant can downsize its operations before the expiry of the lease term.
However, it is essential to note that entering into a sublease does not always mean that the tenant has no future obligations to the landlord. Hence, you should always seek legal advice when entering into such an arrangement.
Key Takeaways
As a landlord or tenant, it is crucial to understand commercial leases well. Indeed, they can come in various forms, depending upon the circumstances. For instance, some types of commercial leases include:
- retail leases;
- commercial leases;
- licences; and
- subleases.
Hanin Naji – Lawyer
legalvision.com.au
Types of small business benchmarks
There are different types of small business benchmarks that help compare your business' performance.
.
Performance benchmarks
Performance benchmarks are financial ranges for your industry. They help you work out how you compare to other businesses and decide if you need to make any changes. Performance benchmarks apply to 100 industries and input benchmarks apply to domestic trade work.
Performance benchmarks include:
- tax return benchmark ranges – from information provided by businesses on their tax returns
- activity statement benchmark ranges – from information provided by businesses using complete financial year activity statement data. These benchmarks have not been produced since 1 July 2017 with the introduction of Simpler BAS.
Tax return benchmark ranges include:
- cost of sales to turnover (excluding labour)
- total expenses to turnover
- labour to turnover
- rent to turnover
- motor vehicle expenses to turnover.
Activity statement benchmark ranges (before 1 July 2017) included:
- non-capital purchases to total sales
- GST-free sales to total sales.
Key benchmark range
Use the key benchmark range when you compare your business's performance to others in your industry.
We use this range to protect honest businesses. We may also use it to determine how much tax a business should have paid when there are insufficient or no records available. This is the most accurate when predicting business turnover.
Search for your industry key benchmark range by:
- alphabetical order – Benchmarks A-Z
- industry grouping – Benchmarks by industry
If your industry isn’t represented in our small business benchmarks, use the industry benchmarks information in taxation statistics.
Input benchmarks
Input benchmarks show an expected range of income for tradespeople based on the labour and materials they use to undertake domestic projects.
We developed them using information from industry participants and trade associations.
Input benchmarks help you to:
- find your industry's benchmark range
- estimate your turnover based on labour and materials used
- ensure your records accurately reflect your income.
ATO
ato.gov.au
Most Expensive Wars In History
Check out the most most expensive wars throughout history
.
.
.
.
.
.
.
.
.
.
.
Is My Organisation Exempt From the Spam Act?
Today, data is an important product for all types of organisations.
.
Businesses often rely on email marketing and promotions to provide their customers with information about new products or to reach out to new customers and expand their reach. Due to the increasing value of data and personal information, the Spam Act 2003 (Cth) (Spam Act) restricts spam with the aim to protect individuals from aggressive marketing strategies. Australian Communications and Media Authority (ACMA) monitors compliance with the Spam Act. This article considers which organisations are exempt from the Spam Act.
What is the Spam Act and When Does It Apply?
The Spam Act covers all commercial electronic messages sent by businesses that are not otherwise exempt. Commercial electronic messages may include messages whose purpose is to advertise:
- the supply of goods and/or services;
- an interest in land;
- a supplier of land; or
- a business or investment opportunity.
Additionally, the message must be sent using an internet carriage service to an email account or an instant messaging account. This includes social media accounts and text messages.
The law takes a holistic approach when determining if a message is a commercial electronic message. It looks at the content of the message, how the message presents itself, and any links the message includes. The most common forms of commercial electronic messages are email marketing campaigns.
It is important to note that even if your business is not required to comply with Australian privacy laws, it will still be required to comply with the Spam Act. That is, there is no minimum threshold for businesses to whom the Spam Act applies.
Exemptions
As mentioned above, not every organisation is restricted from sending commercial electronic messages. The Spam Act permits the sending of ‘designated commercial electronic messages’, which are messages sent by:
- government bodies;
- registered political parties;
- registered charities; and
- educational institutions.
However, there is a condition that such entities can only send messages related to their own goods and/or services.
Similarly, businesses that are not any of the entities listed above may send designated commercial electronic messages if the message consists of no more than factual information. However, you should use caution when sending a designated commercial electronic message. This is because anything in the message that could be considered marketing or promotional material means the entire message is commercial. Consequently, the message is subject to the restrictions set out below. An example of this may be a link to a recent promotion your business is offering in the footer of the email.
When Can a Business That Is Not Exempt Send Marketing Material?
We have all received marketing emails before, so in what circumstances can a business send commercial electronic messages? The Spam Act sets out three requirements that businesses have to follow when sending marketing or promotional material to anyone.
Get Permission From the Recipient
The most essential requirement is to have consent from the recipient before sending them marketing or promotional material. Consent may be express, for instance, if the recipient opts in to receive your direct marketing emails. Alternatively, it may be inferred. You may infer permission to send the message if the recipient has knowingly given their contact information (such as when signing up for an account with your business). Likewise, it must be reasonable to believe that the recipient would expect to receive the message from your business.
Inferred consent cannot be taken if the recipient has made a one-off purchase from your business.
Identify Yourself as the Sender
Your message must accurately identify your business details, including the correct contact details for you and your business.
Make It Easy to Unsubscribe
Every commercial message must include an easy-to-use and free, unsubscribe facility. Any request must be actioned within five working days, although most facilities have immediate unsubscribe facilities.
Tim Jones – Lawyer
legalvision.com.au
Annual wage growth surges to 14-year high of 4%
UPDATED: Hardworking Australians deserve higher wages, the Treasurer says.
.
A 4.0 per cent surge in wages for the year to September – the fastest rate for 14 years – and a record 1.3 per cent spurt for the quarter was the welcome result of government policy, the Treasurer said yesterday.
The ABS said the quarterly growth figure was the highest in the 26-year history of the Wage Price Index and head of prices statistics Michelle Marquardt said the result came down to a combination of factors.
“In the private sector, higher growth was mainly driven by the Fair Work Commission’s annual wage review decision, the application of the Aged Care Work Value case, labour market pressure and CPI rises being factored into wage and salary review decisions,” she said.
“Many public sector jobs were affected by the ending of state wage caps and the resolution of wage negotiations. This resulted in initial or backdated increases being paid for jobs covered by the newly approved enterprise agreements.”
Treasurer Jim Chalmers said Australians deserved higher wages “and that’s what we’re delivering”.
“We believe that solid, sustainable wages growth is part of the solution to the cost‑of‑living challenges Australians face, not part of the problem,” he said.
“Stronger wages growth is a result of the Albanese Labor government’s policies to lift wages for workers including our support for record increases to the minimum wage, a 5.75 per cent pay rise for workers on awards, the highest ever pay rise for aged care workers, our big investments in education and training, and significant investments in new industries to create secure, well‑paid jobs.”
“We seek wages growth that is strong and sustainable, and an economy that is more productive, competitive and inclusive.”
The public sector recorded a 0.9 per cent wage increase for the quarter and annual growth of 3.5 per cent – quicker than at any time since June 2011.
But wage growth in the private sector was racier still, with a 1.4 per cent quarterly increase and annual rate of 4.2 per cent, a mark unsurpassed since December 2008.
Ms Marquardt said two elements that drove the results were the proportion of jobs that had a rise and the size of the increases.
“In original terms, across all public and private sector jobs that had a wage movement in the September quarter, the average change was a 5.4 per cent increase, up from 4.0 per cent in September quarter 2022,” she said.
“The growth was mostly driven by increases to wages in the private sector. Almost half (49 per cent) of all private sector jobs recorded a movement with the average increase being around 5.8 per cent.
“This compared to the public sector where 34 per cent of jobs recorded an average pay rise of 3.3 per cent.”
Accommodation and food services set the pace at 3.2 per cent for the quarter and 5.5 per cent for the year, the ABS said, with some hospitality jobs getting two award increases over the past 12 months.
“Healthcare and social assistance also saw significant wage growth of 3.1 per cent for the quarter and 4.9 per cent annually. Many jobs in this industry have wages set by awards or enterprise agreements with scheduled increases linked to the Fair Work Commission’s annual wage review 2022-23 decision and higher wage provisions for aged care workers.”
Trailing the pack was the mining industry, with quarterly growth of 0.8 per cent, and finance and insurance, with an annual growth of 3.1 per cent.
Philip King
16 November 2023
accountantsdaily.com.au
Average refund plummets by $580, total payout down $5.4bn
UPDATED: The end of LMITO and revised WFH rules have taken billions out of refunds, ATO figures reveal.
.
Tax refunds have plunged by an average of more than $580 this year for the millions who filed their returns by the October 31 deadline, ATO figures reveal.
Data supplied to Accountants Daily revealed 10.5 million taxpayers put in returns by last month’s date, up from 10.2 million last year, with half of those self-prepared and the other half done by tax agents.
But a combination of changes this year, from the end of the low and middle income tax offset – the so-called LMITO – to revised rules about work-from-home expenses have taken a big chunk out of refunds.
The LMITO had provided eligible individuals earning up to $126,000 a tax offset of up to $1,500 when they lodged their returns while the ATO made strict record-keeping a condition of WFH claims from March in a move that blindsided many taxpayers.
This year’s 10.5 million taxpayers had been paid total refunds of 18.2 billion, the ATO disclosed, equivalent to an average of $1,733 each.
But last year’s 10.2 million taxpayers received a whopping $23.6 billion, or an average of $2,314 each.
The difference adds up to an average of $581 for every taxpayer.
An ATO spokesperson said that figure failed to account for taxpayers who received bills for amounts owed or ended the year all-square, and for those who actually received refunds the difference would be less.
Director of tax communications at H&R Block, Mark Chapman, who warned about the consequences of LMITO ending and the cost of the WFH changes earlier this year, said the decline was in line with his expectations.
“The absence of LMITO was inevitably going to lead to smaller refunds and the change to working-from-home deductions has also been a factor,” he said.
“The ATO were adamant that it wasn’t about reducing the size of refunds but it clearly has been. People are finding it harder to claim the deductions that they claimed last year so basically it’s job done – their refunds have gone down.”
He said the average refund figure concealed different results depending on how much each taxpayer earned.
“For anybody who was earning more than $126,000, they won't have been impacted by the abolition of LMITO at all. So there must be some other factor that led to a reduction in their refunds.”
“For people who were earning less than 126,000, a large part of it might have been the loss of LMITO, which gave them a refund of between $675 and $1,500.
“It all evens out, so $581 seems about right.”
He said the revised WFH rules had failed to register with many taxpayers, and that was an additional factor.
“People just didn't know this was going to happen. When this change was first announced at the start of this year people weren't paying attention. Their minds weren't on their tax affairs so it just went over their heads – and that was potentially catastrophic in terms of their claims.”
The revised rules required strict record-keeping of actual hours worked from 1 March to access a new fixed rate method after the short-cut method, introduced during the pandemic, was abolished for FY23.
Mr Chapman said by 1 July, it was too late for many to take the necessary steps.
However, he said the WFH changes had driven some taxpayers into H&R Block to try to maximise their refunds in other ways.
“They basically want to try and make up any difference by claiming all of the other deductions that they may not have previously had the knowledge to have to have claimed. So it's actually been useful for our business.”
Philip King
13 November 2023
accountantsdaily.com.au
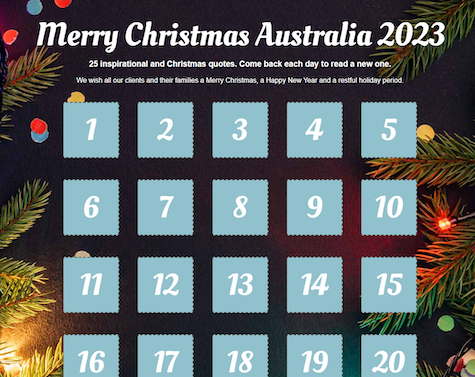
A 2023 Advent Calendar for our clients
Come back each day and click on the next date for more inspirational and Christmas quotes.
The Christmas and New Year holiday period is upon us again and we hope all our clients have a chance to relax and recover from a pretty torrid twelve months. Our Advent Calendar will help. Each day come back and read some of the inspirational notes it includes. Wishing you, your families and your colleagues a great holiday and a prosperous 2024.
(Please click on the image to open the Advent Calendar and then click on a date)
Record low invoice values ‘reveal inflation sting’
The latest CreditorWatch data shows small businesses are being hardest hit by rising prices and interest rates.
.
The average value of invoices has dropped by a third in the past 12 months and external administrations are up 81 per cent, according to the latest CreditorWatch Business Risk Index.
Its October data revealed the lowest average invoice value since the credit bureau began tracking the figure in January 2015, and said it signalled a drop in forward orders which could cause a ripple effect down the supply chain.
It said B2B trade payment defaults saw a slight improvement from September but are now consistently above pre-pandemic levels after rising on a trend basis since the cash rate began its upward climb.
“Businesses are now forced to direct more of their cash towards loan repayments and at the same time continue to grapple with unavoidable running costs that continue to rise, such as electricity, gas, fuel and insurance,” it said.
“In some cases, this is resulting in insufficient cash to pay all suppliers each month. It tends to be the smaller, non-essential suppliers who are reporting trade payment defaults.”
CreditorWatch chief executive Patrick Coghlan said the RBA’s attempts to curb inflation with interest rate increases were hitting businesses hard as consumers curtailed spending.
“Consumer demand is one of the key drivers of the economy and that is coming to a grinding halt as cost-of-living pressures bite,” he said.
“Costs of rents, electricity and fuel are all still very high despite the RBA’s best attempts to drive down inflation. Mortgage holders are suffering from increased loan repayments as well.”
The drop in the average value of invoices and the increase in B2B payment defaults gave a very clear picture of what businesses are going through at the moment, he said, adding that the drop in order values meant revenues and margins were also being squeezed through inflation.
“That is causing an increase in the number of businesses that are unable to pay their invoices to suppliers – and that is a real worry because those defaults greatly increase the chance that a business will not survive into the future,” he said.
“All the data is pointing to another challenging Christmas trading period so it is prudent for businesses to follow up on outstanding debts before then.”
External administrations also continue to rise with an 81 per cent year-on-year increase to October.
CreditorWatch chief economist Anneke Thompson said the increase in interest rates was impacting smaller businesses the most.
“SMEs are more susceptible to changes in demand than bigger businesses and, on the personal side, many owners will have rising home-loan repayments to service, which may involve them having to remove more money from their businesses and reduce orders from suppliers where possible as a result,” said Ms Thompson.
CreditorWatch predicted the business failure rate would significantly increase from the current 4.21 per cent up to 5.78 per cent over the next 12 months.
“This is in part because we are coming off a period where there has been an unusually low rate of business failures, but also the steep decline in consumer spending on discretionary items, which will impact many marginal smaller businesses,” the credit agency said.
“The ATO is also pursuing unpaid tax with more vigour, and there are many businesses that still owe significant amounts of GST following the end of COVID-19 payment ‘holidays’.”
.
Miranda Brownlee
16 November 2023
accountantsdaily.com.au
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...
Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























