
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
Illegal access nets $637 million
The ATO has found $637 million of superannuation savings has left the system due to illegal early access carried out through SMSFs.
.
The figures were released by the regulator today at the SMSF Association National Conference 2024 in Brisbane, where ATO superannuation and employer obligations deputy commissioner Emma Rosenzweig provided the first report on an illegal early access estimate project revealed late last year.
“I’m here today to announce for the first time that we have found for the 2019/20 year an estimated $381 million of super has been illegally withdrawn by trustees of SMSFs,” Rosenzweig said.
“This figure would have been half-a-billion dollars if we hadn’t protected over $125 million leaving the system as part of our new registrant program.
“In the 2020/21 year, we estimate over $256 million of super has been illegally accessed, with almost $170 million additional that was protected at registration.”
“These are large amounts of money and they don’t include prohibited loans across those two years, so a total of $637 million of superannuation savings has left the system illegally through SMSFs.”
She added prohibited loans were also of concern and in each of the two financial years mentioned, SMSFs entered into more than $200 million in prohibited loans each year, but 75 per cent were repaid.
Newly established SMSFs were more likely to engage in illegal early access or prohibited loans compared to established funds and around two-thirds of the $930 million involved in illegal access or loans over the two years came from people entering the system with no genuine intention to run a fund, she noted.
She said the ATO formed its estimate using audit reports and examining funds that had yet to lodge an annual return and would continue to do so each year as the regulator remained concerned illegal early access was ongoing.
“We looked at all auditor contravention reports of funds that have lodged in those two years where those reports had noted a contravention that could amount to illegal early access and then for those SMSFs that have not lodged, we undertook a random inquiry program and a statistically valid sample,” she said.
“Through the results of both of those we have come up with this estimate across the entire population.
“So will we be doing it every year? Yes.
“We do see already in 2021/22 there are indicators that suggest that illegal early access is still prevalent. We continue to see many new trustees entering into the system with the sole intent of raiding their retirement savings, sometimes facilitated by promoters charging a large fee.”
Jason Spits
February 21, 2024
smsmagazine.com.au
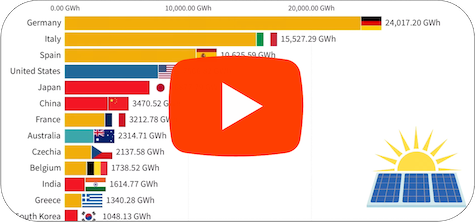
Countries producing the most solar power by gigawatt hours
Check out the countries that produce the most solar power.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
Sharing economy reporting regime for platform operators
Individuals participating in the sharing economy should be aware that transactions for supplying taxi travel/ride sourcing and short-term accommodation are now required to be reported under the sharing economy reporting regime (SERR).
.
That reporting requirement will be expanded for 2024-25 year.
Generally, all operators of electronic distribution 2023–2024 income year must report transactions made through their platform.
However, from 1 July 2024, the SERR will apply to all other reportable transactions of electronic distribution platforms operators, including hiring of assets (consisting of hire of personal assets, storage or business space), food delivery and professional performing tasks and activities will need to be reported.
Why employee v contractor comes down to fine print
The task of worker classification has been a long-running point of contention but the Commissioner’s response to recent court cases suggests a written contract is king.
.
The classification of an individual as an employee or contractor for PAYG and superannuation obligations has been a long-running point of contention.
With the High Court decisions of Jamsek and Personnel Contracting changing the determination process, together with the recent case of JMC Pty Ltd v Commissioner of Taxation potentially expanding the role of the contractor, the question before us now is: where are we with the Commissioner’s response?
Background
In 2022, Jamsek and Personal Contracting determined that the terms and conditions of a written contract between parties were what was relevant when deciding whether an individual providing services is characterised as an employee or a contractor.
As a result, a written agreement between parties contains the determining factors in the employee v contractor issue (control, risk, integration of the individual into the principal’s business).
Provided the agreement is not a sham or has not been varied, it is not necessary for further facts and/or evidence to be gathered or considered by the parties in determining the outcome.
JMC Pty Ltd v Commissioner of Taxation [2023]
JMC was a superannuation case concerning whether sections 12(1) and 12(3) of the Superannuation Guarantee Administration Act 1992 applied to a contract primarily for labour.
The decision is important because including a term that allows for delegating or transferring someone's services in the written agreement will likely lead to them being characterised as a contractor instead of an employee.
The Full Federal Court clearly stated (paragraph 89):
“The right bestowed upon Mr Harrison to subcontract or assign the performance of his teaching services, subject to written consent, was a real and substantial right which was inconsistent with an employment relationship between him and JMC.”
This decision expands the potential for individuals to be engaged as contractors where their agreements have such a delegation authority, regardless of whether the principal approves the delegation. The fact that it exists is the primary issue.
This means that a principal may directly hire an individual for services without the need for any intermediary entity.
The Commissioner’s position
Taxation ruling TR 2023/4 outlines the Commissioner’s position.
It starts in a somewhat pedestrian fashion on the question “who is an employee” for PAYG, and reemphasises that it will be approached in a “holistic” manner.
But the key points in the ruling with respect to the question of employee v contractor are as follows:
- The delegation authority
The Commissioner accepts the position that a right to delegate or assign services, as evidenced in a written agreement, will indicate that the individual is not an employee.
However, there will be parameters in the contractual terms:
- Not be limited in scope (that is, the worker can delegate, subcontract, or assign the entirety of their work to another, as opposed to only discrete tasks)
- Not be a sham, and
- Be legally capable of being exercised.
The Commissioner goes on to state: “Whether the worker is, however, an independent contractor will depend upon an examination of the totality of the legal rights and obligations between the parties.”
It is unclear what the Commissioner means by this. It would appear without doubt that in JMC the weighting to the question of delegation was the substantial factor in favour of characterising an individual as a contractor (independent or otherwise).
- The comprehensive written agreement
A comprehensive written agreement that governs the entire relationship between the parties will be the evidentiary document in considering the employee and contractor divide.
The Commissioner states:
“Where the worker and the engaging entity have comprehensively committed the terms of their relationship to a written contract and the validity of that contract has not been challenged as a sham, nor have the terms of the contract otherwise been varied, waived, discharged or the subject of an estoppel or any equitable, legal or statutory right or remedy, it is the legal rights and obligations in the contract alone that are relevant in determining whether the worker is an employee of an engaging entity.”
Notably, the Commissioner accepts that “evidence of how the contract was performed, including subsequent conduct and work practices, cannot be considered for determining the nature of the legal relationship between the parties”.
Consistent with this, the respective practical compliance guideline (PCG 2023/2) says that there will be low or very low risk outcomes where parties have a written contract expressing the employee v contractor outcome.
- The requirement for written advice
PCG 2023/2 also indicates that each party must commit to and understand the worker classification in their agreement.
The party relying on this classification will fall within the ‘”no risk” or “very low risk” category if they have “obtained specific advice confirming the classification was correct”.
The specific advice does not need to be in writing, but if it is, that will be given greater weighting in the Commissioner’s determination.
Takeaways
The employee v contractor classification is not straightforward.
The High Court’s direction has limited the question to the written agreement (where one is in place). However, issues and disputes between parties regularly arise for “handshake” agreements between friends when the relationship subsequently sours.
The lesson in such matters is simply to get everything in writing.
Phillip London
16 February 2024
accountantsdaily.com.au
Australian Taxation Office (ATO) shifting to firmer debt collection activity
The ATO has flagged a return to more aggressive debt collection actions after seeing a trend of profitable businesses that have the capacity to pay their tax debts but are actively choosing not to do so.
.
The ATO should not be considered as an unsecured lender last in line, because when they lose patience, they hit hard.
Taxed debts include not only income tax, but also unremitted GST and unpaid PAYG withholding, as well as super guarantee charges.
In general, if taxpayers do not pay their tax by the due date or engage with the ATO by the due date to work out a payment plan, general interest charge (GIC) will be applied to any unpaid amounts. GIC is automatically calculated on a daily compounding basis on the amount outstanding and added to taxpayers’ accounts periodically.
What Drives Your Business Growth and Profits?
Every business owner wants to grow their business and their profits.
.
While there’s no secret formula or recipe, the fact is, business growth and improved profitability are outcomes achieved as a result of processes including marketing, your expertise, customer service and your team’s performance.Every business owner wants to grow their business and their profits. While there’s no secret formula or recipe, the fact is, business growth and improved profitability are outcomes achieved as a result of processes including marketing, your expertise, customer service and your team’s performance.
Let’s examine some of the key drivers of growth and profitability.
- Planning – where do you see your business going in the future? What level of profit and growth are you targeting for next year? The definition of insanity in business is doing things the same way and expecting different results. Without a plan to achieve your targets you are just hoping all the moving parts of your business sync together. Unfortunately, hope is not a strategy that delivers growth.
What is your vision for the business and how do you plan to get there? Without a roadmap all roads lead to nowhere. Having a business plan including financial forecasts is really the start of the process because it should identify what resources you need, the equipment and finance requirements. Will you launch new products and services? To achieve the forecast growth, what level of staff will you need?
Another part of the planning process is to complete a SWOT Analysis to ascertain your business Strengths, Weaknesses, Opportunities and Threats. Nobody saw COVID-19 coming but pandemics and snap lockdowns are part of the landscape and you need a contingency plan to deal with such events. As they say, Failing to Prepare is Preparing to Fail.
- Technology has been a game changer in many industries and the rate of change continues to accelerate, just look at what AI is doing and going to do in the future. Before the pandemic arrived a lot of business owners were contemplating some sort of digital transformation to keep up with their competitors and deliver a better customer experience. When COVID-19 arrived, remote working became an urgent priority to keep staff working. Businesses had to invest in technology to help staff transition from office-based to home-based employment and technology that was once considered a luxury became a necessity.
There’s been a massive shift in our daily business habits with face-to-face meetings replaced by video calls on platforms like Zoom, Google Meet, and Microsoft Teams. Going forward, these platforms may well become the default communication method for both internal and external meetings. Travel time has been slashed also but businesses are looking to get staff back into the office. Significant change is afoot again.
Think about what technology you need to speed up your processes, improve productivity, reduce costs and produce better products and services. The right software (local or in the cloud) can save time, help manage your inventory, reduce waste, and generate repeat business with service reminders. It can also automate your marketing efforts. Most importantly, the right digital tools and resources let you keep your finger on the pulse of the business and monitor all the key financial data.
- Marketing – Recent years have seen a significant shift in shopping habits away from retail brick-and-mortar sites such as shopping strips and centres to spending online. The rise of Amazon is ample evidence of this change. With consumers confined to their homes during COVID they became far more familiar with, and keener on, the convenience of shopping online. A trend that has continued after the pandemic. E-commerce sales exploded and this massive shift to online sales is expected to stay for a long time.
To make the most of this shift in consumer behaviour it's time to review your website and, where appropriate, make sure you have an e-commerce store to satisfy customer demand. There are quite a few examples where a business has moved entirely from a retail shop to a totally online model.
Increasing traffic to your site may be as simple as utilising the blog section of your website more effectively. Chances are there is already a blog or news section on your website but nobody is posting anything, or only rarely. If you struggle for what to write in your blog section, head to a question and answer site such as Whirlpool or Quora and find questions related to your industry, product or service and use that question as the title of your blog post and answer the question. Visitors to your site appreciate this content and it will increase the SEO attributes of your website. SEO is important when it comes to Internet searches.
Engaging with your customers in this way and, as well as using social media channels, is no longer optional with your prospects and customers living online. It’s fair to say, for the majority of businesses, your marketing could be the difference between Doom, Gloom and Boom.
- Team – In Michael Gerber’s book, The EMyth Revisited, a key message for business owners was the need to ‘work on the business, not just in the business’. This message should resonate with every business owner and you need to create a business that works independently of you. The purpose of your life is not to serve your business, it’s for the business to serve your life.
Sounds good and easy in theory and the key is finding the right people to run the operational side of the business to free you up. Experienced and trained people who can follow your systems and procedures allow you to delegate tasks you don’t have to do. Rather than manning the sales desk, phones or warehouse you can spend time on the key business drivers like marketing. Wages are often the biggest expense in a business for a reason and their performance can have a massive impact on your growth and profitability. Leadership usually includes managing the team and innovating – that means providing the right tools so the team can perform their tasks in efficiently.
Running a business remains a constant work in progress. To drive better financial outcomes you need to explore ways to continuously improve your business systems and processes. This necessitates planning, the implementation of technology and, today, the adoption of digital marketing techniques. You also need the support of your staff and small improvements can have a compounding effect.
Ultimately the value of a business is linked to factors like revenue, profits and growth rate. It makes a lot of sense to focus on these areas and if you want to discuss the key profit and growth drivers in your business we invite you to contact us today.
ATO’s hands tied with scrapping on-hold debts, expert says
The Tax Office lacks power under current laws to do anything about the wildly unpopular scheme despite plans to review its approach, according to a UNSW professor.
.
Relief for taxpayers with on-hold debts resurrected by the ATO is impossible to achieve without government intervention due to the Commissioner’s inflexible powers, according to one expert.
The ATO announced on Thursday it paused activities around re-raising liabilities previously deemed “uneconomical to pursue” after backlash from the community over the program’s fairness and transparency.
But UNSW associate professor Ann Kayis-Kumar said individuals with on-hold debts hoping for a blank slate would be disappointed because “the ATO’s hands are tied” with no power to write the amounts off.
“The ATO’s in a tricky position. Being responsible for collections and compliance, it needs to walk that delicate balance between collection but also not disproportionately affecting the most disadvantaged in our community,” she said.
“But that raises the question of the discretion available to the ATO.”
Only the finance minister had the power to permanently write off debts owed to the government, she said.
While the ATO could release certain taxpayers’ debts under “serious hardship” provisions contained in the Income Tax Assessment Act, in practice they were ineffective due to being “so outdated and drafted in such a counterintuitive way”.
For example, the current provisions meant the ATO would be less likely to grant hardship relief to taxpayers with more debt.
“That just does not square with reality,” she said. “We need a legislative fix and it really can't be overstated how important that is.”
In the ATO’s statement released yesterday, it announced it would pause the on-hold debts program due to the “frustration” and “concern” caused to the community.
“The ATO has paused all action in relation to debts placed on hold prior to 2017 whilst we review and develop a pragmatic and sensible way forward that takes into account concerns raised by the community,” it said.
However, it said it had “no discretion under the law to waive these amounts and must use any future refund to reduce these debts”.
“In the past, the ATO has excluded some debts from being recovered from taxpayer refunds in this way through long-standing exclusionary criteria, such as for taxpayers on low incomes. However, the Australian Government Solicitor advised this was not in line with the law and so the ATO cannot continue this practice,” it said.
The announcement follows an earlier apology issued by the ATO in November for the “unnecessary distress” caused by its “public awareness campaign” that first alerted taxpayers to the debts a month earlier.
The campaign involved the sending of 200,000 letters to taxpayers and tax agents listing the sums without containing further details of their origins.
Internal documents obtained by The Guardian this week revealed the on-hold debts were the result of the ATO’s gradual removal of filters in its automated systems.
The planned removal of the final filter – debts placed on hold prior to 2017 – would have expanded the program to apply to $15 billion from 1.8 million entities, the documents said.
Ms Kayis-Kumar, who runs UNSW’s pro-bono Tax & Business Advisory Clinic, said on-hold debts disproportionately impacted financially vulnerable individuals without access to tax advice.
Tax agents also reported confusion and increased workloads in attempting to reconcile the debts.
But the community’s concerns could be addressed by giving the Commissioner a “general public policy ground of relief”, in addition to reworking the serious hardship provisions, she said.
A general discretion, as seen in other countries like the US, could allow the flexibility needed to scrap the on-hold debt program in line with public consensus.
“If we adopted something inspired by the public policy ground of relief in the US, the ATO would be able to exercise that discretion in situations like what we’re seeing here,” she said.
“You want decision-makers to be able to make decisions that are in line with community expectations.”
“If we want to see a wholescale improvement to the status quo, we need more reform.”
Christine Chen
23 February 2024
accountantsdaily.com.au
Small businesses may ‘collapse under strain of payday super’, IPA warns
Existing issues within the SG system must be rectified before the government proceeds with the new changes, the IPA says.
.
The Institute of Public Accountants has told the government that the implementation of payday super should not proceed without system improvements being made first.
In its pre-budget submission, the IPA said the introduction of payday super is a significant departure from the existing arrangements where the payment of employees’ salaries and wages is separate from the payment of their super entitlements.
“Over 60 per cent of employers pay their SG contributions quarterly, so payday super will inevitably be one of the most significant changes to the superannuation sector since compulsory super began,” the IPA said.
The association said the existing SG system has many issues that need to be addressed so that they are not dragged into the new regime.
“PDS should not proceed without system improvements addressing the current identified drawbacks, otherwise we will be introducing additional unnecessary complexity into the new regime,” it stated.
“The use of SuperStream, clearing houses, super choice/stapling and remittance processes need to be refined and streamlined to support the move to near real time payment of SG.”
The submission noted that the proposed policy changes will impact a wide range of legislative provisions, employers’ compliance requirements, the onboarding of employees with an employer, payment and reporting systems and processes, and services provided by intermediaries such as payroll providers and clearing houses and administration by the ATO.
“As a result, every aspect of the policy and its impact needs to be carefully considered,” the IPA said.
“Otherwise, there is a high likelihood of significant and unintended consequences that may affect employers’ ability to comply with the PDS model.”
The IPA said processes within the current system must be improved as there is only a small window for error corrections to accommodate the more frequent payment of SG.
Cash flow challenges for smaller businesses
The association also warned that more frequent SG contributions will lead to higher costs for employers by way of processing costs and higher transaction and servicing costs.
“In addition, the cashflow consequences for employers cannot be ignored especially for small and medium businesses,” it said.
“The move to immediate payment may pose challenges during the transitional period where the old and new regimes overlap, and some entities, in particular smaller employers, may collapse under this strain, as the proverbial ‘straw that broke the camel’s back’ syndrome.”
Penalty regime for SG must be overhauled
The IPA is also calling on the government to change the current penalty regime for the late payment and underpayment of SG.
“We consider that the Superannuation Guarantee Charge (SGC) model in its current form is overly complex and punitive,” the IPA said.
“The design of the SGC and the associated penalties deter self-rectification, and they therefore operate as a disincentive for employers to voluntarily report and rectify historical shortfalls,” it said.
One of the key concerns, the IPA said, is the draconian application of penalties that do not proportionately reflect the loss to employees or the ‘culpability’ of an employer who is in arrears.
“Late payment penalties under the existing penalty regime for failure to make SG payments on time need to be revised,” the submission said.
“PDS represents an overdue opportunity to completely redesign the SG penalty regime, to make it simplified and less punitive for employers trying to do the right thing. It must deter bad behaviour, whilst encouraging employers to quickly identify and fix errors.”
07 February 2024
Miranda Brownlee
accountingtimes.com.au
Wheat Production by Country
Check out the countries that produce the most wheat.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
Do you know how to recover debts?
Beginning the year with a clean financial slate can be pivotal to your business’ health.
.
Clearing debts early enhances creditworthiness, reduces stress, and fosters cash flow. It also facilitates strategic planning and growth, setting a solid foundation for a successful year ahead.
Here are five steps for recovering debt:
- Revisit your business terms and conditions: these should set out what steps the debtor must take to resolve payment-related disputes. Your lawyer can help review this for you.
- Follow up: remind the debtor via email or phone of the amount due.
- Send a letter of demand: request the debtor pay the outstanding balance.
- Negotiate with the debtor: before going to court, your lawyer will first try to resolve the dispute.
- Go to court: commence a legal claim against the debtor.
Some other actions:
Issue a Letter of Demand
The first stage in the debt collection process is usually to issue a letter of demand. This is a formal letter requesting payment of the debt. It sets out the specific amount owed and the period in which the debtor can make payment before you take further legal action.
Sometimes, issuing a letter of demand can result in the parties entering into negotiations concerning the debt payment. If parties reach an agreed payment plan, they can enter a binding settlement deed outlining the agreed proposal. This payment plan can be in full or instalments.
A formal letter can encourage a creditor to promptly take action. However, there is always some level of risk that a debtor may ignore the letter or raise a dispute concerning the debt.
Going to court
Going to court to recover a debt is intimidating, expensive and time-consuming. Therefore, you should think carefully before embarking on this final stage of the debt recovery process, especially if you have not exhausted your alternative options for getting paid. This article outlines what you should consider before filing your statement of claim.
- Consider Whether Your Debtor Can Pay
Even if you have a strong claim, if your debtor has no means to pay, you may get little from starting a lawsuit. Therefore, before commencing court proceedings, find out what you can about your debtor’s finances. For example, by checking their credit report and bankruptcy status.
- Determine if You Can Prove Your Claim
Every good lawyer will tell you that ‘litigation is never a sure thing’. The more evidence you have to support your claim, the stronger your position will be. While evidence in the form of written documents is always best, it is not essential. The court will determine a claim without written documentation on a ‘he said/she said’ basis.
Legal Vision
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























