
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
How to read a Balance Sheet
It’s common for small businesses to struggle when understanding their financial data. Cash flow needs and a Profit and Loss statement are analysed more often a business owner and so, understood better.
.
A Balance Sheet, on the other hand, is often a mystery. It is, still important to keep an eye on this data and the following will help.
When it comes to understanding a business, there are few financial statements more important than the balance sheet. The balance sheet offers critical insights into the health of a business that can be used by:
- Potential investors to decide whether to invest in a company
- Business owners to craft more effective organizational strategy
- Employees to adjust their processes to better reach shared organizational goals
Whether you’re a business owner, employee, or investor, understanding how to read and understand the information in a balance sheet is an essential financial accounting skill to have.
Here’s everything you need to know about understanding a balance sheet, including what it is, the information it contains, why it’s so important, and the underlying mechanics of how it works.
What Is a Balance Sheet?
A balance sheet is a financial document designed to communicate exactly how much a company or organization is worth—its so-called “book value.” The balance sheet achieves this by listing out and tallying up all of a company’s assets, liabilities, and owners’ equity as of a particular date.”
The Purpose of the Balance Sheet
A balance sheet provides a summary of a business at a given point in time. It’s a snapshot of a company’s financial position, and is broken down into assets, liabilities, and equity. Balance sheets serve two very different purposes depending on the audience reviewing them.
When a balance sheet is reviewed internally by a business leader, key stakeholder, or employee, it’s designed to give insight into whether a company is succeeding or failing. Based on this information, a company’s management can shift their policies and approach: doubling down on successes, correcting failures, and pivoting toward new opportunities.
When a balance sheet is reviewed externally, it’s designed to give insights into what resources are available to a business and how they were financed. Based on this information, potential investors, or example, can decide whether it would be wise to invest or not. Similarly, it’s possible to leverage the information in a balance sheet to calculate important metrics, such as liquidity, profitability, and debt-to-equity ratio.
External auditors, on the other hand, might use a balance sheet to ensure a company is complying with any reporting laws it’s subject to.
It’s important to remember that a balance sheet communicates information as of a specific date. By its very nature, a balance sheet is always based upon past data. While investors and stakeholders may use a balance sheet to predict future performance, past performance is no guarantee of future results.
The Balance Sheet Equation
The information found in a balance sheet will most often be organized according to the following equation: Assets = Liabilities + Owners’ Equity.
While this equation is the most common formula for balance sheets, it isn’t the only way of organizing the information. Here are other options you may encounter:
Owners’ Equity = Assets – Liabilities
Liabilities = Assets – Owners’ Equity
A balance sheet should always balance.
If a balance sheet doesn’t balance, it’s likely the document was prepared incorrectly. Typically, errors are due to incomplete or missing data, incorrectly entered transactions, errors in currency exchange rates or inventory levels, miscalculations of equity, or miscalculated depreciation or amortization.
Here’s a closer look at what's typically included in each of those categories of value: assets, liabilities, and owners’ equity.
1. Assets
An asset is defined as anything that is owned by a company and holds inherent, quantifiable value. A business could, if necessary, convert an asset into cash through a process known as liquidation. Assets are typically tallied as positives (+) in a balance sheet and broken down into two further categories: current assets and noncurrent assets.
Current assets typically include anything a company expects it will convert into cash within a year, such as:
- Cash and cash equivalents
- Prepaid expenses
- Inventory
- Marketable securities
- Accounts receivable
Noncurrent assets typically include long-term investments that aren’t expected to be converted into cash in the short term, such as:
- Land
- Patents
- Trademarks
- Brands
- Goodwill
- Intellectual property
- Equipment used to produce goods or perform services
Because companies invest in assets to fulfill their mission, you must develop an intuitive understanding of what they are. Without this knowledge, it can be challenging to understand the balance sheet and other financial documents that speak to a company’s health.
2. Liabilities
A liability is the opposite of an asset. While an asset is something a company owns, a liability is something it owes. Liabilities are financial and legal obligations to pay an amount of money to a debtor, which is why they’re typically tallied as negatives (-) in a balance sheet.
Just as assets are categorized as current or noncurrent, liabilities are also categorized as current liabilities or noncurrent liabilities.
Current liabilities typically refer to any liability due to a debtor within one year, which may include:
- Payroll expenses
- Rent payments
- Utility payments
- Debt financing
- Accounts payable
- Other accrued expenses
Noncurrent liabilities typically refer to any long-term obligations or debts which will not be due within one year, which might include:
- Leases
- Loans
- Bonds payable
- Provisions for superannuation
- Deferred tax liabilities
Liabilities may also include an obligation to provide goods or services in the future.
3. Owners’ Equity
Owners’ equity, also known as shareholders' equity, typically refers to anything that belongs to the owners of a business after any liabilities are accounted for.
If you were to add up all of the resources a business owns (the assets) and subtract all of the claims from third parties (the liabilities), the residual leftover is the owners’ equity.
Owners’ equity typically includes two key elements. The first is money, which is contributed to the business in the form of an investment in exchange for some degree of ownership (typically represented by shares). The second is earnings that the company generates over time and retains.
A Crucial Understanding
The information found in a company’s balance sheet is among some of the most important for a business leader, regulator, or potential investor to understand. Without this knowledge, it can be challenging to know whether a company is struggling or thriving, highlighting why learning how to read and understand a balance sheet is a crucial skill for anyone interested in business.
Acctweb
ATO warns businesses on looming TPAR deadline
The ATO is reminding businesses to lodge their tax payable payment annual report by 28 August after issuing around $9 million in penalties in the five years to 2023.
.
The Tax Office is urging businesses required to lodge a taxable payments annual report (TPAR) to do so by 28 August 2024.
Businesses may be required to lodge a TPAR if they pay contractors for certain services including building and construction; cleaning; courier and road freight; information technology (IT); or security, investigation, or surveillance.
It also applies to government entities that pay grants to people or organisations with an Australian Business Number (ABN).
The ATO warned businesses that it is an annual requirement to lodge a TPAR and that penalties may apply for failing to lodge one.
ATO Assistant Commissioner Tony Goding said the taxable payments reporting system (TPRS) ensures contractors providing certain services report all their income.
“This helps keep a level playing field by making sure all businesses pay their fair share of tax,” said Goding.
“TPAR data strengthens our ability to detect and deal with dishonest operators trying to gain an unfair advantage over the majority who do the right thing. It also protects billions of dollars in missing taxes each year, money that funds essential community services, like health, education and natural disaster management.”
In the 2023–24 financial year, Goding said the ATO provided visibility of more than $451 billion in gross TPAR payments from almost 177,000 businesses to almost 1.3 million contractors.
“In doing so, we have helped contractors complete their income tax returns through the pre-fill and transaction services report,” he said.
The ATO said that from 2019 to 2023, it has issued approximately $9 million in penalties to over 5,200 businesses not lodging their TPAR.
“Lodging online is quick and easy. If businesses are unsure if they need to lodge a TPAR, they can visit www.ato.gov.au/TPAR or ask their registered tax or BAS agent,” said Goding.
The ATO said tax or BAS agents can lodge a TPAR or NLA form for their clients using SBR-enabled software or through Online services for agents.
Miranda Brownlee
26 August 2024
accountantsdaily.com.au
Government urged to exempt small firms from TPB reforms
The lower risk profile of small practices means they should not face the same scrutiny as larger ones, the NTAA says.
.
Small firms should be exempted from the government’s proposed TPB registration requirements as their lower risk profiles do not warrant the additional oversight, the National Tax & Accountants’ Association (NTAA) says.
Treasury’s proposal would allow the board to reject or terminate registrations of companies and partnerships based on more stringent criteria including their compliance with governance requirements.
But the NTAA was concerned the proposed change was “too broad in its application”.
“It is evident that the Treasury has reduced the scope of this proposed change to exclude individual tax agents. However, this exclusion does not go far enough,” it said in a recent submission to Treasury.
“The NTAA suggests reducing the scope of the proposed change to exclude small firms.”
“The lower risk level generally associated with smaller firms that operate as companies and partnerships does not warrant additional TPB oversight at the time of registration.”
It said the additional oversight of small firms was an unnecessary burden and provided no benefit to consumers.
But these concerns did not apply to large multidisciplinary firms that had a higher risk of encountering complex practice issues and ethical dilemmas.
“It is clear that the proposed change is intended to target large multidisciplinary firms. The NTAA is fully supportive of a reform that provides additional oversight of such firms,” it said.
“The proposed change would provide a safeguard of sorts to consumers, as it provides a level of comfort that registered companies and partnerships have appropriate controls in place.”
The NTAA said obligations imposed under the tax agent code of conduct would be adequate to deal with smaller firms, with a recent ministerial determination mandating a quality management system at the time of registration.
“The consultation paper proposes a change that would overlay an additional requirement that must be satisfied for certain types of firms to register as a tax agent,” it said.
It also echoed concerns of other professional bodies that having the stringent new criteria as a registration requirement raised procedural fairness concerns.
“Having the quality management system as a registration requirement rather than an ethical standard means that the TPB can decline a registration application by a prospective agent without having to do any real investigation, which would be required under an ethical standards breach,” it said.
“This does not provide the applicant with a fair and just outcome.”
Christine Chen
21 August 2024
accountantsdaily
Millions of landlords the target of expanded ATO crackdown
The Tax Office will acquire property management records to clamp down on taxpayers misreporting rental income and deductions.
.
The ATO has launched a crackdown on the tax affairs of millions of landlords, targeting those who falsely claim rental deductions and minimise their capital gains liability by inflating costs.
It will expand its data matching program, forcing property management software companies to hand over around 2.3 million user records over a seven-year period from 2018–19 to 2025–26, according to a government gazette notice this week.
The data would be used to trigger compliance activities, improve risk models, and educate taxpayers.
“The Australian Taxation Office will acquire property management data from property management software companies,” it said.
Information requested included property owner identification and property transaction details such as the account balance, income, and expenses.
The ATO would focus on landlords failing to lodge tax returns and their rental property schedule on time, as well as those who “omit or incorrectly report income and deductions in their rental property schedules and associated income tax return labels”, it said.
Another issue targeted was omitted or incorrect reporting of CGT.
“Taxpayers with a rental property may omit or incorrectly report cost base elements which are used to determine the net capital gain or loss on a rental property used to generate income,” it said.
The data matching program builds on an initiative that began in May 2021, which involved collecting four years of data between 2018–19 and 2022–23.
Its expansion comes as the ATO grapples with a significant tax gap in the rental property sector, with nine in 10 landlords getting their tax returns wrong.
Recent audits also showed that incorrectly claimed rental property expenses contributed $1.2 billion, or 12 per cent, to the total $10.2 billion tax gap for individuals not in business during the 2019–20 financial year.
The ATO said data collected from software companies would include detailed property owner identification details and transaction information for both residential and commercial properties.
This included names, dates of birth, addresses, and contact information of individuals as well as business names, addresses, and ABNs.
Property details would also include addresses; rental availability dates; and property manager information, such as their ABN, licence number, and bank account details.
The ATO would also be examining transactions, incoming, and outgoings and the account balance of the rental property.
When the data matching produced discrepancies, the ATO said it would contact taxpayers to allow them to verify the information before taking action.
“They will have 28 days to respond before we take administrative action associated with property management data use,” it said.
As part of the ATO’s tax time campaign this year, it singled out rental deductions as one of three key focus areas.
“This year, we’re particularly focused on claims that may have been inflated to offset increases in rental income to get a greater tax benefit,” Assistant Commissioner Rob Thomson said in May.
He said immediate deductions could be claimed for general repairs and maintenance of a rental property – like replacing damaged carpet or a broken window – but capital expenses could not.
“If you rip out an old kitchen and put in a new and improved one, this is a capital improvement and is only deductible over time as capital works,” Thomson said.
Christine Chen
28 August 2024
accountantsdaily.com.au
Scam alert: fake ASIC branding on social media
The Australian Securities and Investments Commission (ASIC) has issued a scam alert warning consumers that there has been an recent increase in the use of ASIC’s logo in social media scams. ASIC’s warning to consumers covers three main areas of concern.

.
Advertisements on social media platforms: ASIC has received reports of ads on social media platforms displaying the ASIC logo and claiming ASIC sponsorship for a “Stock Trading Master Class”. The ads link to a private WhatsApp group called “Lonton Wealth Management Center” – an entity listed by ASIC on the Investor Alert List in May 2024. ASIC is not associated with the entity, and ASIC does not sponsor the class.
Cold calling: Repeated cold calls from someone purporting to be from ASIC have been reported. The caller tries to engage with consumers about obtaining a refund on an investment. Please note that ASIC does not cold call consumers about investments.
Fake Telegram account: An account on Telegram is impersonating an ASIC social media account, with the operators asking investors for money to release their investment funds held in Australia. ASIC does not have a Telegram account as part of its social media presence and will never ask consumers for upfront payments or taxes to release Australian-held investments.
ASIC is working with the National Anti-Scam Centre (NASC) and social media platforms to remove such content and reminds consumers that it does not endorse or promote investment training or platforms, doesn’t cold call consumers, and is not associated with any investment offerings.
Acctweb
Time for a superannuation check-up?
The new financial year has begun, and with it have come some important changes to superannuation from 1 July 2024. With these changes coming into effect, it’s a good time to give your super a check-up.
.
On 1 July 2024, the superannuation guarantee rate increased from 11% to 11.5% on workers’ ordinary time earnings, for payments of salary and wages. In addition, the concessional super contributions cap also increased from $27,500 to $30,000 and the non-concessional contributions cap increased from $110,000 to $120,000.
The Australian Taxation Office (ATO) suggests the following steps as a good place to start in giving your super a check-up:
- Check your contact details: Make sure your contact details and tax file number (TFN) are up to date with the ATO and your super fund.
- Check your super balance and employer contributions: Checking your super balance and keeping track of your employer contributions can be done at any time through ATO online services or your super fund.
- Check for lost and unclaimed super: If you’ve changed your name, address or your job, you may have lost track of some of your super. Lost super is where your super fund hasn’t been able to contact you, or your account is inactive and then have transferred lost super to the ATO. You can check this online.
- Check if you have multiple super accounts and consider consolidating: If you’ve ever moved jobs, you might have more than one super account. Each account will charge fees and may include insurance, so combining your super accounts may reduce fees, help you pay only for the insurance you need and make your super easier to manage.
- Check your nominated beneficiary: Make sure you have a valid death beneficiary nomination with your super fund, as this isn’t covered by your will. Check with your fund if there is an expiry on the nomination – some funds have options where the nominations don’t expire, while most nominations expire every three years. If you don’t have a beneficiary nominated, your fund will follow the law in determining where your super should go.
In addition, you should be evaluating how your super is being invested and how it matches your stage in life, how much risk you are willing to bear on these investments, if you super fund has insurance cover, does this still meets your needs, and do you have enough super for your retirement goals? This may determine a need to top-up on super contributions before retirement.
Given the many factors to consider, such as your health and life expectancy, inflation and investment returns, wages growth and taxation, and fees and regular contributions, it is best to seek professional advice regarding your superannuation circumstances and options moving forward.
Acctweb
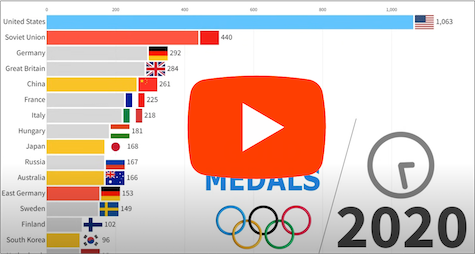
Most Gold Medals in Summer Olympic Games (1896-2024)
Check out which country has won the most Gold Medals in Summer Olympic Games (1896-2024)
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
‘Bleisure’ travel claims in ATO sights, experts warn
Travellers who mix business and pleasure will face increased scrutiny as the Tax Office cracks down on work-related expenses.
.
Business travellers who mix work with pleasure will face increased scrutiny from the ATO this tax time as part of its crackdown on work-related expenses, industry experts warn.
The warning comes as fresh data shows Australians' business trips were twice as long as the rest of the world, averaging six nights compared to the global average of 3.5, according to Flight Centre’s Corporate Traveller division.
Corporate Traveller said those blending business trips with personal leisure time, dubbed “bleisure” travellers, would continue to rise due to reduced flight costs and “strong travel trends”.
“This tax season, business travellers should take extra care to avoid scrutiny,” Global managing director Tom Walley said.
In May, the ATO said work-related expenses would be one of three focus areas this tax time along with rental deductions and a failure to include all income sources in lodgments.
It said over 8 million people made a work-related claim last year and urged taxpayers to follow “three golden rules”, including only claiming expenses if they spent money themselves and were not reimbursed, the expense was directly related to income and there was a record of the expense.
Moneywise Global general manager John Tuohy advised travellers to delay filing their taxes until they were fully prepared.
“There are over 14,000 pages of tax law in Australia, meaning there are lots of incentives and terms and conditions, and with the ATO focusing this year on work-related expenses, it’s particularly important to take that time to get it right, and to understand the nuances to avoid audit triggers.”
“So don’t rush it unless you know your tax is relatively simple and you’re expecting a refund,” he said, with the deadline for returns on 31 October, or mid-May if taxpayers registered with a tax agent.
Corporate Traveller’s flight bookings data found January, September and July were the most popular months for extended business trips, with travellers averaging 7.2, 6.5 and 6.2 nights away, respectively.
Key tips for “bleisure” travellers claiming work-related deductions included maintaining detailed travel diaries of work expenses and avoiding “double dipping” on claims.
“Travellers should keep a travel and expense diary. Often, appropriate annotations in your calendar tool noting dates, times, durations and places of work-related activities will suffice as a 'travel diary' for tax purposes and will substantiate deductions for specific and associated expenses,” Tuohy said.
If leisure travel was “incidental” to a business trip, more expenses such as accommodation and meals would be allowable as deductions.
Legitimate client entertainment expenses and weekend accommodation could also be deductible when business extended from Friday to Monday, he said, however paying to take family on trips or extending travel for leisure before or after work commitments would not.
“Don't be tempted to claim these on your tax,” he said.
Tuohy said day travel was also not an allowable expense. “Public transport, parking, tolls, taxi/rideshare, flights, meals and other incidental expenses that aren’t reimbursed by your employer will only be tax deductible when they are associated with an overnight work trip.”
Christine Chen
22 July 2024
accountantsdaily.com.au
June quarter inflation data reduces risk of rate risk
The June quarter inflation data is likely to see the RBA keep rates on hold next week, economists predicted.
.
The Consumer Price Index (CPI) rose 1 per cent in the June 2024 quarter and 3.8 per cent annually, according to the latest data from the Australian Bureau of Statistics.
“The annual rise of 3.8 per cent for the June quarter is up from 3.6 per cent in the March quarter,” said ABS head of prices statistics, Michelle Marquardt.
BDO Economics partner Anders Magnusson said while yesterday’s CPI data is as sticky as expected, it is no higher than the RBA expected.
“This is good news as the RBA tries to keep a lid on inflation without losing the gains made by workers through a strong labour market,” said Magnusson.
BDO said it maintains its previous forecast that the next movement by the RBA will be a rate cut in early 2025.
“We don’t believe that the RBA will raise the cash rate next week, but the ongoing cost-of-living struggles for many Australians will likely continue until early next year. In particular, inflation in housing is persistent,” said Magnusson.
BDO said a lot of recent “noisy monthly inflation releases” have caused unnecessary worry.
“Globally, countries like the US, Canada, and other European countries have experienced these scares but have eventually moved to lower interest rates,” said Magnusson.
“I expect that we are experiencing a lagged impact of what other countries have already experienced.”
Deloitte Access Economics partner, Stephen Smith said the June quarter CPI data should put to rest the notice that the RBA should lift rates, an act would do nothing but “tempt a recession”.
“Australian mortgage holders and businesses should breathe a sigh of relief as the case for a rate rise should now dissipate,” said Smith.
“If anyone has any doubts about inflation’s downward trend, today’s figures show that annual core inflation has fallen for its sixth consecutive quarter and has reached its lowest rate in two years.”
Smith noted that the factors driving Australian inflation at the moment cannot be fixed through interest rate hikes.
The main factors contributing to the increase were rents due to housing supply constraints, fruit and other food prices due to weather conditions and insurance premiums.
“Higher rates only fight inflation on the demand side, by subduing spending. Australia’s economy is already weak with investment and consumption in the economy too low, and with business insolvencies escalating,” said Smith.
“One thing is clear, the Australian economy is not overheating.”
Smith said lifting rates would fail to bring inflation to target any quicker and would only serve to damage the economy by erasing the benefits of the Stage 3 tax cuts.
Commenting on the latest CPI data, Treasurer Jim Chalmers noted that Australia’s headline inflation peaked lower and later than many comparable economies, while core inflation has moderated faster than the US, Canada and the Euro area.
“We’ve seen around the world that inflation can zig and zag on the way down – and, because Australia’s inflation peaked lower and later than in many countries, we’re seeing that trend here now,” said Chalmers.
01 August 2024
Miranda Brownlee
accountingtimes.com.au
Warning to micro businesses. ‘Higher taxes for thousands of businesses’.
The ATO’s draft guidance on personal service income and the general anti-avoidance provisions is likely to be a shock to many small and microbusinesses in Australia.
The ATO has released a draft practical compliance guideline, PCG 2024/D2, which provides practical guidance on the ATO’s compliance approach for alienation arrangements where personal services income (PSI) of an individual is derived through a personal services entity that is conducting a personal services business.
The PCG, which was released on Wednesday, explains the type of alienation arrangements the ATO considers to be of low or higher risk in terms of Part IVA applying and the likelihood of the ATO having cause to apply compliance resources to review those arrangements.
The guidance in PCG 2024/D1 outlines how the PSI rules of the tax law interact with the General Anti-Avoidance Rules (GAAR) of the tax law, Part IVA ITAA 1936.
“The PSI rules were introduced in 2000. The purpose of those rules was to set out conditions, that if not passed, broadly meant that the income derived by a ‘personal services entity’ would be taxed to the individual that earned the PSI,” said Tax expert and education provider John Jeffreys.
“Instead of seeing the PSI rules as an exclusive code for the taxation of personal services income, the ATO has always maintained that even if the PSI conditions are passed, the GAAR can still have application. That view is supported in a note to the PSI rules.”
Income is classified as PSI when more than 50 per cent of the income received from a contract is a reward for personal efforts or skills of the individual.
The law applies to a wide range of professions and occupations including doctors, dentists, plumbers, electricians, carpenters, bricklayers, accountants, lawyers, beauticians, hairdressers, and many others, Jeffreys said.
The position of the ATO, he said, is that unless (nearly) 100 per cent of the personal services income derived by an individual through an entity is taxed to the individual, the individual should be forced to pay extra tax by operation of the GAAR by taxing the individual on all the PSI.
Jeffreys gave the example of Dirk, an employee plumber being paid about $100,000 per year.
“Dirk decides to start a plumbing business and quits his job. He asks around and concludes that running his new business through a company would be the safest option. Because they share everything, he decides to have the shareholding 50 per cent held by him and 50 per cent by his life partner, Diedre,” said Jeffreys.
“The business goes well. He earns fees of $250,000 in a year mainly from his own personal efforts. He decides to pay himself a salary of $120,000 plus superannuation.”
The company makes an after-tax profit, after Dirk’s salary and other expenses, of $80,000. He then decides to pay a fully franked dividend of $10,000 each to himself and Diedre, meaning there is $60,000 of retained profits.
Jeffreys said that while there may not appear to be anything wrong with this scenario from a tax perspective, there is according to the ATO.
“Dirk could be seen as a tax avoider and should probably be hit with an assessment under the general anti-avoidance rule (GAAR) of the tax law plus penalties,” he said.
“Why has Dirk become a pariah on the Australian taxation system? Because, according to the ATO he has split his personal services income (PSI) with his partner and retained some of the profits of the business in the company.
“To do so is, according to the ATO, illegal. This is because the overall rate of tax payable on the company’s income is lower than if the whole amount had been taxed to Dirk personally.”
Jeffreys said this example is illustrative of the shock that is coming to possibly hundreds of thousands of small and microbusinesses in Australia.
By Miranda Brownlee
30 August 2024
accountantsdaily.com.au
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























