
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
ASIC continues crackdown on dodgy directors
The corporate regulator has taken enforcement action against four company directors and 58 individuals for contraventions relating to company collapses.
.
ASIC said the failure of these directors to meet their statutory obligations had adversely impacted many small business creditors across a range of industries.
“Small businesses employ approximately half of the private sector workforce and contribute more than $500 million to the Australian economy each year. They are essential for Australia’s prosperity,” ASIC said.
Criminal prosecutions and administrative actions were also taken against directors for failing to maintain proper books and records, failing to lodge tax returns, failing to ensure companies had paid statutory debts, insolvent training, failing to assist liquidators and lodging false and misleading documents with ASIC.
ASIC said small business owners can take practical steps to protect their interests such as maintaining financial records to track the health of their business, keeping up to date about their company’s financial position and performance and ensuring their company can pay its debts on time.
In 2024, ASIC disqualified both Constandinos Ganatzos and Mary Makeny for the maximum period of five years, as well as Allan Caratti for four years.
ASIC has said it is continuing to take firm action against directors who fail to meet their statutory obligations in its update for Q2 FY25 update.
During the period from 1 October to 31 December 2024, ASIC disqualified four company directors. Of the four, two were disqualified for the maximum period of five years – one for misleading statements, and another for making false statements.
Additionally, the corporate regulator also took action against 58 individuals for 107 offences of failing to assist registered liquidators following the collapse of their companies.
The regulator also recently disqualified Ian Thomas Griggs from managing corporations for two years on 20 November 2024.
Griggs was found to be involved in the failure of four companies in the hospitality industry, with the four companies owing an excess of $4 million to creditors.
Another director, Jye Dilin Menzies-Clifton, was charged with two counts of misleading statements in a document lodged with ASIC On 27 November 2024.
“ASIC alleges that while director of a company which operated a Sydney gym, Mr Menzies-Clifton submitted a form to close the company which contained declarations that the company had no outstanding liabilities, and that all the members of the company agreed to the deregistration, while knowing those statements to be false.”
The other criminal prosecution involved Benjamin Molloy, who was sentenced to a recognisance release order with a fully suspended sentence of 12 months’ imprisonment on the condition he be of good behaviour for two years.
ASIC said it would continue to take action against directors acting in a way that jeopardised the health of small Australian businesses.
Imogen Wilson
03 February 2025
accountantsdaily.com.au
5 Clauses Tenants Should Look For When Reviewing a Lease
Before signing a commercial lease, verify critical terms like rent, insurance, and renewal clauses to match your business’s future plans.

.
In Short
- Review the lease duration, renewal terms, and rental review clauses to ensure they fit your business needs.
- Confirm insurance obligations and landlord inspection rights to avoid unexpected costs or disruptions.
- A “heads of agreement” is crucial for outlining terms before the final lease is signed, protecting both parties.
Tips for Businesses
Before signing a commercial lease, verify critical terms like rent, insurance, and renewal clauses to match your business’s future plans. Look closely at any “heads of agreement” document to confirm all agreed conditions are included, as this sets the foundation for the final lease. Legal advice is invaluable for avoiding pitfalls.
Commercial leases are binding agreements that outline the obligations between business owners (tenants) and property owners (landlords). They grant you the right to occupy the premises. The terms and clauses in the lease define commercial tenants’ rights. Before signing a lease, you should review specific terms that could impact you. This article includes five key clauses when reviewing your commercial lease.
1. Lease Duration and Extension of Term
The lease duration specifies how long you can occupy the premises, so reviewing this term in your agreement is crucial to ensure it meets your needs. Once your lease expires, the landlord is not obligated to renew it, meaning you’ll need to find alternative premises. To protect yourself, consider including a notice clause if renewal isn’t guaranteed.
Lease durations vary depending on business planning. Early-stage businesses often prefer short-term leases to allow flexibility for future growth, while other tenants might opt for longer leases with fixed renewal options to secure their tenancy.
If you plan to extend your lease, you must notify the landlord of your intention to stay, typically three to six months before the lease ends. Sometimes, this notice period may be longer, so keeping track of these deadlines is important.
2. Rent, Outgoings and Review
As a prospective tenant, you should clearly understand the following:
- the starting rent for the premises;
- the outgoings and any additional fees on top of the rent;
- any unusual or extra costs included in the outgoings;
- consumption costs;
- how and when the rent will increase upon review;
- the method used for rent review, such as a Consumer Price Index (CPI), a fixed percentage, or a market review; and
- the payment method and due dates for rent, outgoings, and other lease-related payments.
Most leases include clauses outlining when and how the landlord will review and increase the rent, typically annually on the anniversary of the lease commencement date, following the method specified in the lease. It is advisable to seek legal advice on rental provisions and, if possible, negotiate a rent reduction.
3. Insurance
Most commercial leases require tenants to obtain specific insurance, including:
- public liability;
- business contents insurance for property and stock;
- worker’s compensation; and
- plate glass coverage.
You must secure an insurance policy and provide the landlord with a certificate of currency. Maintaining up-to-date insurance is crucial in commercial agreements. You should ensure that all insurance policies are current and give the landlord updated copies as the lease requires. These provisions ensure continuous insurance coverage throughout the lease term, which is often necessary for the landlord to hand over the premises.
Failure to comply with insurance requirements may constitute a breach of the lease, allowing the landlord to re-enter and take possession of the property.
4. Inspection When Reviewing a Commercial Lease
As a tenant, you should expect exclusive possession and use of the property. Under common law, you have the right to “quiet enjoyment” of the property. This quiet enjoyment will be subject to the terms of the lease and any rights expressly reserved by the landlord.
However, the landlord cannot significantly interfere with your use and enjoyment of the property if you comply with the lease terms and fulfil your obligations. Therefore, any inspection clause in the lease should be limited to specific situations and require reasonable notice at reasonable times, except in emergencies.
5. Heads of Agreement
After the parties finalise negotiations on the commercial terms of the lease, the first step is to create a “heads of agreement” (also known as an “offer to lease”). This document must accurately reflect all agreed-upon commercial terms between the landlord and tenant. It should be marked as “non-binding” until the lease is:
- prepared;
- reviewed; and
- signed to protect both parties.
Your commercial tenant rights will be established within the heads of agreement, the lease, and any ancillary documents. It is essential to review these carefully to ensure your rights as a tenant are safeguarded.
The heads of agreement should also detail any significant work to be completed by you and the landlord before moving into the premises. Reviewing these details is crucial to understanding the fit-out work required and any incentives the landlord may offer, such as a rent-free period or financial contributions to the work being done.
Key Takeaways
When signing a commercial lease, you enter into a binding agreement with your landlord. It is crucial that the lease is clear and accurately reflects your needs to minimise risks and prevent unwelcome surprises. A well-defined lease that outlines all agreed-upon terms helps avoid future liabilities and disputes. Always seek legal advice before committing to a long-term contract like a lease to ensure your rights as a tenant are protected.
If you need help understanding commercial leases, our experienced leasing lawyers can assist as part of our LegalVision membership. For a low monthly fee, you will have unlimited access to lawyers who can answer your questions and draft and review your documents. Call us today at 1800 534 315 or visit our membership page.
Frequently Asked Questions
Why is the lease duration important?
It determines how long you can stay. Ensure it is appropriate for your business needs and consider adding a renewal option.
What is a heads of agreement?
A heads of agreement is a preliminary document outlining the commercial terms the tenant and landlord agreed upon. This document is essential as it sets the foundation for the final lease terms, including any work to be done by the landlord or tenant before moving in. Reviewing this carefully ensures that your rights as a tenant are protected.
Salary sacrifice and your super
An important consideration in building your super balance is to salary sacrifice you earning to make additional contributions to your super.
.
Your employer can make additional super contributions by salary sacrificing your part of your earnings. This are treated as concessional contributions, taxed at 15% in the superannuation fund. However, this is compared to your marginal income tax rates if this was not sacrificed.
Potential benefits for the regular salary sacrificed superannuation payments include an acceleration of growth of your super balance (which would make a big difference at retirement) and this will lower your taxable income and may help you pay less tax, stay in a lower tax bracket, reduce the Medicare Levy or qualify you for certain concessions, etc
Acctweb
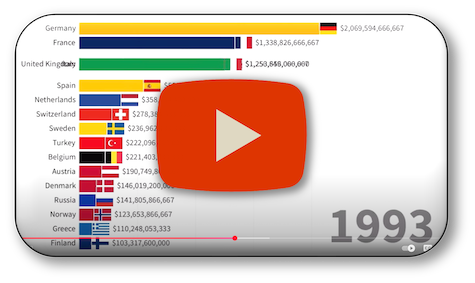
Most Powerful Economies in Europe | 1960-2024
Check out the most Powerful Economies in Europe | 1960-2024
.
.
.
.
.
.
.
.
.
.
.
.
.
Resources and Tools to help our Clients build their future
Making our website into a valuable resource for our clients is very important to us.
Educational videos on accounting and financial planning topics. Every 16 weeks the current range of 6 videos is changed for another 6. All are relevant and interesting. Ensure you and your family are able to learn about many topics related to accounting issues and topics. This month's topics are:
-
Cloud based accounting
-
Understanding Estate Planning
-
Lending Interest Rates Affect Everyone Differently
-
Why you need business expense insurance
-
Individual Trustees vs Corporate Trustees in a SMSF
-
Understanding SMSFs
Latest news articles. 7-9 articles are added every month and all are chosen from 25-30 for their relevance. Our website is a great place to stay informed and articles are very easy to find and read.
Calculators. A good range of calculators to help you better understand and manage your personal and family financial issues. Four of the more popular are: Pay calculator, Budget Calculator, Loan Calculator, and Super Calculator
Client portals. Portals are quite common on many sites and can be used to store your data, pay bills, log onto investment systems, and more.
Ask us a question at any time. If you have a question on any related topic then don’t hesitate to use the Contact Us form to ask.
Your information is private and confidential and should be treated that way. Using Secure File Transfer means your information is encrypted when sent in either direction over the Internet.
Many sites also have a message window feature that displays messages of interest or that cover topics and deadlines you should be aware of.
* Not all are on every website.
E-Commerce Laws You Must Know To Run An Online Business
Make sure your e-commerce business complies with Australian Consumer Law by having accessible terms and conditions.
In Short
- Understand key e-commerce laws, including Australian Consumer Law (ACL), privacy laws, shipping regulations, and intellectual property (IP) protection.
- Ensure your e-commerce policies (returns, refunds, and cancellations) are clear and comply with legal standards.
- Prioritise customer data protection and stay informed about shipping restrictions for your products.
Tips for Businesses
Make sure your e-commerce business complies with Australian Consumer Law by having accessible terms and conditions. Always publish a clear privacy policy detailing how customer data is handled. Understand shipping restrictions and check with couriers about any product limitations. Lastly, protect your intellectual property with trademarks and avoid using content you don’t have permission to use.
E-commerce is a relatively new retail branch, having taken off recently as the internet has exploded. It is important to note that all businesses, including those operating exclusively online, are subject to rules and regulations. Whether you are a new or well-established e-commerce business, there are several laws you must know. This article will take you through four e-commerce laws you must understand to run an online business.
Australian Consumer Law
The Australian Consumer Law (ACL) oversees all e-commerce transactions in Australia, making it essential to prevent legal disputes or breaching any obligations. The ACL provides consumers with specific legal rights and ensures businesses can be held accountable for their actions.
The ACL compels you to guarantee several elements. This includes the product must:
- be without defects;
- match the description on the website;
- meet safety regulations; and
- come with certain guarantees, including the right to request a replacement, refund or cancellation.
Failure to comply with ACL can lead to disputes and complaints reported to the Australian Competition and Consumer Commission (ACCC). Although it is impossible to contract out of these guarantees, you should still have an e-commerce policy. This policy should be outlined in easily accessible terms and conditions, outlining conditions and time frames for returns, refunds and cancellations.
Privacy Laws
All businesses should be aware of the relevant privacy laws. This is particularly pertinent for e-commerce businesses, which have access to a larger market than traditional businesses. Depending on where your e-commerce business operates, you will need to know the different applicable rules and jurisdictions.
In Australia, the Privacy Act 1988 provides critical laws protecting private information. This includes the collection, use, storage and sharing of any personal information. However, even if this legislation does not apply to you, you must protect your customers’ data to prevent any data breaches. Therefore, all e-commerce businesses should prioritise publishing a highly visible privacy policy outlining exactly how they handle sensitive data.
Shipping Laws
Before setting up an e-commerce business, you must know specifically what you can and cannot send to customers. The Australian Code for the Transport of Goods by Road & Rail outlines some dangerous goods you cannot ship in the mail. This includes:
- explosive materials;
- certain liquids; and
- perishable items, including fresh fruits and vegetables.
The courier company you choose to use for your e-commerce business will also have their own restrictions. For example, certain courier companies will not ship glass because of the potential dangers if the item breaks. Therefore, before setting up your business, you should check that you can legally ship your goods.
Intellectual Property
All e-commerce businesses should be aware of intellectual property (IP) laws. Knowledge of this will protect your business and ensure you do not impede on the IP of others. An e-commerce business’s IP will include all its intangible assets, including its branding material and online content. Protecting your branding with a trade mark is one way to prevent anyone from using your IP for their benefit.
In addition to protecting your IP, it is equally important to not ‘steal’ anyone else’s. This includes ensuring all content you publish is either original or royalty-free content that you can use safely. If you use someone else’s IP without their consent, you risk legal disputes and tarnishing your business’ reputation.
Key Takeaways
To run an online business safely and successfully, e-commerce business owners must be aware of the laws surrounding their operations. Some important e-commerce laws to be aware of include laws regarding:
- Australian Consumer Law;
- privacy;
- shipping; and
- intellectual property.
Frequently Asked Questions
What is e-commerce?
E-commerce refers to a business model selling goods and services online. E-commerce allows businesses to access a wider market, making it popular for smaller companies with a narrow reach. Australia is one of the largest e-commerce markets in the world, with the industry continuing to expand.
What e-commerce laws should I know to run an online business?
To run an online business safely and successfully, e-commerce owners must know the laws surrounding their operations. Some essential laws that e-commerce business owners should understand include laws regarding the Australian Consumer Law, privacy, shipping and intellectual property.
By Emily Young
Legal Vision
Legalvision.com.au
ATO issues alert on guarantee arrangements and Division 7A
A new taxpayer alert raises concerns about certain arrangements involving guarantees by private companies for third-party loans.
The ATO this week has issued taxpayer alert TA 2024/2 and taxation determination TD 2024/D3 which explain its views on where section 109U of the ITAA may apply to arrangements where a private company gives a guarantee to another private company.
The ATO issued the taxpayer alert to warn entities and tax practitioners about its concerns regarding contrived arrangements seeking to circumvent Division 7A.
“The arrangements involve a profitable private company guaranteeing a loan made by a bank, or other financial institution, to a related private company with – minimal or no distributable surplus. Amounts are then loaned or paid to a shareholder or associate of a shareholder,” the ATO said.
“We consider the arrangements are not effective and that Division 7A would apply to deem the private company which gave the guarantee to have paid an unfranked dividend. Alternatively, Part IVA of the Income Tax Assessment Act 1936 (the general anti-avoidance rule) may apply.”
The ATO stated in the taxpayer alert that it is currently reviewing arrangements under which:
- A private company (the first company) guarantees a loan made by a financial institution to a related private company that has no or minimal distributable surplus.
- The related company on-lends (or pays) some or all of the amount borrowed from the financial institution to the first company's shareholders (or their associates) on terms that do not comply with the requirements of Division 7A of the Income Tax Assessment Act 1936 (Division 7A).
The Tax Office said the alert only applies to arrangements that, when viewed objectively, involve a series of steps intended to circumvent the operation of Division 7A.
The ATO said it is concerned that taxpayers may be entering these arrangements on the misunderstanding that section 109U, within Division 7A, only applies if the third-party lender is a private company.
“This is not the case. Section 109U requires the entity which makes the payment or loan to the shareholders to be a private company, but it does not require the entity to which the guarantee is given to also be a private company.”
BDO tax partner Mark Molesworth warned the ATO would need to be careful with its approach set out in the alert and determination, as taxpayers may fall into these situations with no intention of avoiding tax.
Molesworth said while the ATO said it will only pursue arrangements that are objectively designed to get around Division 7A, it doesn't provide any detail on what objective facts would mean that the arrangement is considered to be an attempt to circumvent Division 7A.
“We're relying on the Commissioner's approach which is not ideal for certainty for taxpayers.”
“It's also been dropped two weeks before Christmas so advisors and their clients are now going to be scrambling around working out who's provided guarantees to banks and who the banks have lent to.”
By Miranda Brownlee
13-12-24
accounantsdaily.com.au
Warning on ATO data matching “lifestyle” assets and your business
Data matching programs are a major compliance tool at the ATO and taxpayers need to be aware of them.
The ATO has announced/extended a number of data-matching programs recently. This includes lifestyle assets data matched from insurance providers for 2023–2024 to 2025–2026 for specified classes of asset where the asset value is equal to or exceeds nominated thresholds.
The assets and thresholds covered are:
- caravans/motorhomes: $65,000;
- motor vehicles including cars, trucks and motorcycles: $65,000;
- thoroughbred horses: $65,000;
- fine art: $100,000 per item;
- marine vessels: $100,000; and
- aircraft: $150,000.
The aim is to determine any tax risks relevant to businesses that the ATO is keen to address. This includes the omission or incorrect reporting of income and/or capital gain; omission or incorrect reporting of FBT, incorrect GST credits claims, use of assets in SMSF in breach.
This highlights the need to review your business assets to determine if you have such assets held and if these have been treated correctly in your accounts.
AcctWeb
Managing your business’s tax debts
The ATO has recently shifted to a more active approach to debt recovery and may require a more proactive method from you with dealing with tax debts.
You or your tax agent can review your income tax assessment notices or use the ATO's online services to check your current tax debt. You can also contact the ATO directly by phoning 13 28 66 (the business enquiries line).
If you find yourself unable to settle your tax debt in full by the due date, don't panic. The ATO offers several repayment options, including:
- For debts under $100,000, you can set up a plan online using self-services. This option is available if you don't already have an active plan for the same debt and can cover the amount within two years.
- For larger debts or more complex situations, you can propose a tailored payment plan. The ATO provides tools like the Payment Plan Estimator and Business Viability Assessment Tool to help you create a realistic proposal. In addition, the ATO may need to assess capacity to pay, including details such as income sources, expense and cash flow information.
Remember, entering into a payment plan means committing to paying future tax obligations on time as well and interest charges apples to unpaid tax debts.
The key to managing your tax debt successfully is proactive communication. If you're experiencing difficulties, don't wait for the ATO to contact you. Reach out to the ATO directly, or to your registered tax agent, as soon as possible. By engaging early and honestly, you can avoid more serious potential consequences like director penalty notices, garnishee notices or having your tax debt disclosed to credit reporting bureaus.
AcctWeb
Social media scams dominate losses in 2024
Scammers exploiting online platforms fleeced Australians out of $58 million, topping all other fraud categories.
Australians lost $58.3 million to social media scams this year, according to the ACCC, but there are signs a multi-agency crackdown is working.
Deputy chair Catriona Lowe called social media a “gold mine” for scammers, costing more than any other scam method in the first 10 months of 2024.
“In the September quarter alone, we saw a 146 per cent increase in reported financial losses linked to social media,” Lowe said.
Social media scams were substantially more financially damaging per incident despite being less frequently reported by victims.
While they accounted for over one-fifth (22 per cent) of the $262 million lost to scams in 2024, they only represented 7 per cent of total reports to Scamwatch.
“It shows just how lucrative these scams are for the criminal groups behind them – and serves as a reminder to us all of the need to be suspicious of anyone who unexpectedly contacts us on social media,” Lowe said.
Of the $58.3 million lost to social media scams, Scamwatch data showed the top categories were investment scams ($39.2 million), romance scams ($9 million) and job scams ($4.5 million).
Fraudsters often created fake social media profiles, posing as trusted individuals like financial advisers, romantic partners or recruiters to deceive victims into handing over money or personal information.
“They learn a lot about you from what you share on social media and trick you into sharing personal information, which they then use to target you in other scams,” Lowe said.
It comes as the ACCC’s National Anti-Scam Centre delivered an update on its crackdown on job and employment scams.
Since launching a job scam fusion cell to co-ordinate anti-scam action between the government and industry in September, the ACCC said NASC had taken down over 200 job scam websites and referred over 200 phone numbers for disruption.
It said it was also working with law enforcement, government agencies and cryptocurrency platforms to freeze or restrict cryptocurrency wallets being used in job scams.
“The fusion cell is already proving effective in disrupting the activities of criminal groups who are stealing from Australian job seekers by advertising or offering jobs that do not exist,” the ACCC said.
It is the second fusion cell launched by NASC since it commenced work in July in the ACCC last year.
An investment scam fusion cell that ran from August 2023 to February 2024 removed over 100 scam advertisements and 220 websites and diverted 113 consumer calls to a recorded warning.
“Job scams involve criminals posing as legitimate businesses or recruiters and targeting jobseekers with lucrative offers to complete tasks – deceiving their victims into handing over money,” Lowe said.
“This public-private taskforce has brought together expertise from social media platforms, online employment websites, banks, cryptocurrency platforms, law enforcement, and commonly impersonated businesses to tackle these scams.”
By Christine Chen
10 December 2024
accountantsdaily.com.au
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...
Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























