
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
Which country produces the most electricity annually?
Check out which Country Produce most Electricity per year (TWh), including
Coal, Gas, Hydro, Nuclear, Wind, Solar, Oil and Bio.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
The ATO’s new draft rules could change your holiday home tax claims
A new ATO draft guidance aims to clarifies how to work out if your property’s considered a holiday home under this rule, and how much you can legitimately claim expenses.
.
The draft guidance addresses when a property is a “holiday home” for tax purposes and considers common scenarios like renting to family or friends at reduced rates. It outlines what the ATO considers fair and reasonable methods to split expenses between income-producing use and private use; for example, if your holiday home’s rented out half the year and you use it for the other half, you can claim roughly 50% of general costs like interest, utilities and insurance as deductions.
In the addition, the guidance introduces a traffic-light system of risk zones. “Amber” covers medium-risk scenarios where you rent the property but also use it personally for a significant part of the year.
“Red” covers high-risk arrangements where the property’s mostly used by you or your family, with infrequent or non-commercial rentals, but with expenses claimed. If you’re in the red, the ATO will suspect the property’s mainly a lifestyle asset rather than a genuine income-producing investment, and will be more likely to investigate or challenge your claims.
While these rules are drafts right now, the ATO plans to apply them retrospectively once they’re finalised, with a transitional compliance approach for arrangements in place before 12 November 2025.
We suggest to re-review your holiday home usage and review your past claims. Improve your record-keeping by maintaining a log of rental periods, vacant periods and personal use dates.
Acctweb
Heading overseas? Centrelink and the ATO might need to know
Different government payments have their own rules about whether, and for how long, they’re paid while you’re outside Australia.
.
Short trips for most families are usually fine, but longer absences can reduce, pause or stop certain payments. You must also keep meeting the usual eligibility tests (residency, income and assets) while you’re away.
For instance:
- JobSeeker and Youth Allowance: These typically stop as soon as you leave Australia, unless you have an approved reason. Youth Allowance or Austudy may continue if the time overseas is an approved part of your Australian course.
- Age Pension: There may be changes to your payment rate after six weeks and after 26 weeks abroad.
- Disability Support Pension (DSP): You can receive DSP for up to 28 days in a 12-month period overseas. Extended stays may require special approval.
- Family Tax Benefit: Payments usually stop after six weeks overseas.
You should inform Services Australia of any travel plans to ensure correct review of information before any border movement data is shared with Services Australia (and trigger a surprise review). Also check payments status when you get home.
The tax side is simpler. A short holiday doesn’t usually change your Australian tax residency, or payment processing. Longer absences may effect residency, reporting arrangements and student loan obligations, so best to discuss these before you leave.
Acctweb
‘Not insurmountable’: What accountants need to know ahead of Payday Super
As Payday Super obligations are set to come into play for employers in July this year, two experts provide insight on what accountants, advisers, and employers need to be aware of.
.
With the Payday Super start date approaching hard and fast, there will no doubt be many challenges and hurdles to overcome as employers scramble to comply by 1 July.
On a recent Accountants Daily and Yellow Canary live stream, Yellow Canary general manager Kirsty Martin and Alvarez & Marsal managing director Amanda Spinks shared how the incoming regime would change how employers and accountants manage super payments.
Martin said superannuation was already complex, with an average underpayment for wages and salaries of 1–3 per cent of total payroll, which superannuation could be a “knock on” effect from or the underlying set-up in a platform.
“It’s really important to look at that setup in the platform. The increased frequency is actually going to expose any underlying payroll configuration issues faster, which can be a really good thing to help you get on track much sooner than you would at the moment,” she said.
“The key is the change management piece, so you need to loop in stakeholders early. Get everyone on board, create a team environment and discuss those impacts on the various areas of the business.”
Martin noted she believed there to be lots of “offshoots” apart from the actual processing, meaning cash flow changes needed to be looked at.
According to Martin and Spinks, within this upcoming change, it was crucial to view collaboration as a key piece of the puzzle, as everyone needed to be on the same page, across the same messaging, and briefed with the same information.
This is linked to the fact that accountants would now need to be more closely aligned with payroll teams, as efficiency and ability to adapt to the Payday Super changes would depend on this.
“We need financial literacy for payroll and payroll literacy for accounting teams to ensure we get that fluency and identify all the stakeholders to discuss how to manage this change,” Martin said.
Spinks added: “None of this is insurmountable. And as Kirsty said, there are multiple people that we need to be involved with, and will be, the key to making sure that this is done successfully at any business.
“It’s really important to bear in mind that tax, finance, and HR teams are all going to need to be involved while we are waiting for software companies to update their tech. Give them a minute. Payday Super is going to really require you to update and implement new processes.”
The pair flagged it was increasingly important with this new process that, if anything out of line was noticed, a voluntary disclosure would need to be made to the ATO as soon as possible.
Spinks said typically it was required for tax to be involved in these conversations and vary across what’s happening with any ATO interaction, as it was critical to identify any shortfalls, how shortfalls would be rectified, and how these would be disclosed.
According to Spinks, it was important for accountants and finance teams to look at how often voluntary disclosures were being made, the process, ensuring the payments were being made, and if the assessment was being made by the ATO.
“We’ve got tech and we’ve got new processes, so what do your governance policies say and how is your board going to react to all of this?” she said.
“You’re going to need to have it all outlined for them. Practitioners can really be involved with all of these steps, really making sure that everyone is across and helping to get through all these processes that need to be done… not insurmountable.”
06 January 2026
Imogen Wilson
accountantsdaily.com.au
Digital Assets You Forgot You Own (and Why They Still Matter at Tax Time)
Forgotten digital assets like old domains, online wallets and unused subscriptions can carry tax consequences in Australia. Here's what the ATO wants you to know.
.
Key Highlights
- Digital assets include domains, online wallets, subscriptions, and income platforms
- Forgotten assets can result in unclaimed income or tax reporting gaps
- Managing domain names is one example of staying on top of digital ownership
- A quick digital audit before tax time helps reduce costs and avoid mistakes
When you think about what needs sorting before tax time, your mind probably goes straight to invoices, receipts, or maybe that shoebox of expense records. What usually doesn’t make the list? Digital assets. Not just the obvious ones like crypto — we’re talking about the forgotten stuff. That domain you bought five years ago for a side project. The PayPal account with a lingering balance. A design software subscription that still bills you every quarter.
These digital remnants of past ideas or old routines might seem trivial, but they don’t disappear just because you’ve moved on. They can carry real financial value, attract ongoing charges, and in some cases, require reporting to the ATO. The more digital our lives become, the easier it is to overlook assets that live behind logins and email alerts.
You don’t need to be in tech or business to have digital assets. If you've ever bought a domain, earned money online, used cloud tools, or sold something through a digital platform, you’re in the picture. And what you’ve forgotten could quietly affect your records — especially as the ATO starts looking more closely at digital activity.
What Counts as a Digital Asset (and Why the ATO Cares)
Digital assets aren’t limited to investment tools like crypto or NFTs. In tax terms, they can include anything owned or controlled in digital form that holds value or generates income. Think domain names, PayPal and Stripe accounts, cloud storage credits, software subscriptions, digital products, online memberships and loyalty point balances.
The ATO has already flagged digital asset tracking as a growing focus area. They're paying closer attention to undeclared online income, capital gains on digital sales, and deductions linked to digital tools. That includes small business operators, sole traders, side hustlers, and even individuals who’ve passively held online assets for years.
Unlike physical assets, digital ones tend to stay hidden — until they pop up in bank statements or audit trails. That’s why the ATO’s data-matching programs increasingly scan for payment platform activity, crypto wallets, and business tools with financial links. Whether or not the asset is active, ownership alone may carry tax consequences.
Common Digital Assets Australians Forget They Own
It’s surprisingly easy to lose track of what’s still in your name. A domain purchased during a uni project. A few hundred dollars sitting in an old PayPal account. A Canva Pro subscription still charging your card. Accounts on platforms like Etsy or Gumroad with small earnings that never made it to your bank.
Crypto wallets with forgotten tokens. Old eCommerce storefronts. Cloud services or website hosting packages that auto-renew. Affiliate platform earnings you didn’t realise were taxable. These aren’t niche problems — they’re everyday scenarios. And while none of them might seem significant on their own, they can add up to messy tax returns or missed deductions.
Tax Time Risks of Forgotten Digital Assets
The ATO doesn’t just care about what you’re actively using. They care about what’s in your name, what earns income, and what changes in value. If you’ve sold a domain, cashed out a token, or let a digital asset expire after it had been linked to business activity, there may be tax implications — even if you forgot it was there.
You might be paying for things you no longer use, like subscriptions or storage. You might also be entitled to deductions you’re not claiming, simply because you overlooked a tool that’s technically still part of your workflow. If you’ve made money through digital platforms but didn’t report it, you could end up under-declaring income.
How Domain Names Fit into the Bigger Picture
Domain names are a great example. Plenty of Australians own domains they haven’t used in years. Some were set up for old blogs or side businesses, others for ideas that never launched. But if those domains are still renewing, or were ever linked to a business ABN, they can’t be ignored at tax time.
Effectively managing domain names is a key part of the wider digital clean-up. Knowing what you still control, what’s worth keeping, and what should be written off or sold makes your tax position clearer. Domains can sometimes hold resale value too, which may attract capital gains if sold.
Simple Steps to Reclaim Control Before Tax Time
A simple digital audit is all it takes to stay ahead. Go through your inbox for old subscription receipts. Log into your domain registrar or hosting provider to see what’s still active. Check balances on PayPal, crypto wallets, and online marketplaces. Make note of what’s linked to your business, what you’re still paying for, and anything with income potential.
Work with an accountant who understands digital asset reporting in Australia. The ATO’s approach to digital income is tightening, and guessing your way through it won’t cut it anymore. Even if an asset doesn’t trigger a tax event this year, keeping it on your radar ensures you’re ready when that changes.
Final Thoughts
Digital assets have become part of modern financial life — but they’re often treated like digital dust. Whether it's a domain quietly auto-renewing, a side hustle account you forgot about, or a few dollars in a wallet you haven’t touched in years, the ATO may still want to know about it.
It’s worth taking time before June 30 to look at what you still own online. Because if it holds value, costs money, or ever touched your business activity, it matters more than you think.
31 December 2025
Dominic Vivarini
accountantsdaily.com.au
ATO cracking down on tax dodgers trying to leave the country
The Tax Office is issuing departure prohibition orders as it moves to bolster payment performance and debt collection.
.
In a statement, the ATO has said it is focused on reducing unpaid tax and “bringing down the $50 billion collectable debt book” through its approach to debt management, including taking necessary actions on taxpayers who refuse to pay debts, particularly those relating to unpaid employee superannuation, and taxes withheld from employees’ wages, or collected from customers as GST but not passed on to the government.
One way the Tax Office is doing this is via departure prohibition orders (DPOs), which are enforcement actions to prevent certain persons with tax liabilities from leaving Australia without paying.
DPOs, ATO noted, are often applied in conjunction with other firmer actions, “where the impact of these other actions would be limited or rendered futile if the taxpayer left the country”.
The increased use of DPOs, the Tax Office said, “is just one example of the strong and deliberate action the ATO is taking to deal with taxpayers who are continuing to ignore their obligations and refuse to engage to pay their outstanding amounts”.
ATO assistant commissioner Anita Challen said: “Taxpayers with significant debts to the ATO that think they can skip the country without paying what is owed to the community should think again.”
“We think most Australians would expect businesses to pay their employees’ superannuation before they plan an overseas holiday,” she said.
The consequences of being issued a DPO are “serious and confronting,” Challen added.
“A taxpayer issued a DPO was recently pulled aside and prevented from boarding an international flight out of Australia in the early hours of the morning.”
“If you have a significant debt with the ATO and we’ve issued you with a DPO, you’ll need to pay or make satisfactory arrangements to pay before planning your overseas travel,” she said.
“The ATO strongly encourages taxpayers who cannot meet their obligations on time, to engage with us or speak with their registered tax professionals early. Putting your head in the sand is not an option.”
“Not paying tax affects everyone, and it is common for businesses who aren’t paying their tax to owe money to more than one creditor and, if this [is] not addressed, they can put other small businesses and their employees at risk,” Challen concluded.
Since July 2025, the ATO has issued 21 DPOs, it said, which was more than the total number issued in the most recent financial year.
09 January 2026
Jerome Doraisamy
accountantsdaily.com.au
8 tips to improve your online sales
Online shopping sale days have become more common with a number of major events throughout the year.
.
8 Tips to improve your online sales
Events like Click Frenzy, Black Friday and Cyber Monday are becoming more popular among businesses for boosting sales.
Here are some tips to help your small business make the most of online sale events throughout the year.
1. Optimise your online store
Online shoppers have come to expect easy and smooth transactions when buying online. Make your online store the best it can be by optimising your site to convert visitors into customers and make sure it has the bandwidth to handle any increase in traffic on sale days.
Some eCommerce platforms, such as Shopify, allow you to email visitors who abandon their shopping carts on your website. This can give you one last chance to remind customers that their items are still waiting and even offer a coupon.
2. Embrace click and collect
Adding a click-and-collect option to your online store gives customers the convenience of online shopping without the shipping time and cost.
Power Retail surveyed 1,000 online shoppers and found that 63% of people had used click & collect. Customers are continuing to choose click and collect because it is faster and cheaper than shipping.
For more on click and collect, read Power Retail’s article.
The key to click and collect is to have accurate stock levels that update in real-time and processes that allow you or your employees to reserve items as soon as an order comes in.
3. Adapt to the sale day and target market
Sale days can be a great opportunity to move old or out of season stock. Think about the type of consumers you might get for each sale day and what they might be shopping for.
Finder does a great breakdown on the types of people that typically shop on each of the big sale days. Take a look at the Black Friday statistics from 2024.
If you had an online store last year, check your analytics for trends on what your customers looked for and bought.
If you’re interested in measuring analytics, doing keyword research or improving your search engine optimisation, find out more on Website analytics.
Consider adding a ‘gift ideas’ section to your website and creating social media posts or blog articles to encourage customers to browse for items.
Bundle pricing, gift packs, vouchers or offering gift wrapping can also make shopping easier. Keep in mind how long it will take to package and deliver products during busy periods like EOFY sales, Boxing Day or Christmas.
4. Focus on what your business can offer customers
As a small business, consider promotions that are less likely to damage your profit margin, such as:
- an extended returns policy
- free or discounted shipping over a certain amount
- quantity discounts
- gift wrapping and cards
- gift with purchase.
- Offering pick-up or fast local delivery will draw shoppers who have a deadline and can’t afford shipping delays. Don’t worry, we’ve all been there last minute trying to find gifts.
If offering a gift with a purchase online, make sure it’s something that will be cheap enough to post and factor the cost into your margins.
5. Use your small scale to your advantage
Capitalise on what customers can get from your business that they can’t from big stores or brands. Use the fact that you are local, have relationships with many of your customers and can offer an in-person and personalised shopping experience to your advantage.
Some of your customers may be intimidated by crowds and might not like busy in-store sale days. Your small sized store and fast delivery of products can appeal to these people.
A carefully wrapped package and personalised note in online orders can also go a long way to create a connection with customers you may never see face-to-face.
Read more about the power of packaging with our article, Why unboxing should be part of every online retailer’s marketing strategy.
6. Promote on social media and in newsletters
If you’re thinking about running a sale, there’s no better way to promote it than through a social media campaign. This can be done with paid advertising to attract new customers or with organic posting to let your existing customers know you have a sale.
For tips on starting a business social media account or ways to improve your existing one, find out how to Use social media for business.
Promote your sales in advance on social media and get your followers to spread the word with these tips:
- Experiment with one of the big sale days and start with a small-budget social media campaign.
- Offer exclusives to social media followers and newsletter subscribers.
- Hold competitions for followers who tag friends in your posts or repost your promotion posts to spread the word.
- Widen your net with #blackfridaysales #blackfriday2025 and other related hashtags in your posts.
- Use banner and profile images on your social media channels and google business profile listing to promote your sales day campaigns.
7. Make it an exciting event
Your small business may not have the capacity to do what the big stores do, but there are ways to keep your customers engaged.
Here are some small ways to take advantage:
- Organise different promotions for different days (or times) of a sales period ask customers to post on social media and tag you in exchange for a chance to win.
- Reward your social media followers or newsletter subscribers with VIP discounts or early bird deals.
- Set a limit on a particular deal at the beginning of a day to get customers to act quickly.
8. Reach a wider audience with an online marketplace
There are pros and cons to small businesses selling products through online marketplaces like Amazon, eBay, Catch, Ozsale or even Facebook Marketplace. These platforms provide a large audience for you to tap into.
For big sale days, marketplaces are often the most efficient ways for customers to do their shopping. Getting your products out in the market can also be faster this way if you’re starting from scratch.
One thing to remember, you give up a portion of your profits to the marketplace provider and lose some of your brand identity to the bigger umbrella brand.
Instead of interacting with you, customers interact with the marketplace, so you lose some control over the customer experience that many small businesses find essential to building connection and brand loyalty.
Ultimately, the decision to use a marketplace will depend on your business plan and the goals you’ve set for your business.
When selling on an online marketplace make sure you:
- Add as much detail as possible to your listing, including important keywords, tags and filters.
- Consider using the marketplace’s advertising options to bump your products to the top.
- Add different shipping options and make your pick-and-pack as efficient as possible.
Take your online sales to the next level
Improving your online presence starts with digital marketing. Some businesses build a website, others use a social media page or an online store. At some point you’ll need to start promoting yourself. Here are some resources to get you started or to help you improve your existing strategies.
Business Victoria
13 Mar 2024
business.vic.gov.au
13 Mar 2024
business.vic.gov.au
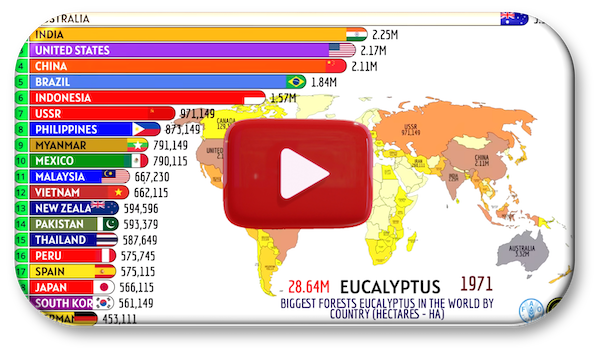
Countries with the largest collection or eucalyptus trees
Check out the countries that have started to grow their eucalyptus tree stocks
.
.
.
.
.
.
.
.
.
.
.
.
.
.
.
Super gender gap slowly narrows
The latest Financy Women’s Index (FWX) for the September quarter has shown the superannuation gender gap is closing, with true parity between men and women now predicted to be achieved in a more rapid timeframe.
.
To this end, the FWX superannuation sub-index rose by 0.6 points to 79.2 points during the quarter partly on the back of improved female wage growth. This resulted in the estimated period of time it will take to completely close the gender gap falling to 13.9 years, down from the previously predicted 17 years.
FWK author Bianca Hartge-Hazelman noted the superannuation sub-index now has the second-shortest timeframe to equality of any sub-index after ASX 200 boards, forecast to be 4.7 years.
“Closing the gender gap in superannuation savings is a crucial step forward to improving the long-term financial security of women, given that they are more likely to spend time out of the paid workforce caring for loved ones,” the report stated.
Overall, the FWX rose 0.12 points over the September quarter to 79.44 points, a new record high with underemployment and superannuation elements playing a key role in the result.
“This record high is reflective of fragile progress. While we celebrate the gains in superannuation and hours worked, the cracks appearing in childcare confidence and the stagnation in board diversity serve as a stark reminder that our progress is not yet cemented in strong foundations,” Hartge-Hazelman said.
Women’s full-time employment fell slightly (0.1 per cent) in the quarter, as part-time employment rose by 1.2 per cent, and participation rates retreated from recent highs as childcare usage dropped following recent safety failures.
“When families can’t trust the childcare system, women step back from work and men stay out of the care workforce – reinforcing the idea that caregiving is ‘women’s work’,” Deloitte Access Economics associate director and FWX Advisory Committee member Rhiannon Yetsenga explained.
“Breaking that cycle starts with affordable, high-quality childcare, unlocking more equal participation and a more balanced gender workforce over time.”
November 26, 2025
Penny Pryo
smsmagazine.com.au
Protecting yourself from misinformation
The Australian Taxation Office (ATO) has observed websites attempting to harvest personal information such as Tax File Numbers, identity details and myGov login credentials under the guise of providing “super advice”.
.
To protect yourself:
- Always verify information through trusted sources such as ATO, Australian Securities & Investments Commission Money Smart or your super fund.
- Consult a registered tax professional or licensed financial adviser for personalised guidance.
- Be wary of “free expert” tax advice from unverified sources.
- Think twice before acting on information from social media or non-official websites.
- Check if tax professionals are registered with the Tax Practitioners Board before engaging their services.
Acctweb
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























