
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
‘Visible, valued and owned’: ATO outlines super priorities for new year
The ATO has renewed its commitment to making sure super is “visible, valued and owned” in 2020, naming consolidation of member accounts and reducing the incidence of SG non-payment as some of its key priorities for the coming year.
In a recent statement published to the ATO website, ATO deputy commissioner James O’Halloran said the regulator would keep an eye on ensuring the implementation of any reforms in the super space were “fit for the future” in terms of the impact they would have on practitioners going forward.
“Just like many of our readers, we’re in the business of turning concepts into reality; the implementation of any major reform must not only be designed to be ‘fit for purpose’ but also ‘fit for the future’,” Mr O’Halloran said.
“Or to put it another way, super is about people and their future. So, we’ll keep the client experience front and centre of all we do, because we know our approach and actions impact your members’ plans for their investments and their retirement.”
Mr O’Halloran added that the ATO would continue to scrutinise employers around SG non-payment in the new year, a process that had been made easier by the rollout of the Single Touch Payroll system over the course of 2019.
“Aided by the introduction of Single Touch Payroll and fund event-based reporting, we now have an unprecedented level of ‘visibility’ of super information at the account and transaction level and we’re increasingly using this capability,” he said.
Mr O’Halloran also touched on the introduction of myGovID as a key achievement for the year that would continue to roll out in 2020.
“We’ve recently launched myGovID, the federal government’s digital identity solution which aims to transform how Australians interact with government,” he said.
“It will be faster and easier to prove who you are when accessing government online services.”
He added that while the ATO “can’t predict the next wave of reform”, it would focus on ensuring super was “visible, valued and owned” by Australians in the coming year.
Sarah Kendell
30 December 2019
accountantsdaily.com.au
Australia by the Numbers
The following data is used to make decisions that effect every Australian's life.
Please click on the following link to see all this interesting information. The areas covered are:
- Overview
- Markets
- GDP
- Labour
- Prices
- Money
- Trade
- Government
- Business
- Consumer
- Housing
- Taxes
- Climate
Access all this data here.
tradingeconomics.com/australia
Accounting profession responds to bushfire crisis
The professional accounting bodies have begun launching initiatives to help support accountants and their clients affected by the ongoing bushfire crisis.
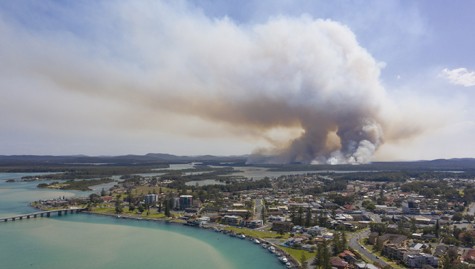
Chartered Accountants Australia and New Zealand (CA ANZ), CPA Australia and the Institute of Public Accountants (IPA) have now confirmed that they will be providing support to communities ravaged by the bushfire disaster.
CA ANZ has now partnered with Rural Aid to connect members wishing to assist drought and fire-affected businesses in rural and regional Australia with monetary donations as well as donations of their time and skill.
A range of CA ANZ resources has also been made available, including a checklist on practical issues for small businesses impacted by bushfires, and a mental health first-aid guide to help accountants engage in difficult conversations with their clients.
“As bushfires and extreme heatwave conditions persist across regions in Australia, my thoughts are with all our members in practice, your clients and the wider communities during this time, particularly those who have had losses or needed to evacuate to safety,” said CA ANZ president Peter Rupp.
“Accountants are often the backbone of their communities, playing a critical role to help Australians and businesses navigate the financial impact of bushfires and assist them through recovery.”
The IPA has also begun reaching out to its membership base to create a pro bono register for members to volunteer their services.
The accounting body had previously carried out a similar exercise in the 2009 Black Saturday bushfires and the 2010 Queensland floods.
The IPA has also reached out to members directly affected by the crisis and will offer support as required.
CPA Australia is currently in the midst of updating its online disaster recovery toolkit for businesses, with information to guide advisers on aspects to consider immediately following the disaster and steps to developing a recovery plan.
A CPA spokesperson said a number of other initiatives were currently being considered and would be announced shortly.
Not has the ongoing impact of the bushfires been lost on the profession itself, with firms and practitioners coming together to offer various forms of professional support.
Jotham Lian
07 January 2020
accountantsdaily.com.au
Helping your business survive a natural disaster – ATO
Australia has experienced more natural disasters in the last few months, and over a greater area of the country, than ever before in such a short period of time.
The ATO, to its credit, has responded quickly and their efforts have helped accountants and financial planners offer support and assistance to their clients through these very tough times.
In Australia, natural disasters such as floods, bushfires or storms can strike without warning. You can make sure your business is prepared by planning how your business might recover from a natural disaster.
If you are affected by a disaster or major incident, we, the ATO, understand that dealing with your tax affairs may not be a priority. We will give you time to deal with your more immediate problems first and can work with your accountant or help you directly to sort out your tax affairs later. Where your tax records have been damaged or destroyed, we, the ATO, can help you to reconstruct them.
We can also provide support by giving you more time to lodge, pay and respond.
If you or your business is affected by a disaster and you need further assistance, phone your accountant, or the ATO on 1800 806 218.
Find out about:
The Australian Taxation Office (ATO)
Single Touch Payroll (STP) – now ensure super is paid on time.
Single Touch Payroll (STP) will connect you to the Australian Taxation Office through your payroll software.
Each time you run your payroll and pay your staff, you will be sending your employee’s salaries and wages, Pay as You Go withholding and superannuation, to the ATO at the same time.
Superannuation funds will report to the ATO when they receive your employee’s superannuation contribution.
The ATO will know if you are now paying your workers their superannuation entitlements ON TIME, and strong compliance action will follow.
The payment deadlines cannot afford to be avoided.
AcctWeb
Beware of Australian Taxation Office (ATO) impersonation scams
The ATO warns taxpayers to be alert to malicious scammers who are using increasingly sophisticated methods and technology to impersonate the ATO.
A new tactic on the rise is “spoofing”, where scammers mimic a legitimate ATO phone number caller ID to call or send SMS messages, or mimic a legitimate email domain to send emails.
SMSs and emails may ask you to click on a link and provide your personal details to get a “refund” from the ATO. Scammers may also say you need to pay a (fake) tax debt. The ATO warns that these scammers may intend to steal not only your money, but also your identity by using your personal information.
If you’re not sure whether a communication is really from the ATO, don’t respond, don’t click any links and don’t open any attachments. Quickly hang up. You could call us. Alternatively, call the ATO’s scam hotline on 1800 008 540 to check its legitimacy.
On form of protection (if you remember) is that ANY communication with the ATO is via us – your tax agent.
AcctWeb
Bushfires 2019–20 (ATO
Devastating bushfires have been burning across large parts of Australia since November 2019.
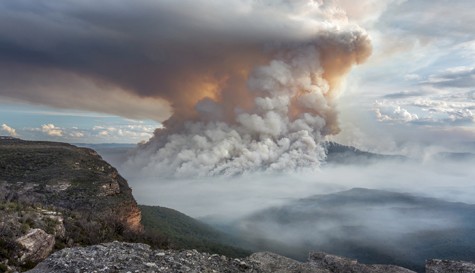
Important Information.
The bushfires have had a major impact on a large number of Australians and the trauma and devastation can't be overstated. The ATO has already released a website update that outlines how it is helping those effected. Accounting bodies and your accountant are also ready to help.
Also just released by the ATO is information about an automatic two-month deferral for lodgements and payments to those impacted by the ongoing bushfire crisis. Identified impacted postcodes across New South Wales, Victoria, Queensland, and South Australia will be granted an automatic two-month deferral for activity statement lodgments and payments due. Taxpayers or their agents do not need to apply for a deferral.
Read more …
ATO
Client Alert – December 2019

ATO debts may affect your credit rating
Businesses with tax debts need to be aware that the ATO will now be able to disclose the details of their tax debts to credit ratings agencies, which could potentially affect the ability of the business to obtain finance or refinance existing debt.
Generally, only businesses with an ABN and debts over $100,000 and that are not “effectively engaged” with the ATO will be affected. The ATO is planning a phased implementation which will consist of undertaking education efforts before it targets companies, followed by partnerships, trusts and sole traders.
The aim of the laws, according to the government, is to encourage more informed decision-making within the business community by making large overdue tax debts more visible, and to reduce the unfair advantage obtained by businesses that do not pay their tax on time.
Tip: Are you unsure if you have a tax debt, or perhaps you need help with working out a payment plan with the ATO for your existing debt? We can help you with all of this and more.
Crowdfunding: is it income?
Crowdfunding has fast become a go-to strategy for people in need of large amounts of money quickly, but is the money raised considered to be income and therefore taxable?
Crowdfunding is when an individual or business (the promoter) uploads a description of a campaign (e.g. to fund an activity, a project or a new invention) along with the amount they want to raise to a platform like Kickstarter, GoFundMe, Indiegogo or Pozible.
Other people online (the contributors) can then choose to support the campaign or cause by pledging money.
Many campaigns are donation-based. This is where contributors pledge an amount of money without receiving anything in return. If you’re a contributor in this case, you won’t be able to deduct an amount contributed in a crowdfunding campaign as a “donation” in your Australian tax return unless the cause you’ve donated to is an endorsed or legislated deductible gift recipient (DGR).
Other campaigns can be rewards-based. In these cases, the promoter provides a reward, such as goods, services or rights, to contributors in return for their payments. For example, differing levels of campaign-related merchandise may be available. Usually, your acquisition of goods or services for making a contribution means the payment is considered private in nature and not deductible.
As the promoter of a campaign (either donation-based or rewards-based), whether the money you receive is considered to be taxable depends on the circumstances. Generally, if the campaign is related to running/furthering your business or is a profit-making plan, then any money received would be classed as income.
Tip: If you’re thinking of starting a crowdfunding campaign or have already had success with one, we can help you deal with all the tax consequences, so you can concentrate on making your business or project a success.
Non-commercial losses: do the rules apply to you?
If you have a business in addition to your main employment, the non-commercial loss rules could apply to you, which may prevent you from deducting your business losses against your other income.
Depending on your business activity, as long as you satisfy certain conditions your business will not be subject to the non-commercial loss rules. If your business doesn’t satisfy these conditions, don’t worry – you can also apply to the ATO for an exemption under certain circumstances.
A “non-commercial” business activity in this context is any business where the deductions exceed the assessable income in any particular year.
If you’re a primary producer or a professional artist and your income from other sources unrelated to the business is less than $40,000, the non-commercial loss rules will not apply to you. You will be able to deduct any losses from the business against your other income, but you should be aware of the $40,000 threshold, which may change from year to year based on your personal circumstances.
Tip: If you get the bulk of your income from being an employee and run a business on the side, we can help you figure out if you’re subject to the non-commercial loss rules. We can also help make a formal request to the ATO to allow you an exemption from the rules.
Less tax for some working holiday makers?
The working holiday tax rate (commonly known as the “backpacker tax”) has generally applied from 1 January 2017 to individuals who have working holiday or work and holiday visas. In essence, the first $37,000 of “working holiday taxable income” is taxed at 15%, and then the balance is taxed at the standard rates applicable to residents.
Thus, working holiday makers are taxed at a higher rate on their first $37,000 than residents, because the holiday makers don’t get the benefit of the Australian tax-free threshold ($18,200 for 2019–2020).
A recent Federal Court case centred on a British citizen who lived in Australia for almost two years. During most of that time she lived in the same share house accommodation in Sydney, and only left for short stints to travel to other areas. Essentially, the case came down to whether or not she was a resident of Australia and if so, whether the non-discrimination clause in the Australia–United Kingdom double taxation agreement prevented her from being taxed at the higher “backpacker” rate. The Federal Court found that she was an Australian resident for tax purposes, and she should not be taxed at the higher rate.
Some have seen this decision as a win for all working holiday makers, but it’s likely to have a fairly narrow application. Coupled with the ATO still considering an appeal, this area of law is far from settled.
Tip: If you’re unsure whether this decision affects you, we can help you work out whether you’re a tax resident and may be eligible to pay less tax on your working holiday income.
Tax relief for drought-stricken farmers
With drought sweeping across the country, farmers are being offered access to concessional loans, grants and special allowances to help ease the immediate financial burden. While it is difficult to predict when the drought will break, for those who are in the process of navigating their way out of immediate financial strain, there are ways to future proof your farm or primary production business by taking advantage of various tax concessions.
Some of the immediate assistance measures include concessional loans and the farm household allowance, through which lump sum payments of up to $12,000 can be paid to eligible farm households.
The allowance can also be in the form of fortnightly payments for a maximum period of four cumulative years at the same rate as the Newstart allowance. This allowance may be available to both the farmer and their partner, provided certain conditions are met. An activity supplement of up to $4,000 to pay for study, training or professional financial advice may also be available to eligible households.
In addition to the immediate assistance, primary producers can obtain ongoing benefits of various tax concessions, including the instant asset write-off, immediate deductions for fodder storage assets, and income averaging to assist with cash flow.
Tip: If you’re experiencing hardship due to drought, we can contact the ATO on your behalf or assist with your application for farm household allowance to ease the immediate financial burden.
Super guarantee opt-out for high income earners
Under the superannuation guarantee framework, employers are required to contribute a minimum percentage (currently 9.5%) of their employees’ ordinary time earnings into superannuation. Employers that fail to do so will be liable for a penalty called the superannuation guarantee charge, payable to the ATO. If you’re a high-income earner with multiple employers, this requirement has the very real chance of pushing you over the concessional contributions cap of $25,000.
To avoid this unintended consequence, laws have recently been passed so that eligible high-income earners with multiple employers can opt out of the super guarantee regime. From 1 January 2020, employees with more than one employer who expect their combined employers’ contributions to exceed the concessional contributions cap can apply for an “employer shortfall exemption certificate” with the ATO.
Tip: It’s a good idea to speak to your employers before deciding to apply for an exemption certificate, as it may impact relevant awards or your workplace agreements.
How the gig economy could create hidden tax issues for contractors and employers
Workers and employers are benefiting from the burgeoning gig economy in which people work part-time or on a project basis, often for a stable of employers.
However, this is creating some uncertainty around whether people are independent contractors or employees, or a hybrid of both.
Misinterpreting the arrangements can lead to inadvertent breaches of various legislation, as was demonstrated in the Fair Work Commission’s decision in Joshua Klooger v Foodora Australia Pty Ltd [2018] FWC 6836.
While Mr Klooger had entered into an independent contractor agreement with Foodora that stipulated he was a contractor and not an employee, the Fair Work Commission found that he was, in fact, an employee based on the “totality of the relationship”. This meant Mr Klooger had been unfairly dismissed and was entitled to compensation.
Furthermore, the tax authorities swooped after the decision, finding that payroll tax obligations existed, as well as other employment tax obligations such as pay-as-you-go withholding (PAYGW), superannuation and personal services income (PSI).
These decisions meant that Foodora was liable for millions of dollars of potentially unpaid withholding taxes and superannuation. Compounding the problem, the decision of the Fair Work Commission effectively changed the flow of income for both Foodora and its workers. The cumulative impact meant that the German-founded food delivery business had to leave Australia.
Instead of the independent receiving all the income and paying an amount to the digital platform provider, the result is now that the digital platform provider receives all the income and pays some of that to its employees. While this may not change the bottom line for either, the implications across a range of stakeholders including banks, government departments and auditors are significant.
Tax authorities in Australia have been grappling with this issue for many years and, to date, no attempts to solve the problem have been effective. The Foodora example illustrates the potential pitfalls for many businesses when it comes to embracing the gig economy. The line between independent contractors and employees remains murky, which could affect businesses in a range of different industries.
Contractors are not technically employees of the business, so they usually get paid by issuing the business an invoice for their services and then pay their own superannuation, tax instalments and liability insurance, as well as any other costs of doing business.
This common example of a relationship between a contractor and a business has generally been accepted by the Australian Taxation Office (ATO), but the Foodora case could lead to changes. If the ATO were to take the view that these relationships were, in fact, employee relationships, then there would be a large number of contractors and businesses that would need to reconsider their tax structures and affairs.
This could mean significant out-of-pocket expenses for businesses as they would need to pay wages to their employees, pay the superannuation guarantee charge (SCG), allow for leave entitlements and ensure their insurances covered their employees.
The contractors themselves would have their tax affairs simplified but would also be unable to continue claiming certain tax deductions or splitting income through certain tax structures.
If the contractor and business elected to continue with the current independent contractor arrangement, the ATO may seek to review the arrangement with the following outcomes:
- Request the business pay an applicable outstanding SGC to the contractor’s superannuation fund. As this would be late-paid superannuation, no tax deduction would be allowed for the payment.
- Charge a 10 per cent interest rate and quarterly administration fees on the unpaid SGC amounts.
- Amend the contractor’s income tax return under the personal services income (PSI) provisions to disallow certain deductions and income splitting.
These developments mean it’s critical for any business engaging independent contractors to seek expert advice to ensure they understand the issues and take all steps to ensure their business model works. Failing to do so could be catastrophic, as was illustrated by Foodora’s forced exit from the Australian market.
Tony Ince and Kane Zaknich, RSM Australia
22 November 2019
accountantsdaily.com.au
Reverse Mortgage?
Some elderly Australians are trapped asset rich, income poor. Whilst downsizing might be the smartest solution, another option is a reverse mortgage.
No income is required to qualify, however, credit providers are required by law to lend money responsibly, so not everyone will be able to obtain a reverse mortgage.
A reverse mortgage is a type of loan that has been specifically designed for seniors over the age of 62 years to borrow money using the equity in their home as security. The loan can be taken as a lump sum (for a holiday, renovation, boat, accommodation bond for aged care, etc), a regular income stream, a line of credit, or a combination of all these options.
Interest is charged like any other loan, except the borrower is not required to make repayments while they live in their home – the interest compounds over time and is added to the loan balance. The borrower remains the owner of their house and can stay in it for as long as they wish.
The loan must be repaid in full (including interest and fees) when:-
- the borrower sells their home,
- they move into permanent aged care,
- the last surviving borrower passes away.
A reverse mortgage is not the same as a house reversion scheme, where a portion of the house is sold.
The family need to understand the impact on the reduced “inheritance”.
It will not be cheap, fees will apply, it will take time, legal advice should be obtained, and expect numerous conditions. Always seek help and involve the family.
AcctWeb
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News
Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























