
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
A resource hub for our clients.
We provide 24/7 access to many extra tools and resources to help you build on what we offer concerning your tax and other financial affairs. *
Latest News. 7-9 individual articles every month and all chosen for their relevance. Our website is a great place to stay informed.
Educational Videos. All are relevant, interesting, educational and interesting. Videos that are changed three times a year to ensure you and your family are able to lean about many issues related financial issues and topics.
Calculators. A good comprehensive range of calculators to help you better understand and manage your personal and family financial issues. Four of the more popular are: Pay calculator, Budget Calculator, Loan Calculator, and Superannuation Calculator
Client Portals. Portals are quite common on many sites and can be used to store your data, pay bills, log onto investment systems.
Ask us a question at any time. If you have a question on any related topic then don’t hesitate to use a form on our site to ask.
Your information is private and confidential and should be treated that way. Using Secure File transfer means your information is encrypted when sent in either direction over the Internet.
Many sites also have a message window feature that displays messages of interest or that cover topics and deadlines you should be aware of.
Your Accountant
* Not all are on every website.
Absentee Property Owner – Tax Whack – Victoria
The State of Victoria State Revenue Office (SRO) coffers must be bulging from land tax imposed on absentee owners.
As a simple illustration for land with a site value of $3m normal land tax would be $24,975 p.a. but if the owner is non-resident, tax is $84,975 p.a.
An absentee individual is any individual who:-
- is not an Australian citizen or permanent resident
- does not ordinarily reside in Australia, and
- was absent from Australia
- on 31 December of the year prior to the tax year, or
- for more than six months in total in the calendar year prior to the tax year.
An absentee corporation is a corporation:
- that is incorporated outside Australia, or
- in which an absentee person(s) has a controlling interest.
An absentee trust can have at least one beneficiary who is an absentee person.
This 20% tax will significantly exceeds any rental income – great care is needed if potentially relevant. And the obligation is on the owner to advise SRO of their absentee status.
AcctWeb
Australian Taxation Office (ATO) debts may affect your credit rating
Businesses with tax debts need to be aware that the ATO will now be able to disclose the details of their tax debts to credit ratings agencies, which could potentially affect the ability of the business to obtain finance or refinance existing debt.
Generally, only businesses with an ABN and debts over $100,000 and that are not “effectively engaged” with the ATO will be affected. The ATO is planning a phased implementation which will consist of undertaking education efforts before it targets companies, followed by partnerships, trusts and sole traders.
The aim of the laws, according to the government, is to encourage more informed decision-making within the business community by making large overdue tax debts more visible, and to reduce the unfair advantage obtained by businesses that do not pay their tax on time.
As always, communication is the best action so working out a payment plan with ATO will mean you are “engaged” and should not be listed.
AcctWeb
Risks when dating documents in 2020
Do you use the short form year when dating documents?
The risk is that formatting the date as DD/MM/YY leaves the year able to be altered by the adding of two digits after the ‘20’ to (fraudulently) post or pre-date the document.
It would be wiser, as a standard habit to always write ‘2020’ in full when dating documents. Doing so means the date cannot be altered or manipulated.
AcctWeb
ATO expands small business review pilot
‘Not interested in dragging disputes out’: The ATO has stopped short of making its small business independent review service a permanent feature as it expands and extends the pilot program until the end of the year.
The ATO’s independent review service trial for small businesses will now be extended to 31 December 2020 and expanded to include disputes involving GST, excise, luxury car tax (LCT), wine equalisation tax (WET) and fuel tax credits (FTC).
Launched by commissioner Chris Jordan on 1 July 2018, the pilot program had initially only considered disputes involving income tax audits and was set to run for only 12 months.
With 138 small businesses having taken up the offer since the pilot began, ATO deputy commissioner Scott Treatt said its early success had prompted the Tax Office to expand the pilot.
“Pleasingly, we’ve only received two objections from businesses that have been through our independent review pilot since it launched on 1 July 2018. This result demonstrates that our pilot program is working as intended for small business in that it’s helping to resolve disputes prior to matters reaching objection,” Mr Treatt told Accountants Daily.
“We proactively invite small businesses to take advantage of the service when we issue an audit finalisation letter. We’ve found that the service is helping us resolve disputes with small businesses earlier.
“Our officers will make every effort to resolve disputes as quickly as possible. We are not interested in dragging disputes out.”
The independent review process had been previously reserved for entities with a turnover greater than $250 million.
The pilot program will see eligible small businesses with an audit in progress be contacted by their audit case officer with the offer of a review before issuing assessments.
According to Mr Treatt, small businesses can expect an independent officer from outside its audit area to review the facts and technical merits of the ATO’s audit position.
The most common issues that small businesses have asked for a review into to date includes omitted cash income, usually due to inadequate record keeping; administrative penalties; deductibility of business expenses; and characterisation of payments to related individuals.
Disputes over superannuation, fringe benefits tax, fraud and evasion findings, and interest will not be considered by the independent review service at this stage.
Jotham Lian
28 February 2020
accountantsdaily.com.au
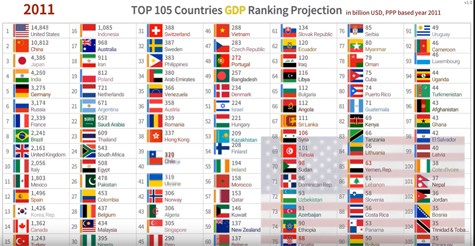
Expected GDP by country 2010 to 2100
This animated chart is simply amazing but some world events could have a negative impact. Even so, it's fascinating to see how the world might change into the future.
Simply click on the image and see how global economies are expected to change between 2010 and 2100.
SG amnesty bill passes Parliament
The long-awaited superannuation guarantee amnesty bill has now passed both houses, with employers set to get six months to disclose historical non-compliance before tougher penalties apply.
The Treasury Laws Amendment (Recovering Unpaid Superannuation) Bill 2019 has now been passed and is awaiting royal assent.
The SG amnesty provides for a one-off amnesty to encourage employers to self-correct historical SG non-compliance dating from 1 July 1992 to 31 March 2018.
An employer will not be able to benefit from the amnesty for SG shortfall relating to the quarter starting on 1 April 2018 or subsequent quarters.
It will allow employers to claim tax deductions for payments of SG charge or contributions made during the amnesty period to offset SG charge, as well as remove the administrative component and the Part 7 penalty that may otherwise apply in relation to SG non-compliance.
The amnesty period will start from 24 May 2018 and end six months from the date it receives royal assent.
The new legislation will also impose minimum penalties on employers who fail to come forward during the amnesty period by limiting the commissioner’s ability to remit penalties below 100 per cent of the amount of SG charge payable.
Around 7,000 employers have since come forward to voluntarily disclose historical unpaid super since the amnesty was first announced on 24 May 2018.
Treasury estimates an additional 7,000 employers will come forward during the six-month amnesty period, returning $230 million of superannuation to employees who may have otherwise completely missed out.
Assistant Minister for Superannuation, Financial Services and Financial Technology Jane Hume said the passing of the legislation should not be viewed as giving a free kick to employers who had been previously non-compliant.
“Employers will not be off the hook. To use the amnesty, they must still pay all that is owing to their employees, including the high rate of interest. However, the amnesty will make it easier for workers to secure the super they are owed by not hitting employers with the penalties usually associated with late payment,” said Ms Hume.
“If employers do not take advantage of the amnesty, they will now face significantly higher penalties when they are caught. In addition, throughout the amnesty period the ATO will still continue its usual audit and enforcement activity against employers for historical obligations they do not own up to voluntarily.
“We encourage employers to check they don’t owe outstanding super — and if they do, to take advantage of this once-only opportunity to set things right before much tougher penalties apply.”
Jotham Lian
24 February 2020
accountantsdaily.com.au
ATO flags most common SMSF return mistakes
The Australian Taxation Office has revealed the top five most frequent errors made in the submission of SMSF annual returns as well as how advisers can avoid them when lodging this year.
A bank account that isn’t unique to the SMSF
The ATO said there must be a bank account in the fund’s name to manage the SMSF operations and to accept contributions, rollovers of super and income from investments.
Further, it said the account must be separate from the trustees’ individual bank accounts and any related employers’ or advisers’ bank accounts.
“This will protect your fund’s assets and ensure super payments can be made to your SMSF,” the ATO said.
Providing an incorrect electronic service address (ESA)
The ATO said an ESA allows an SMSF to receive electronic remittance advice and contributions if it has members receiving super from non-related employers. Therefore, it’s not an email address or the contact details of the SMSF messaging provider.
“An ESA consists of alphanumeric characters with a combination of upper and lower-case characters and is case sensitive,” the Tax Office said.
Not valuing an SMSF’s assets at market value
The Tax Office noted that SMSF assets need to be calculated at market value as at 30 June to prepare the fund’s accounts, statements and SAR.
“If you follow our valuation guidelines, we’ll generally accept the valuation you provide,” the ATO said.
“Accurate asset valuation is important to ensure your SMSF retains its complying fund status. Penalties may apply for inaccurate valuations as these can have an impact on your members’ balances.”
Trying to lodge with zero assets
The ATO said an SMSF is not legally established until the fund has assets set aside for the benefit of members. As a result, the regulator said it won’t accept a SAR from an SMSF that has no assets unless the fund is being wound up.
“If this is your SMSF’s first year and you have no assets set aside for the benefit of members, you can ask us to either cancel your fund’s registration or flag the SMSF’s record as return not necessary (RNN),” it said.
Lodging an SAR without auditor details
An approved auditor examines an SMSF’s financial statements and assesses the fund’s compliance with super law, meaning an audit must be completed before your SAR can be lodged, according to the ATO.
“A SAR lodged without auditor’s details will be suspended and not recognised as a lodgment. This will impact the complying status of the fund until the SAR is lodged with the required information,” the ATO said.
“Appoint an auditor at least 45 days before your SAR is due to ensure the audit is completed in time to meet the lodgment date.”
Adrian Flores
26 February 2020
accountantsdaily.com.au
Client Alert – March 2020

Super guarantee loopholes closed
The concept of a superannuation guarantee – the legal requirement for your employer to contribute 9.5% of your salary into a nominated super account – should be familiar to everyone, as it makes up the bulk of most people’s future retirement income. You may also salary-sacrifice amounts of your salary to put extra into your super.
Until recently, loopholes in the law meant that your employer could count your salary-sacrificed amounts towards their super guarantee contribution amounts – essentially working against your intention to boost your super. Employers could also calculate their super guarantee obligations based on your post-sacrifice earnings rather than on your full pre-sacrifice earnings.
Depending on your employment agreement, these loopholes meant that if you salary-sacrificed an amount equal to or more than your employer’s super guarantee amount, your employer could choose to not contribute any amount and the legal requirements of the super guarantee would still be met.
TIP: It’s important to note that this wasn’t the original intention of the law, and not all employers would choose to exploit these loopholes. However, where they did, employees who salary-sacrificed could be short-changed and end up with lower super contributions as well as a lower salary overall.
The good news is that the law has now been changed. From 1 January 2020, amounts that you salary-sacrifice to super can’t be used to reduce your employer’s super guarantee obligations, and employers must calculate their super guarantee obligations based on all of your ordinary time earnings (OTE), including any amounts you sacrifice into superannuation that would have otherwise been OTE.
ATO tackling international tax evasion
Australian tax residents are taxed in Australia on their worldwide income. While most do the right thing and declare all their income, some people and businesses try to avoid paying tax by exploiting secrecy provisions and information-sharing gaps between countries.
A recent coordinated effort by the Joint Chiefs of Global Tax Enforcement (J5) has yielded evidence of tax evasion by Australians. The J5 consists of the tax and revenue agencies of Australia, the United Kingdom, the United States, Canada and the Netherlands and was initially formed in 2018 to fight global tax evasion. The countries share intelligence on international tax crime as well as money laundering.
According to the ATO, several hundred Australians are suspected of participating in arrangements with an international financial institution in Central America whose products and services are believed to be facilitating worldwide money laundering and tax evasion. Multiple investigations are currently under way, and anyone with information about the scheme or other similar arrangements is encouraged to contact the ATO.
The ATO has a network of international tax treaties and information exchange agreements with over 100 jurisdictions. In recent years over 2,500 exchanges of information have occurred, enabling the ATO to identify unpaid tax amounts totalling $1 billion.
TIP: The message from the ATO is that anyone with offshore income or assets is better off declaring their interests voluntarily. Those who do so may be eligible for reductions in related administrative penalties and interest charges.
New measures to combat illegal phoenixing
New laws are now in place to target illegal phoenixing of companies in Australia.
Phoenix activity is when a new company is created – “rising from the ashes” of another company that was in debt and has been deliberately liquidated – to continue the business of the old company while avoiding having to pay its debts. Recent estimates are that illegal phoenix activity directly costs Australian businesses, employees and governments between $2.85 billion and $5.13 billion each year.
To combat this type of debt and tax evasion, the new laws target a range of behaviours, including preventing property transfers to defeat creditors, improving the accountability requirements for resigning company directors, allowing the ATO to collect estimates of anticipated GST liabilities and authorising the ATO to retain tax refunds where lodgements are outstanding.
Insurance payouts: are they taxable?
In recent months, parts of Australia have been battered by a combination of fire and floods. As people try to piece their lives together in the aftermath, insurance payouts can go a long way in helping rebuild homes and replace lost items.
However, if you receive an insurance payout in relation to your business, home business or rental property you need to be aware there may be associated tax consequences. For example, if you keep a home office or run a business from home, or make money from renting out your home on a short-stay website, you may be subject to capital gains tax (CGT) when receiving an insurance payout on the home.
Businesses that receive an insurance payment may be subject to varying tax consequences depending on what the payment is designed to replace.
Tip: If you’ve recently received an insurance payment or you’re expecting one, contact us to find out more about how your tax obligations could be affected.
Australia’s independent tax complaints investigator
Do you know who to turn to when you have a complaint about the ATO? Whether you’re an individual or business, the Inspector-General of Taxation and Taxation Ombudsman (IGTO) should be your first port of call.
As the Taxation Ombudsman, the IGTO provides all taxpayers with an independent complaints investigation service. As the Inspector-General of Taxation, it also conducts reviews and provides independent advice and recommendations to government, ATO and other departments.
The IGTO can investigate and assist with issues including extensions of time to pay; the ATO’s debt recovery actions; delays with processing tax returns; delays in ATO communication and responses; information the ATO has considered regarding taxpayers’ matters; understanding the ATO’s actions and decisions; and identifying available options and other relevant agencies that can help.
Complaints can be made online and via phone or post, and services are offered in languages other than English as well as for people who are hearing, sight or speech impaired.
ATO scrutiny on car parking fringe benefits
The ATO has started contacting certain employers that provide car parking fringe benefits to their employees to ensure that all fringe benefits tax (FBT) obligations are being met. Generally, car parking fringe benefits arise where the car is parked on the business premises of the entity, used by the employee to travel between home and their primary place of employment and is parked for more than four hours between 7 am and 7 pm, and where a commercial parking station located within 1 km of the premises charges more than the car parking threshold amount.
Employers have a choice of three methods to calculate the taxable value of the benefits: the commercial parking station method, the average cost method and the market value method. The method currently under ATO scrutiny is the market value method, which states that the taxable value of a car parking benefit is the amount that the recipient could reasonably be expected to have to pay if the provider and the recipient were dealing with each other under arm’s length conditions.
Foreign residents and the main residence exemption
Laws limiting foreign residents’ ability to claim the CGT main residence exemption are now in place. This means that if you’re a foreign resident for tax purposes at the time you sign a contract to sell a property that was your main residence, you may be liable for tens of thousands of dollars in CGT. Some limited exemptions apply for “life events”, as well as property purchased before 9 May 2017 and disposed of before 30 June 2020.
According to the ATO, a person’s residency status in earlier income years will not be relevant and there will be no partial CGT main residence exemption. Therefore, not only are current foreign residents affected, but current Australian residents who are thinking of spending extended periods overseas for work or other purposes may also need to factor in this change to any plans related to selling a main residence while overseas.
CHANGES TO XERO PRICING PLANS
For all our clients who currently hold a Xero subscription, we would like to inform you that from the 18th of March 2020 Xero are increasing their subscription fees by $2 per month.
If you currently hold your Xero subscription with Guests you will notice the $2 increase in your first monthly invoice issued after the 18th March.
SOME USEFUL LINKS
Here are some information links to help understand these changes:
Xero pricing and plans update
https://www.xero.com/blog/2018/11/xero-pricing-and-plan-update/
Changes to Starter, Standard and Premium plan pricing in Australia
https://www.xero.com/au/pricing/update/
If you have any questions about this increase, please do not hesitate to reach out to us via phone on 9509 7033 or by email nb@guests.com.au

Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News
Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























