
- 234 Balaclava Road, Caulfield North VIC 3161
- contactus@guests.com.au
- (03) 9509 7033
ATO Small Business Newsroom – May / June
The ATO provides information on a large number of business related topics, issues, rules and regulations. We hope this article will help quickly you keep up to date.
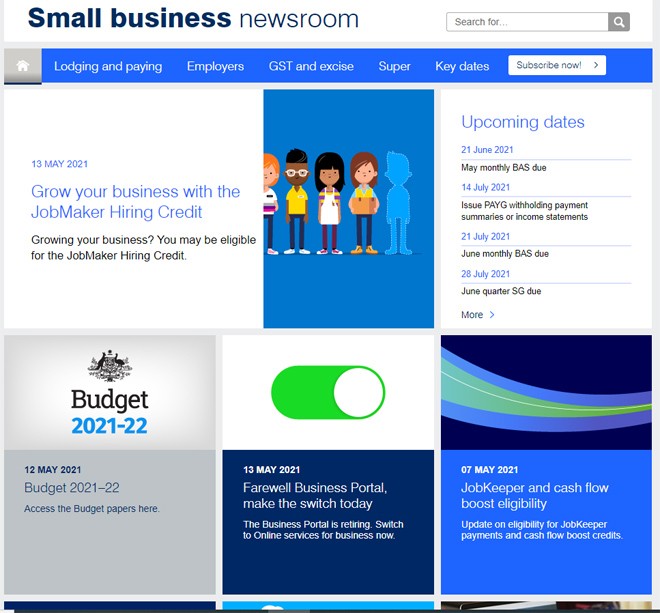
Visiting the ATO's website can be daunting but here is a page that links to information important to small businesses everywhere.
For example:
- Upcoming dates
- Grow your business with the JobMaker Hiring Credit
- Budget 2021–22
- Farewell Business Portal, make the switch today
- JobKeeper and cash flow boost eligibility
- More ….
Click here to access this resource.
ATO
Videos to help understand accounting topics.
Often watching a short video is a quicker way to understand what can otherwise be quite confusing. The following titles have just been added to our website and can be accessed at any time and by anyone.
In our site's menu you will find a link to our updated range of videos on the following topics.
- Understanding SMSFs
- Tips for getting your client bills paid on time
- Managing redundancy
- Update your will
- Planning to succeed.
- Individual Trustees vs Corporate Trustees
Closely held payees: STP options for small employers
Small employers with closely held payees have been exempt from reporting through single touch payroll (STP).
However, they must begin STP reporting from 1 July 2021.
Small employers must continue to report information about all of their other employees (known as “arm's length employees”) via STP on or before each pay day (the statutory due date). Small employers that only have closely held employees are not required to start STP reporting until 1 July 2021, and there’s no requirement to advise the ATO if you’re a small employer that only has closely held payees.
If your business will need to lodge through STP soon, we can help you find an easy and cost-effective STP-enabled solution, or we can lodge on your behalf. Whatever you choose, remember that STP reports can’t be lodged through ATO online services and isn’t a label on your Business Activity Statement, so early preparation is needed.
AcctWeb
End of year financial strategies
With the end of the financial year approaching there may be some valuable opportunities worth discussing for you or your family, depending on your personal circumstances.
Contributions review
As always there are two concerns here, especially if you wish to maximise the contributions made and the dangers of going over concessional (CC) or non-concessional contribution (NCC) caps.
For concessional contributions, there is a universal standard cap of $25,000 that applies if you qualify. But if the total super balance (TSB) on 30 June 2020 is less than $500,000, you can have the benefit of carrying forward any unused concessional contributions. These are the concessional contributions under the cap that haven’t been fully used since 1 July 2018.
Time frames are always important if you wish to claim a tax deduction for personal concessional contributions. An election must be made within your SMSF, setting out the amount being claimed, and must be lodged with the fund. This must be done before personal tax returns are sent to the ATO for the 2021 financial year and no later than the end of the financial year after the contribution was made. Remember, there’s a bit of a twist as you need to lodge the notice with the fund before any part of the contribution is withdrawn or used to start a pension. The SMSF also needs to acknowledge its election before you lodge the income tax return.
A major consideration in making non-concessional contributions (NCC), which are not tax-deductible, is the amount of an investor’s TSB. The TSB determines the amount that can be contributed to an SMSF without facing a tax penalty. If a TSB is more than $1.6 million, a penalty will apply to any NCC made and this may mean even having to withdraw any excess.
If you have a TSB of less than $1.6 million, and qualify to make an NCC into your SMSF, you may be able to immediately make up to $300,000 over a fixed three-year period. The standard NCC is $100,000, but for anyone under 65 it is possible to bring forward up to the next two years’ standard NCC if you have a TSB of less than $1.5 million. If a TSB is less than $1.4 million, you can bring forward the next two years’ standard NCC and if it is between $1.4 million and $1.5 million, you can bring forward just one year’s standard NCC.
If you have triggered the bring-forward rule in either 2018/19 or 2019/20, then the total NCC may be either $300,000 or $200,000 respectively, provided the maximum TSB has not been exceeded as at 30 June 2020.
Indexation of caps – strategy
From 1 July 2021, the TSB will increase to $1.7 million and the standard NCC will rise to $110,000. Those under 65, thinking of using the bring-forward provisions this financial year, may wish to seek further advice to see what can provide the greatest benefit. Where the amount of the caps changes, there are nearly always strategic advantages from the timing of NCCs. For example, there may be advantages in making some contributions in late June and taking advantage of the indexed amounts from 1 July this year.
Accessing the Government co-contribution
Individuals with assessable income (2) of below $54,838 may qualify for the government co-contribution of up to $500 if they make a non-concessional contribution of $1,000 before 30 June 2021. To qualify for the co-contribution:
- at least 10% of assessable income must be received from employment or a self-employment arrangement
- the individual must be below age 71 at the end of the financial year
- they must have Total Superannuation Balance of less than $1.6m on 30 June 2020 and;
- they must lodge a tax return for the 2020/21 income year
Make a spouse contribution
Couples with one spouse earning a low income or no income, may benefit from the spouse tax offset if the high-income earner makes a spouse contribution into the low-income earner spouse’s superannuation. The maximum offset that can be claimed is $540 where the low-income earner spouse’s income is below $37,000 (3) and $3,000 is contributed before 30 June. As well as the tax benefit available to the high-income earner spouse, the strategy can also help to build up superannuation savings for the low-income earner spouse.
Contributions splitting
Another way to increase a spouse’s super is implementing the contribution splitting strategy. The strategy allows eligible spouses (married or de facto) to split up to 85% of concessional contributions (including mandatory employer contributions) made in the prior financial year. The split must occur before the end of the following year, i.e. 30 June 2021 is the deadline for splitting concessional contributions made in the 2019/20 income year.
First Home Super Saver Scheme
Individuals saving for their first home may benefit from making voluntary contributions to super before 30 June. The FHSS Scheme allows first home buyers to make voluntary contributions of up to $15,000 to superannuation per financial year while saving towards the deposit in a tax-effective environment. After contributing for a couple of years, they can withdraw these contributions (up to $30,000 per individual being increased to $50,000 from 1 July 2022) and use the proceeds towards the acquisition of their first home.
SMSF Contribution Reserving
This strategy allows SMSF members to make personal deductible contributions over the annual cap in June and claim larger tax deduction for the current year.
SMSF meeting the minimum pension requirement
SMSF Trustees with members in the retirement income phase must ensure the minimum pension requirement is met before the 30th of June. Otherwise, the income stream will be taken to have ceased for income tax purposes at the start of the year and the SMSF will lose the eligibility to claim the tax-free earnings for that year.
Downsizer Contributions
This strategy allows people who are aged over 65 (reducing to 60 from 1 July 2022) who are selling a residence they have lived in for ten years to contribute $300,000 each to superannuation within 90 days of settlement without the normal restrictions on contributions. There is no age limit.
Investment strategy review
Ensuring an investment strategy accurately reflects a SMSF’s current asset allocation is an important compliance responsibility. While there is a degree of flexibility with respect to movements in overall asset allocation, it is good practice to review the current asset allocation against the documented strategy. If the fund’s current allocation falls outside the documented strategy, you may wish to make an adjustment to either so they fall back into line.
Some of the more common situations where SMSF investment strategies should be reviewed include:
- trustees purchasing property for their fund, but not updating the investment strategy to reflect the purchase,
- an asset class, such as listed shares, being over the fund’s target position due to significant rises or falls in the underlying holdings,
- trustees moving from accumulation to pension phase and changing asset allocation due to cash-flow needs, but neglecting an investment strategy update, and
- trustees choosing to invest in predominantly one asset or asset class – 90 per cent or more of the fund – can lead to concentration risk.
- In this situation, a fund’s investment strategy needs to document how the trustees have considered the risks associated with a lack of investment diversification. This should include how high concentrations of assets can meet the fund’s investment objectives, including predicted returns and cash-flow requirements.
Asset concentration risk is heightened in leveraged funds, especially where the fund has used a limited recourse borrowing arrangement to acquire the asset. This can expose members to a loss in the value of their retirement savings should the asset decline in value. It could also trigger a forced asset sale if loan covenants (for example, the loan-to-valuation ratio) are breached.
Capital gains tax review
In the lead-up to the end of the financial year, trustees or advisers may wish to undertake tax planning to minimise the capital gains tax position of their SMSF. This is usual where an SMSF has assets with an unrealised loss position. Trustees may seek advice on whether it is worthwhile to crystallise the unrealised losses to reduce any of the fund’s realised gains. It’s important to understand there may be tax consequences from simply selling an asset and buying it back immediately.
Asset revaluation
One of your most important obligations is to ensure, for the purposes of preparing a fund’s financial accounts, that assets are valued at market value each year. This is a legal requirement and ensures the value of the fund assets and member balances are accurate. There are valuation implications for each member’s TSB, as well as taxing the fund’s income if it is paying pensions.
The value of some of a fund’s investments may be easy to obtain, such as listed company shares and bank account balances. However, when it comes to real estate and other fund investments, market value may not be that obvious and a valuation may be required from an appropriately qualified person, such as an independent registered valuer or real estate agent.
For assets where a valuation is not easy to determine, it is necessary to obtain evidence to support whatever value you decide on as this will assist when the fund is audited. For more exotic assets, such as privately held unlisted shares, unit trust holdings or artworks and collectables, the matter can always be raised with a fund’s auditor to see whether the fund is on the right track.
Pension review
Make sure at least the minimum pension is paid for any existing pensions and the maximum level is not exceeded for transition-to-retirement income streams. A pension that does not satisfy the payment rules will mean any income on assets supporting the pension will be taxed at 15 per cent rather than be tax-exempt.
When deciding to draw more than the minimum pension, a client may wish to consider taking any amount over the minimum as a pension payment or as a lump sum. The reason is that lump sum commutations of a client’s pension balance will result in a reduction of their transfer balance account and can be used to access additional pension benefits in future.
Taxation
Prepay income protection premiums
Individuals holding income protection insurance outside of superannuation can prepay premiums for the next 12 months to bring forward the tax deduction to the current financial year. This may be beneficial where individual has larger than expected taxable income for the current year.
Prepay interest on an investment loan
Similar to prepaying income protection premiums, prepaying deductible interest on an investment loan before 30 June 2021 will bring forward the tax deduction to the current financial year.
Social Security
Gifting
Social security recipients wishing to gift an amount or an asset within the allowable disposal amount can do so before 30th June. These individuals can gift up to $10,000 before the 30th of June and another $10,000 after 1 July 2021, a total of up to $20,000 over June and July. Individuals in receipt of government benefits can gift up to $10,000 in a single financial year or up to $30,000 over 5 rolling financial years. However, the amount gifted in any given financial year cannot exceed $10,000 or the deprivation rules will be applied.
These are just some of the things you should be considering as you wrap up this financial year. We encourage you to contact our office to discuss if any of these strategies might suit your personal circumstances, goals and objectives.
———————————————
IMPORTANT: Certain eligibility requirements may apply to strategies listed. To avoid penalties, we strongly recommend seeking advice from your financial planner before implementing any of the strategies explained in this article. The information contained in this article is general information only. It is not intended to be a recommendation, offer, advice or invitation to purchase, sell or otherwise deal in securities or other investments. Before making any decision in respect to a financial product, you should seek advice from an appropriately qualified professional. We believe that the information contained in this document is accurate. However, we do not accept responsibility for any action that you take without confirming with us that it is suitable for your personal circumstances.
(1) Up to 30% if you earn $250,000 or more.
(2) Assessable income for this purpose includes assessable income plus reportable fringe benefits plus reportable employer contributions less business deductions.
(3) Income for this purpose includes assessable income plus reportable fringe benefits plus reportable employer contributions.
A compilation based in information from Graeme Colley (SuperConcepts) and AcctWeb, the latter being for added general EOY accounting topics.
10% Super Guarantee from 1st July 2021
Business leaders should turn their attention to how they plan on managing the government’s increase to the superannuation guarantee, set to come into effect from 1 July, to avoid penalties, says one tax expert.
An increase to the superannuation guarantee (SG) is set to go ahead from 1 July which will see the base rate rise from 9.5 per cent to 10 per cent, followed by incremental half percentage point increases each year to 12 per cent on 1 July 2025.
John Jeffreys, tax counsel at Tax & Super Australia, warns that businesses should establish their approaches to the increase early, because non-payment, underpayment and late payments of as little as 24 hours are likely to attract the attention and penalty from the ATO.
“We haven’t had guidance from the ATO about any grace period or lenience for employers who don’t meet this new SG obligation,” Mr Jeffreys said.
He said that businesses are likely to act in the interest of their bottomline, but warned that regardless of how they approach the change, they should do so with transparency and clearly communicate how their approach will impact their employees’ payslips.
“While the policy of the legislation is for the employer to contribute the extra half a per cent without impacting take-home wages, this may not be the case across all workplaces,” Mr Jeffreys said.
“As well as considering how much room they have within their profit margins, business products or activities to best cater for this increase, employers should keep in mind that this is not a one-off increase.
“They’ll need to prepare for the SG to go up 0.5 [of a percentage point] annually until it reaches 12 per cent in 2025.”
The warnings follow the release of a survey conducted by consultancy firm Mercer which looked at the steps Australian businesses are taking to prepare for the SG increase.
The results showed that, of the 145 firms surveyed, 46 per cent of respondents were still establishing a position and continue to assess the full cost of the SG increase to their organisation.
Of the businesses currently offering their staff a base-plus-super package, 62 per cent of respondents said they’d meet the full cost of the SG increase and maintain their employees’ take-home pay.
Meanwhile, almost two-thirds of the firms surveyed who have a total package arrangement in place — one where superannuation is bundled in with an employee’s salary — said that their staff would be left to bear the brunt of at least some of the cost imposed by the increase.
Australian Council of Trade Unions secretary Sally McManus told a panel discussion at an Australian Institute of Superannuation Trustees conference on Tuesday that the changes would offer employers a legal opportunity to cut the take-home salaries of their staff.
However, she expects the cohort of employees to suffer a pay cut to be small.
“There would only be some very discrete circumstances where employers could unilaterally cut people’s take-home pay on 1 July,” Ms McManus said. “That would be a very small circumstance where employers could do that, just straight out legally do that.
“The issue of low wage growth is a big structural problem unrelated to the super issue, and it would be if super was going up or if it was not going up.”
While the increase has been legislated for some time, Minister for Superannuation, Financial Services and the Digital Economy Jane Hume wavered on whether the increase could be held back by further delays as recently as March.
Speaking to ABC News Breakfast in March, Ms Hume said the SG would come “at a cost” and could result in slowed wage growth.
“Money doesn’t grow on trees and there is a good chance that if there is an additional cost to employers when they pay that extra 0.5 [of a percentage point] that it will come at the expense of potentially wage rises in the future,” Ms Hume said.
“The Prime Minister has said that he will assess the situation closer to the time based on the best information available to him at the time, the best economic information available to him at the time.”
The Morrison government’s 2021–22 federal budget didn’t include any changes to the legislated SG increase, which is set to come into effect from 1 July.
John Buckley
20 May 2021
accountantsdaily.com.au
New insolvency rules commence
The measures from 1st January 2021 apply to incorporated companies with liabilities less than $1 million.
For those businesses that are “unable to survive”, a new simplified “liquidation pathway” will apply for small businesses to allow faster and lower-cost liquidation.
To be eligible to access this new process a company must:
- have total liabilities which do not exceed $1 million on the day the company enters the process – this excludes employee entitlements;
- appoint a small business restructuring practitioner to oversee the restructuring process, including working with the business to develop a debt restructuring plan and restructuring proposal statement.
This principle has the potential to allow continuation of a longer-term successful business hit by short-term or covid cash flow difficulties.
AcctWeb
ATO promises not to ‘destroy’ businesses as it resumes debt collection
Businesses struggling with tax debts have been urged to re-engage with the ATO as it pledges not to “destroy the very thing that [it has] been trying to support” throughout the pandemic.
While the Tax Office has now confirmed that it has resumed pursuing and enforcing debt recovery, ATO second commissioner Jeremy Hirschhorn has reassured businesses that it will not go too hard too soon.
“We want people to re-engage. It’s a relatively soft engagement. We get that it’s really hard to go from nothing to full payment,” said Mr Hirschhorn at Chartered Accountants Australia and New Zealand’s Practice Power Up Conference on Wednesday.
“We are expecting a lot of payment plans to really try to get businesses gradually back fully into the system.
“But what we don’t want to do is to support companies or businesses all the way through a pandemic and then by dialling debt collection up too quickly, we destroy the very thing that we’ve been trying to support.”
The resumption of debt collection activity comes after the ATO paused its debt, audit and lodgement work at the height of COVID-19, resulting in its debt book growing by $20 billion, according to Mr Hirschhorn.
“We pivoted as an organisation, we turned off some sacred cows in the Tax Office,” he said.
“We turned off debt collection, we turned off lodgement chasing up, we really dialled back almost to no new audit activity, and gave taxpayers the opportunity to say, ‘Do I want to pause my existing compliance activity, continue it or slow it?’, so we really tried to put that in the hands of the taxpayer.”
Mr Hirschhorn said it was necessary for the ATO to now resume its business-as-usual activities, but it remained conscious of struggling businesses amid a recovering economy.
“Where we are now is really saying, look, everybody should be lodging, and the default is that everybody should be paying,” Mr Hirschhorn said.
“We recognise that it is a strange economy still, because some businesses are absolutely going gangbusters, and other businesses are really still struggling. It’s not just the obvious industries like tourism, but [for example], it’s been a fantastic time for suburban coffee shops, and a terrible time for CBD coffee shops.
“What we’re really saying is, please approach us and we’re going to be very empathetic or reasonable around debt, but we really expect you to lodge.”
Jotham Lian
23 April 2021
accountantsdaily.com.au
Taxpayers urged to keep work-from-home records
Moore Australia has called for taxpayers to keep a diligent log of the hours worked from home this financial year as tax time looms.
“Although Australia has fared well throughout COVID, our working patterns have changed in step with the rest of the world, as expected,” said David Tomasi, chairman of Moore Australia.
“It is important that Australians are aware of their entitlements under the ‘new normal’.”
While tax agents should be advising their clients on working-from-home entitlements, taxpayers should also be aware of the ATO’s shortcut method which in January was extended to 30 June this year.
“To their credit, the ATO has significantly simplified the process of claiming tax deductions related to working from home,” Mr Tomasi said.
The temporary arrangement allows taxpayers to claim a fixed rate of 80 cents an hour for all running expenses incurred as a result of working from home, as opposed to calculating costs for specific expenses.
Its introduction also saw the end of a measure which required taxpayers to have a dedicated work-from-home area, factoring in multi-person households, where each working taxpayer would now be able to claim.
“To claim home office deductions using the shortcut method, individuals need to keep a record of actual hours worked at home,” Mr Tomasi said.
“The shortcut method is not compulsory, and individuals can still claim based on actual expenses incurred.
“However, they would then have to comply with the necessary, and more complex, record-keeping requirements.”
Tax agents and self-lodgers interested in using the method will need to include a note that reads “COVID-hour rate” in their tax returns.
The method will cover a range of running expenses including electricity for lighting, cooling, heating and the running of other electronic items; phone and internet costs; and the depreciation of various items spanning computers, laptops, home office furniture, and other household fixtures that see wear as a result of a taxpayer’s working arrangements.
The Tax Office last extended its simplified working-from-home deduction method in January while New South Wales was reckoning with the containment of a COVID-19 outbreak which sent Sydney’s northern beaches into lockdown.
Introduced last April, it was first due to expire at the end of the last financial year, before it was in June extended to September last year, and then until December.
John Buckley
03 May 2021
accountantsdaily.com.au
Businesses feeling ‘adverse’ impacts of COVID-safe measures: ABS
While less than two out of 10 businesses are recording a dip in revenue, nearly two-thirds of them are still feeling the impact of COVID-safe controls, according to new data from the Australian Bureau of Statistics.
The Australian Bureau of Statistics (ABS) on Friday released the results of its latest Business Conditions and Sentiments Survey which showed that, while reported revenue decreases have fallen to just 18 per cent, many businesses remain challenged by COVID-safe controls and supply chain disruption.
Nearly 64 per cent of businesses are being “adversely impacted” by COVID-safe provisions like stringent cleaning requirements and the use of personal protective equipment (PPE) among their staff.
Of the businesses surveyed, 21 per cent of businesses said they had felt the impacts of at least one of these provisions to “a great extent”.
CreditorWatch chief economist Harley Dale said that while sparse reports of falling revenue emerge as a positive, the fact that such a large proportion of businesses are still feeling the impacts of COVID measures shows that “we are not out of the woods”.
“That is the best result since the ABS began this series in July 2020,” Mr Dale said. “It also represents the first time since December 2020 that an increase in revenue has outweighed a decrease in revenue.
“However, there is always a sting in the tail. Sixty-four per cent of businesses report COVID-related controls are still having an adverse impact on business conditions, which should be seen as a prescient warning that we are not out of the woods.”
John Shepherd, head of industry statistics at the ABS, said businesses have pivoted to adapt to changing conditions in various ways.
Some 62 per cent of business leaders said they’ve changed their ordering processes, while 41 per cent said they’d changed the way they deliver products and services to customers, and another 39 per cent said they have changed suppliers.
“Three in 10 (30 per cent) businesses are experiencing supply chain disruptions, with 37 per cent of these businesses affected to a great extent,” Mr Shepherd said.
“Another response from businesses has been to increased teleworking.
“Before COVID-19, one in five (20 per cent) businesses had staff teleworking. Currently, 30 per cent of businesses have staff teleworking, with 45 per cent of these experiencing improved staff wellbeing as a benefit.”
Pointing to the March CreditorWatch Business Risk Review, Mr Dale said that manufacturing, while still experiencing slowed productivity, could be turning a corner. He said supply disruptions highlight the risk of recoveries in these sectors slowing.
“Growth in credit is being driven by housing, according to the latest RBA stats, which is hardly surprising given government support programs,” Mr Dale said, “with owner -occupier housing credit driving the race on a three-month annualised basis.
“Contrary to some speculation, credit extended to housing investors is still not on the front grid. We need to see evidence of stronger outcomes for personal and business credit, and the CreditorWatch BRR reinforces this point.”
John Buckley
03 May 2021
accountantsdaily.com.au
ATO signals crackdown on 4 ineligible work-from-home claims
As tax time looms, the ATO has pointed to four key ineligible work-from-home claims it will be watching closely as taxpayers look to make the most of flexible working arrangements.
The ATO on Thursday urged all taxpayers to be aware that, while the temporary shortcut method will remain available to those claiming work-from-home deductions this year, personal and occupancy expenses, among others, cannot be claimed through any method.
Personal expenses like coffee, tea and toilet paper — while may be made available by some employers — aren’t directly related to earning income, and cannot be claimed by taxpayers who were forced to adapt from hybrid working arrangements last year.
Other ineligible expenses include those related to a child’s education, like online learning courses or laptops, as well as large upfront costs. Those could include any asset that costs over $300, like a computer, which can’t be claimed immediately and should instead be spread out over a number of years.
The ATO also warned that employees generally aren’t able to claim rent, mortgage interest, property insurance, or other land taxes and rates. The Tax Office said that working from home does not make a taxpayer’s home a place of business for tax purposes.
The ATO warns that claiming occupancy expenses could expose some taxpayers to capital gains tax when they leave their homes.
The temporary shortcut method, which in January was extended to 30 June this year, allows taxpayers to claim a fixed rate of 80 cents an hour for all running expenses incurred as a result of working from home, as opposed to calculating costs for specific expenses.
The method’s introduction did, however, spell the end of a measure which required taxpayers to have a dedicated work-from-home area, factoring in multi-person households, where each working taxpayer would now be able to claim.
“The shortcut method is straightforward; just multiply the hours worked at home by 80 cents,” said Tim Loh, assistant commissioner at the ATO. “The only proof you need is a record of the number of hours you’ve worked from home, such as a timesheet.”
The method covers a range of running expenses including electricity for lighting, cooling, heating and the running of other electronic items; phone and internet costs; and the depreciation of various items spanning computers, laptops, home office furniture, and other household fixtures that see wear as a result of a taxpayer’s working arrangements.
However, the shortcut is all-inclusive, Mr Loh said, and can’t be supplemented by additional, individual expense claims on items like phone and internet costs and other depreciation claims on items like furniture and laptops.
“If you decide to go with an existing method, I would encourage you to do your research and keep good records,” Mr Loh said.
“Keeping track of each individual expense and calculating the work-related use of each one can be fiddly, so be organised. “So, make sure you’ve read the guidance on our website or chat to your registered tax agent.”
The ATO’s reminder follows a separate call from Moore Australia earlier this week for taxpayers to keep a diligent log of the hours they work from home this year as tax time looms.
“To claim home office deductions using the shortcut method, individuals need to keep a record of actual hours worked at home,” said David Tomasi, chairman of Moore Australia. “The shortcut method is not compulsory, and individuals can still claim based on actual expenses incurred.
“However, they would then have to comply with the necessary, and more complex, record-keeping requirements.”
Tax agents and self-lodgers interested in using the method will need to include a note that reads “COVID-hour rate” in their tax returns, Moore Australia warned.
The Tax Office last extended its simplified working-from-home deduction method in January while New South Wales was reckoning with the containment of a COVID-19 outbreak which sent Sydney’s northern beaches into lockdown.
Introduced last April, it was first due to expire at the end of the last financial year, before it was in June extended to September last year, and then until December.
John Buckley
07 May 2021
accountantsdaily.com.au
Latest Industry News

How Do I Write Legally Compliant Terms and Conditions for My Business?
Terms and conditions bind your customers only where they actively accept them, so a tick box at checkout holds...

Paid parental leave super contributions have started
From July 2026, the new Paid Parental Leave Superannuation Contribution (PPLSC) has started. From...

If the business is no longer profitable, and is unlikely to be profitable in the future, your best option may...

Check out the this visualization, which tracks the evolution of dietary calorie intake from 1930 to...

Taxpayer given 35% penalty for BAS recklessness
Following an application for a refund of nearly $94,000, the Administrative Review Tribunal has set aside an...

SMEs warned as ATO ramps up tax debt collection
One insolvency specialist has emphasised the importance of small businesses engaging their accountants to stay...

Does Your Small Business Need to Follow AML Privacy Rules?
Compliance with new anti-money laundering (AML) laws may subject your small business to additional privacy...

Don’t get caught out at tax time with your multiples jobs
Picking up a second job, holding multiple part-time roles, or doing gig work is now part of everyday life. But...

Global companies turn to cost-cutting amid ongoing inflation
Rising operating costs and persistent inflation are placing renewed pressure on businesses worldwide, despite...

Warning for early lodger this tax time!
The ATO has a clear message this year: slow down and get it right. Early lodgers are far more likely to make...

ATO no longer treating debt the same as during COVID
One expert has stressed the importance of tax agents reminding their clients that the ATO is no longer as...

The evolution of the world’s languages
Check out the evolution of the world's most spoken languages from 2500 BC to...
Latest Guests News

Newsletter Newslettter We are pleased to supply you with the latest edition of Client Alert, which...





























