Updated guidance on R&D claims
.
We've released 2 new taxpayer alerts to warn entities and their advisers about our concerns regarding incorrect Research and Development (R&D) tax incentive arrangements we’re reviewing. These alerts are about expenditure incurred to associated entities and activities conducted overseas for foreign related entities.
We’re concerned these arrangements are being used to:
- claim the R&D tax offset in situations where it would not otherwise be available, either at all or in the income year claimed by the R&D entity
- artificially increase the amount of the R&D tax offset claimed.
We encourage you to read these alerts and consider if your clients need to contact us or make a voluntary disclosure by amending their R&D tax incentive claim.
Penalties may apply to participants of these types of arrangements. These penalties can be significantly reduced if the amendment request is treated as a voluntary disclosure. Generally, the reduction is greater if the disclosure is made before being notified of an examination of your client's tax affairs.
About the alerts
Taxpayer Alert TA 2023/4 Research and development activities delivered by associated entities. We’ve identified arrangements where an entity incorrectly claims the R&D tax offset for expenditure incurred under an agreement with an associated entity who conducts those activities.
Taxpayer Alert TA 2023/5 Research and development activities conducted overseas for foreign related entities outlines our concerns about arrangements where Australian entities claim the R&D tax offset for expenditure incurred on R&D activities conducted overseas. Arrangements of concern include where an R&D entity has purported that R&D activities were conducted for its own benefit, but those activities were instead conducted for a foreign entity that is ‘connected with’, or is an ‘affiliate’, of the R&D entity.
To provide information about this or another type of arrangement, or about a promoter of this or another arrangement, you can:
ATO
14 December 2023
ato.gov.au
2 in 3 SMEs benefit from instant asset write-off, survey reveals
The uncapped version of the instant asset write-off scheme was extremely popular among SMEs with the average spend over $90,000, according to ScotPac.
.
The latest SME Growth Index by ScotPac has shown that 63 per cent of Australian SMEs took advantage of the Uncapped Instant Asset Write Off Scheme in the financial year before the revised $20,000 per asset limit.
Since its introduction more than a decade ago, the Instant Asset Write-Off (IAWO) Scheme has allowed eligible businesses to claim an immediate tax deduction for the purchase of various assets, up to a specified threshold.
At the outset of COVID-19, the federal government increased the IAWO threshold from $30,000 to $150,000 to make it easier for small businesses to benefit from asset purchases. It later removed the cap entirely by introducing temporary full expensing.
It later removed the cap entirely by introducing temporary full expensing.
A revised IAWO threshold of $20,000 per eligible asset was introduced for 12 months from 1 July 2023.
The survey by ScotPac reveals that SMEs ramped up their use of the scheme in the lead-up to the capped version of the scheme.
The average amount spent by SMEs that used the IAWO scheme in the 2022–23 financial year was $91,500.
SMEs with declining or flat growth were the biggest users of the scheme with 68 per cent purchasing eligible assets, compared with 59 per cent of growth SMEs.
NSW and the ACT recorded the most use with 75 per cent of businesses in these states taking advantage of the scheme.
ScotPac CEO, Jon Sutton, said the IAWO scheme has been a major factor in SME decision making on capital expenditure in recent years.
“There is no doubt the Instant Asset Write-off Scheme has achieved its objective of encouraging SMEs to invest in assets to help grow their business,” Mr Sutton said.
“In raw numbers, hundreds of thousands of SMEs were able to claim tax relief worth billions of dollars for assets purchased in 2023-24.
“When you consider the rising costs faced by all businesses in that period, including the cost of critical assets, the Instant Asset Write-off scheme has provided a great boost for SMEs,” Mr Sutton said.
Under the current IAWO threshold, a $20,000 cap applies on an asset-by-asset basis.
Assets valued at more than $20,000 are placed into the small business depreciation pool and depreciated over several years.
Mr Sutton said while there was understandable disappointment that the temporary full expensing measure had ceased, the current IAWO scheme still provided incentives for SMEs to invest in capital.
“Average capital expenditure levels for SMEs are continuing to grow,” he said.
“While recent changes to the scheme have removed the immediate tax benefit for larger items, the $20,000 per asset cap still provides opportunities for SMEs looking to expand or upgrade their asset base.”
Miranda Brownlee
31 January 2024
accountantsdaily.com.au/
GrantConnect
GrantConnect provides centralised publication of forecast and current Australian Government grant opportunities and grants awarded.
.
Click on the links below to find out more about the grants and how to access them.
Labor tweaks stage 3 tax cuts to make room for ‘middle Australia’
Following years of mixed messaging, Labor has bowed to economic pressure and announced changes to its stage three tax cuts.
.
Only those earning less than $150,000 will benefit from the impending tax cuts, which were originally slated to abolish the 37 per cent tax bracket applied to income between $120,000 and $180,000 and reduce the 32.5 per cent tax rate to 30 per cent for all incomes between $45,000 and $200,000.
However, with rising inflation and consequent increases to interest rates, Labor has pivoted to make room for cost-of-living ease for middle Australia, effectively scrapping the already legislated stage three rollout – something Prime Minister Albanese said he would not do going into the last election.
This means that those earning $200,000 or more will receive a $4,529 cut, instead of the legislated $9,075 they were due to receive from 1 July.
Under the changes, the 19 per cent tax rate that applies to incomes between the $18,200 tax-free threshold and $45,000 will be lowered to 16 per cent.
Those earning between $45,000 and $135,000 will be taxed at 30 per cent, while the 37 per cent tax rate will be reinstated and apply to incomes between $135,000 and $190,000, after which the 45 per cent rate will apply.
This means that someone on $73,000 will receive a tax cut over $1,500, more than double the amount under the previous plan, while somebody on $100,000 will have their tax cut increased from $1,375 to $2,179.
On Thursday before the National Press Club, Prime Minister Albanese said: “Our government will deliver a tax cut for every Australian taxpayer”.
“This is a plan for middle Australia that delivers for every Australian taxpayer, right up and down the income ladder,” he said.
The tax cuts won't hurt inflation, he said.
“This option is broadly revenue neutral and will not add to inflationary pressures,” the PM cited a Treasury report and added that there are no implications for the Reserve Bank’s forecasts.
“Some would say that we should stay the course, even if it means going to the wrong destination.
“To them I say, we are choosing a better way forward given the changed circumstances.”
The PM also added that his government will increase the low-income threshold at which the Medicare levy applies.
According to media reports, the government plans to launch an ad campaign to help sell its obvious backflip.
‘Different position for best reason’
Doing the media rounds on Thursday morning, Treasurer Jim Chalmers defended Labor’s surprise move, noting that the government has “come to a different position” for “the best possible reason”, which is “we can provide more tax relief for more people to help them with the cost‑of‑living”.
“Now we are being upfront with people and saying we have come to a different view. We've come to a different view because what we're proposing today is better for middle Australia, better for cost‑of‑living pressures, better for women and workforce participation and better for the economy, without adding to the inflationary pressures that we are dealing with,” Mr Chalmers told ABC Radio.
Questioned about whether these broken promises could be costly for Labor, Mr Chalmers said “what we're doing here is we're putting people before politics”.
“Of course, these will be politically contentious. Our opponents will play their usual mindless, nasty, negative politics over this.
“We understand that but I believe you build trust by making the right decisions for the right reasons in the interests of the people and when you come to a different view, as we have, you front up and explain why the circumstances have changed, why our position has changed and how people will benefit from what we are proposing today”.
In the lead-up to last year’s May budget, Treasurer Chalmers was, however, selling a different story, reinforcing at the time that the government would push ahead with stage three tax cuts.
This story would later shift to suggest that Labor was prepared to re-evaluate the tax cuts if inflation remained an issue.
Maja Garaca Djurdjevic
29 January 2024
smsfadviser.com
Does your business have a company Power of Attorney?
An individual power of attorney gives an attorney legal authority to manage a person’s assets and financial affairs.
.
A company power of attorney authorizes a person or persons to act on behalf of a company and/or sign certain documents on its behalf.
When granting a company power of attorney, it could be:-
- Limited power, for routine transactions
- For specific purposes
- General powers
And, be aware the director will remain liable for an attorney’s actions. The company may want to consider appointing two persons to act jointly as attorney.
A complete estate plan for a family should consider a power of attorney for all companies in the group, in addition to the personal and financial affairs of the individuals involved.
AcctWeb
Accessing superannuation benefits.
Common conditions of release include the fund member having reached preservation age and retired, or commenced a transition-to-retirement income stream; ceasing an employment arrangement on or after the age of 60; being 65 years old even though they haven’t retired; or having died.
.
Alternatively, under special circumstances, some benefits may be available where the fund member: –
• has terminated gainful employment;
• is temporarily or permanently incapacitated;
• is suffering severe financial hardship;
• meets conditions for compassionate grounds;
• has a terminal medical condition; or
• is taking part in the first home super saver scheme.
The Australian Taxation office is aware of scams and improper access, and will continue targeting Self-Managed Super Funds and their trustees.
It is the trustees responsibility to take care and always be prudent.
Acctweb
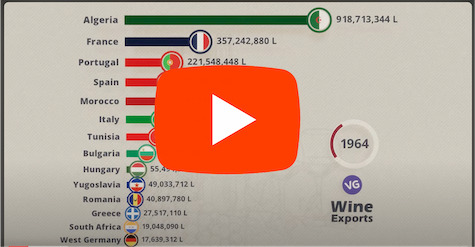
The Countries that Export the Most Wine in the World
Check out the countries that export the most wine in the world
.
.
.
.
.
.
.
.
.
Raft of revenue tweaks in MYEFO to raise millions
Changes to interest deductibility, taxes, thresholds and even passport fees made up the fineprint of the mid-year economic update.
.
Canberra will embellish its budget bottom line by hundreds of millions over the next few years with a raft of policy and revenue tweaks in the fine-print of its Mid-Year Economic and Fiscal Outlook, released yesterday.
High on the list in terms of financial impact will be the denial of deductions for the ATO general interest charge (GIC) and shortfall interest charge (SIC) incurred in income years starting on or after 1 July 2025.
GIC is incurred when tax debts have not been paid on time while SIC is charged when a tax liability has been incorrectly self-assessed and resulted in a shortfall of tax paid. Both charges have increased in line with rising interest rates and are adjusted quarterly but compound daily. The SIC for January to March next year will be 7.38 per cent and for GIC 11.38 per cent.
The MYEFO said removing tax-deductibility would “enhance incentives for all entities to correctly self-assess their tax liabilities and pay on time, and level the playing field for individuals and businesses who already do so”.
The measure was estimated to increase receipts by $500 million over the five years from 2022–23.
Canberra would also supplement its recently announced increased fees for foreign real estate investment with a rise in the foreign resident capital gains withholding tax rate from 12.5 per cent to 15 per cent and reduction in the threshold from $750,000 to zero.
The tax applies when a foreign resident sells real estate and requires the purchaser to withhold a percentage of the price and remit that to the ATO.
“The measure will complement the government’s initiatives to improve housing affordability for Australians,” the MYEFO said.
The changes would apply to contracts entered into from 1 January 2025 and was forecast to increase receipts by $150 million, and increase payments by $5.9 million, over the five years from 2022–23.
Meanwhile, for those eligible to hold an Australian passport application fees would increase by 15 per cent from 1 July 2024, raising $349 million over three years that would be “redirected to support priorities in the Foreign Affairs and Trade portfolio”.
To encourage the take-up of “fuel-efficient vehicles” the government would tighten the definition for the purposes of the Luxury Car Tax, reducing the maximum fuel consumption from 7 litres per 100km to 3.5.
Luxury cars that meet the definition have a higher threshold for LCT, which is levied at 33 per cent.
The government would also update the indexation rate of the LCT value threshold for other luxury vehicles from headline CPI to the motor vehicle purchase sub-group CPI, aligning it with the indexation of the LCT value threshold for fuel-efficient vehicles.
The measures would apply 1 July 2025 and increase receipts by $155 million over the five years from 2022–23.
Also in line for an increase was the Commonwealth penalty unit, which would rise by 5.4 per cent from $313 to $330 starting four weeks after passage of legislation.
The increase would apply to offences committed after the relevant legislative amendment came into force and the amount would continue to be indexed every three years in line with the CPI as per the pre-existing schedule.
Penalty units are used to describe the amount payable for fines under Commonwealth laws, including in relation to communication, financial, tax and fraud offences.
“This measure ensures that financial penalties for Commonwealth offences continue to remain effective in deterring unlawful behaviour,” the MYEFO said and was estimated to increase receipts by $4.5 million over five years from 2022–23.
Philip King
14 December 2023
accountantsdaily.com.au
How to Resolve Invoice Payment Disputes
As a business owner, managing your debtors and improving your cash flow are crucial to the success of your business.
.
Therefore, you must take proactive steps to avoid customer payment disputes and prevent cash-flow issues. This article explains how to avoid or resolve invoice payment disputes.
Draft Effective Business Terms and Conditions
A customer enters a binding contract each time they buy from you. A written contract setting out the terms of that transaction provides clarity and can reduce the risk of invoice payment disputes arising. Here are four top tips for writing your business terms and conditions:
| Tip |
Explanation |
| Be clear about what products or services you sell |
The more detail you provide about your goods or services, the more customers know what they are getting. This may help if a dispute arises and they try to avoid payment. |
| Dictate how your client or customer can accept your business terms and conditions |
Once they accept, your customer will be bound by your terms and conditions. Standard acceptance methods include signing, ticking an acceptance box online, confirming in writing or paying a deposit. Choose the method that best suits your business and your customers. |
| Set out your payment terms and acceptable methods of payment |
Payment terms should indicate the timeframe in which you require the customer to make payment. You should also set out the consequences if the customer fails to pay on time, such as being charged interest on overdue amounts. |
| Include a dispute resolution clause |
In the unfortunate event that a dispute does arise, a dispute resolution clause can assist you in resolving the dispute faster and more cost-effectively. Dispute resolution clauses usually require an attempt at Alternative Dispute Resolution before escalating the matter further. |
Your business terms and conditions are essential in managing your debtors. Therefore, you (or your lawyer) should draft these terms specifically for your business. They will form the foundation for any future debt recovery proceedings. It is far easier to point to terms and conditions in an agreement than to rely on a verbal agreement or informal email chain.
Avoid Delays and Always Follow Up
Issue invoices promptly while the transaction remains fresh in your customer’s mind. The invoice should contain sufficient detail about the goods or services you have provided to avoid confusion.
Once an invoice becomes due, be sure to follow up. You may only need to give customers a friendly reminder by email or phone.
Additionally, diarising when accounts become due or implementing an automatic notification system into your accounting software are great ways to keep on top of debtors.
Keep Communicating
Keeping the lines of communication open with a customer who owes you money is essential. If those lines of communication close, it is unlikely that you will receive payment without escalating the matter further. Some tips for keeping communication open:
- resend a copy of your outstanding invoice;
- remain calm as disputes tend to escalate quickly (sometimes unnecessarily) when emotions are left unchecked;
- speak with the person responsible for paying your invoice;
- confirm in writing the amount outstanding and when payment was due;
- ask questions and listen. There may be a reason your invoice has not been paid; and
- keep a paper trail. If you start debt recovery proceedings later, you can use this trail as evidence.
However, even after doing everything in your power to coerce payment, escalating your debt recovery to a lawyer may be your best option. In this case, issuing a letter of demand is the next step.
Key Takeaways
Resolving invoice payment disputes quickly can improve your business’s cash flow by ensuring you receive money owed in time to pay your debts. You can increase the odds of customers paying on time by having well-drafted terms and conditions, following up promptly and keeping communication open.
Meryem Aydogan
Law Graduate
legalvision.com.au
Why crypto treads an uncertain path through tax minefield
The taxation of digital assets used for lending and borrowing would benefit from clear-sighted guidelines.
.
The ATO has not released much formal (binding) guidance on the taxation treatment of crypto assets and continues to slowly publish general (non-binding) advice via its website. Additionally, the BoT’s report following its review into the appropriate policy framework for the taxation of digital assets was delayed beyond December 2022 and is now due by 29 February 2024.
Against this backdrop, the ATO has recently published some new informal guidance on its website concerning the tax treatment of lending and borrowing with decentralised finance (DeFi) with a focus on liquidity pools.
DeFi and liquidity pools
DeFi is a blockchain-based form of finance that does not rely on a financial intermediary. Instead, it is peer-to-peer with many apps, protocols and platforms commonly built on the Ethereum blockchain.
A liquidity pool is an arrangement whereby crypto assets are gathered and “locked” in place with a smart contract. The use of liquidity pools facilitates decentralised lending and adds liquidity to crypto asset trading.
A lender provides crypto assets to the liquidity pool for use by the DeFi protocol and typically receives new crypto assets as compensation (generated from transaction fees and often described as “interest”).
Tax treatment
Crypto lenders typically understand that the market value of the interest they receive is taxable. What they may find alarming is that the ATO also considers that the mere act of depositing (lending) the crypto assets into a liquidity pool amounts to a disposal of the crypto asset, thereby triggering CGT event A1.
CGT event A1 occurs because, in the ATO’s view, depositing the crypto asset into a liquidity pool results in a change in beneficial ownership.
Whether or not investing (depositing) into a particular liquidity pool results in the lender relinquishing (and so transferring) beneficial ownership of the crypto asset will depend on the precise terms of the underlying protocol. Retaining a right to withdraw will not necessarily mean the depositor has retained beneficial ownership.
If the lender only has a contractual right to withdraw the deposited asset, then beneficial ownership will most likely have transferred. On the other hand, if, for example, a “trust relationship” is established, it may be possible that the depositor has retained beneficial ownership.
The creation of a trust relationship does not necessarily mean that there has been no change in beneficial ownership. The High Court has held that the trustee of a unit trust – and not the beneficiaries of that trust – holds the beneficial ownership of trust assets. However, the types of trusts to which the High Court was referring can be distinguished from other trust relationships such as a special type of trust known as a bare trust, where the beneficiary – and not the trustee – will continue to hold beneficial ownership of the trust’s assets.
The existence of a bare trust may be incompatible with the commercial reality of a DeFi protocol, which may require all the deposited assets to be mixed. Given the assets are homogenous and fungible, depositors may otherwise be indifferent as to whether the assets are mixed and so whether their subsequent withdrawal contains the exact same assets they deposited or merely equivalent ones (like depositing $20 in a bank account and then withdrawing another $20 note). In this respect, the mixing of the assets may not only reveal the lack of a bare trust arrangement but may also help explain the risk profile of the investment.
Other arrangements may fall short of transferring beneficial ownership and should not trigger CGT event A1, such as where the crypto assets are merely offered as collateral.
Interest-earning bank account
As alluded to above, the analogy of a bank account may not assist crypto liquidity pool investors. Technically, depositing funds into a bank account would trigger CGT event A1 but for the Commissioner’s indulgence in Taxation Determination TD 2002/25, where he states that he does not regard Australian currency as a CGT asset to the extent it is used as legal tender to facilitate a transaction. Without that indulgence, there would – arguably – be a disposal of the notes and coins (a change in beneficial ownership) in exchange for a new asset, being the chose in action/bank account. Crypto assets will not attract this indulgence as they are not Australian currency being used as legal tender.
Foreign currency
Foreign currencies have their own regime and so are typically taxed outside of the CGT regime. Yet the Commissioner has never accepted that cryptocurrencies are a foreign currency, and that position has since been enshrined in legislation.
In ATO ID 2003/551, the Commissioner states that the definition of a CGT asset includes a bank account denominated in foreign currency. Depositing foreign currency into that account increases its cost base, and withdrawing the foreign currency triggers CGT event C2 from a cancellation of part of the debt owing under that chose in action/bank account.
Takeaway
There is limited formal ATO guidance to help crypto users and their advisers understand the taxation consequence of various DeFi (and other crypto) arrangements.
The ultimate tax position will depend on the particular terms of the protocol and what rights and obligations they confer on the parties.
The BoT is due to release its report this month, which will hopefully pave the way for important legislative reform so that crypto assets are not taxed any more harshly than more traditional financial assets.
In the meantime, crypto users and creators need to ensure that they obtain advice on the taxation ramifications of their crypto arrangements. As the above analysis shows, the legal position and the corresponding taxation implications are not straightforward.
Philip King
02 February 2024
accountantsdaily.com.au











































